


Rocket Lab has seen its share price fall sharply in recent weeks after a very large multi year gain, which puts fresh focus on whether the current valuation still lines up with its sales base. With sentiment swinging around launch delays, defense contracts and satellite ambitions, investors are increasingly asking how much revenue the market is paying for today.
- Over the past 3 years the stock has delivered a very large return of about 7x, so any reassessment of what its sales are worth now matters a lot for holders who have ridden that move.
- Rocket Lab's Space Systems arm is now generating far more revenue than its launch activity and the planned Iridium Communications acquisition may support a larger and more recurring sales mix that could influence how investors think about its price to sales profile over time.
- Your read on Rocket Lab is one view; the desks covering it have another. See what analysts think Rocket Lab's shares could be worth.
The issue now is whether Rocket Lab's current share price can be explained by its sales when set against this mix of sharp recent volatility and a business model leaning more on recurring space systems revenue.
If you are weighing Rocket Lab against other potential ideas, a focused stock screen built around 42 high quality undervalued stocks can be a useful next step in your research.
Has Rocket Lab Run Too Far on Sales?
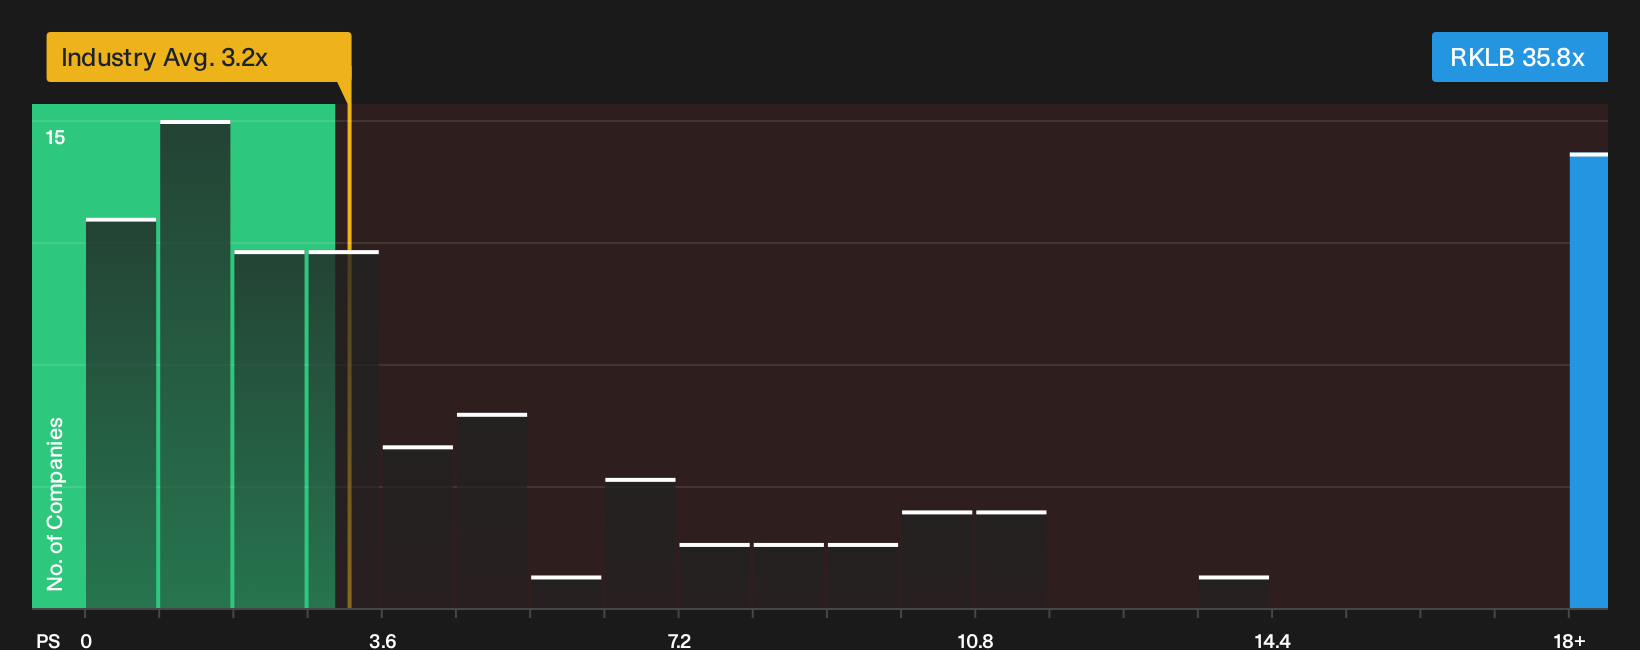
P/S fits Rocket Lab because it is still loss making on free cash flow and earnings, so investors are mostly paying for revenue today. On that score, the stock trades on a P/S of 35.8x, which is far above the Aerospace & Defense sector average of 3.2x and well ahead of the 8.6x peer group mark.
The fair multiple model, which adjusts for Rocket Lab's growth profile, margins, size and risk, points to a materially lower P/S than the current level. The shares screen as overvalued on this framework and the gap is wide enough to read as a warning rather than a precise target. Because the Neutron delay to 2027 has already hit sentiment, the fact that the P/S still sits this far above sector and peer references suggests investors are paying a steep premium for the future space systems and Iridium driven story rather than the current sales base. Explore the numbers behind Rocket Lab's P/S valuation.
The Rocket Lab Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Rocket Lab pick up where the valuation puzzle leaves off by spelling out what growth, margin and earnings paths would need to hold for the stock to end up worth materially more or less than today's price, and they sit on the platform's Community page. Rather than relying on a single multiple, each narrative lays out the assumptions behind its view of fair value so you can track those against Rocket Lab's actual results over time.
Rocket Lab brings out sharply different views in the community, with one camp seeing a long runway while the other worries the price already bakes in a lot of success.
Bull case: 53% undervalued
"Rocket Lab USA seeks to vertically integrate itself throughout the $800 billion space 'backbone' in order to attract the customers operating within that $1 trillion top component…"
Discover why this Narrative puts Rocket Lab at 53% undervalued.
Bear case: 183% overvalued
"The entire valuation is 'priced for perfection,' which means any delay causes volatility…"
Explore why this Narrative puts Rocket Lab at 183% overvalued.
One more Rocket Lab check that sits outside the price charts
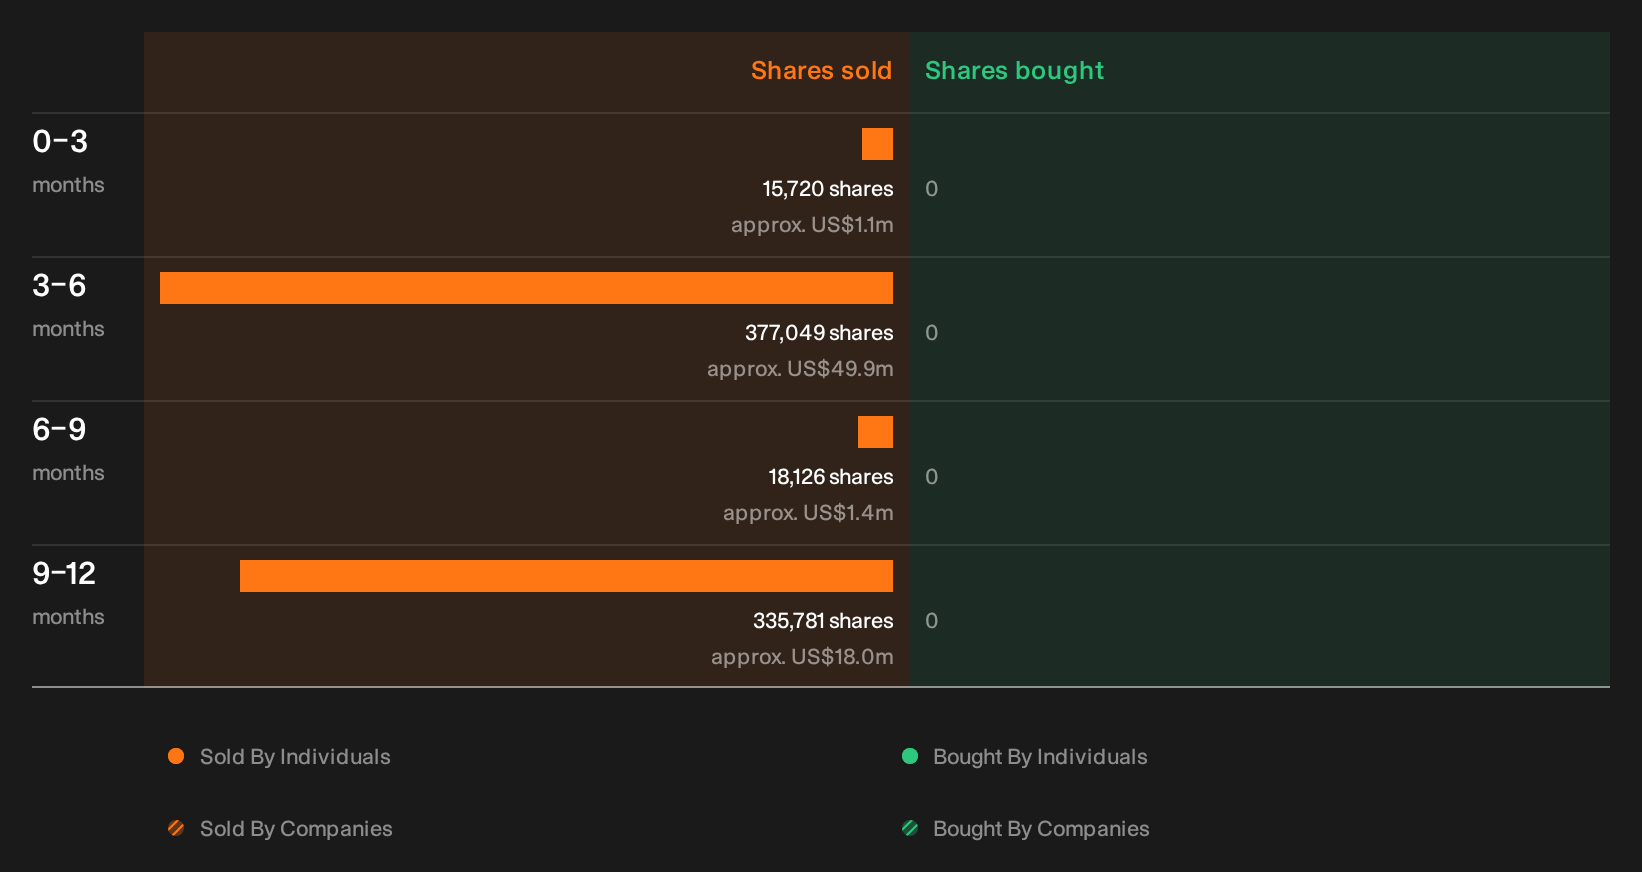
Before moving on from Rocket Lab, it is worth knowing that recent transactions by people inside the business have been flagged by our checks, with the specific sellers, trade sizes and possible signals left for you to review. See the recent insider selling flagged for Rocket Lab.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com