


Valued at $134.3 billion by market cap, Medtronic plc (MDT) is a global medical technology company that develops, manufactures, and sells medical devices, equipment, and technology-driven healthcare solutions. Headquartered in Galway, Ireland, the company serves healthcare providers and patients in more than 150 countries, offering products used to diagnose, treat, and manage a wide range of medical conditions.
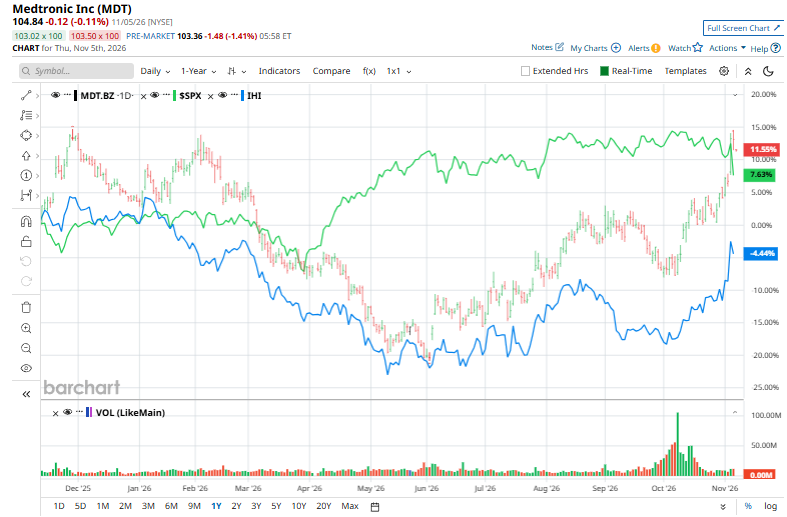
Shares of this medical devices giant have outperformed the broader market over the past year. MDT has soared 15% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 8.6%. In 2026, MDT stock is up 8.3%, compared to the SPX’s 7.8% rise on a YTD basis.
Narrowing the focus, MDT’s outperformance is apparent compared to the iShares U.S. Medical Devices ETF (IHI). The exchange-traded fund has declined 3.3% over the past year. Moreover, MDT’s single-digit YTD rise outshines the ETF’s 5.7% losses over the same time frame.
Medtronic's shares jumped 1.3% on Oct. 15, after the company completed the separation of its diabetes business, MiniMed Group Inc. (MMED), which began trading as an independent publicly listed company. The transaction eliminated Medtronic's equity stake in MiniMed through an exchange offer in which Medtronic shareholders swapped approximately 55 million Medtronic shares for 253 million MiniMed shares. The offer was 5.4 times oversubscribed, highlighting strong investor interest in the newly independent diabetes care company.
For the current fiscal year, ending in April 2027, analysts expect MDT’s EPS to grow 8.1% to $5.98 on a diluted basis. The company’s earnings surprise history is impressive. It beat the consensus estimate in each of the last four quarters.
Among the 29 analysts covering MDT stock, the consensus is a “Moderate Buy.” That’s based on 14 “Strong Buy” ratings, two “Moderate Buys,” and 13 “Holds.”
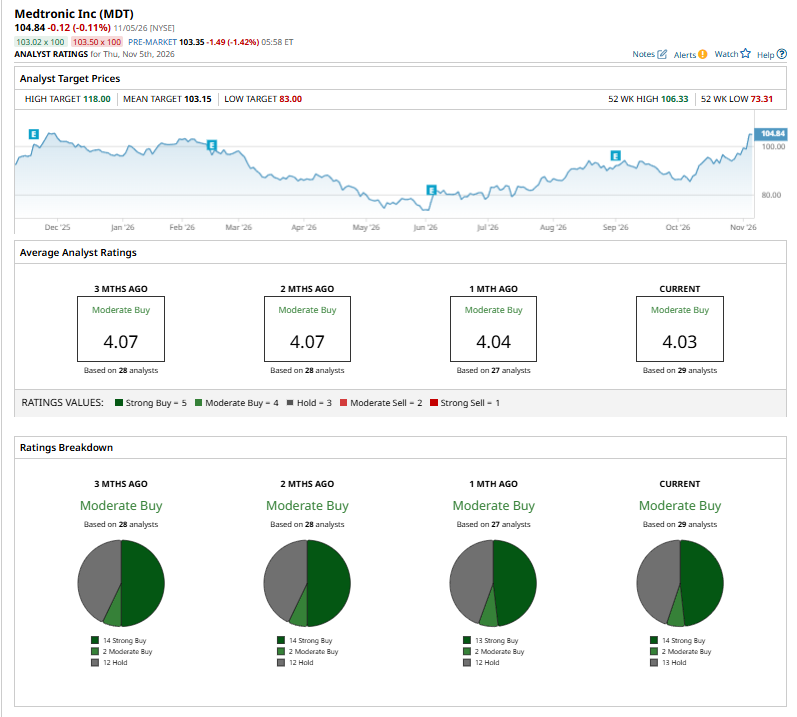
This configuration is more bullish than a month ago, with 13 analysts suggesting a “Strong Buy.”
On Sept. 2, Stifel analyst Rick Wise raised Medtronic’s price target to $95 from $80 while maintaining a “Hold” rating. The analyst cited a strong start to fiscal 2027, supported by another impressive quarter from its Cardiac Ablation Solutions business.
While the stock currently trades above its mean price target of $103.15, the Street-high price target of $118 suggests an upside potential of 12.6%.
On the date of publication, Kritika Sarmah did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.