


Why Sensirion Holding’s latest medical sensor launch matters now
Sensirion Holding (SWX:SENS) has just rolled out its SFM3304-D gas flow sensor globally, targeting mechanical ventilation and respiratory care, putting fresh attention on how its medical portfolio could influence the stock.
The device is designed for use close to patients in ventilation, smart resuscitation and medication nebulization. It builds on the prior SFM3300-D design with a reworked flow path and a newer sensor chip.
Investors watching Sensirion Holding may focus on how this single use product, sold through channel partners worldwide, fits into the wider sensor business that serves automotive, industrial, consumer and medical customers.
The fresh product launch comes after a volatile period for Sensirion Holding’s share price. It is down 17.9% over the past month and 13.8% over the last week. However, the year-to-date share price return is 21.9% and the 1-year total shareholder return is 34.0%. This suggests that near-term momentum has cooled, while the longer-term picture has been stronger for patient holders.
Activate your watchlist by comparing Sensirion Holding’s medical sensor push with a curated group of resilient hardware and components players screened as 214 resilient stocks with low risk scores.The share price has slipped hard in recent weeks even as Sensirion Holding reports rising revenue and net income. Do those fundamentals still justify paying CHF 75.60, or has the risk reward tilted away from new buyers?
Most Popular Narrative: 14% Undervalued
Against the latest close of CHF 75.60, the most followed narrative pegs Sensirion Holding’s fair value at CHF 88.25, which frames the recent pullback as a disconnect between price and the long term sensor story.
The market leadership in A2L refrigerant leakage sensors for HVAC systems directly addresses new U.S. and international regulations around climate-friendly, low-global-warming-potential refrigerants. This positioning supports demand as regulatory frameworks tighten and is associated with stable to rising topline and margin resilience.
See why 5 investors see Sensirion Holding as 14% undervalued.
Result: Fair Value of CHF 88.25 (UNDERVALUED)
Still, Sensirion Holding’s story can wobble if currency swings dent earnings again or if A2L sensor demand normalizes faster than analysts anticipate.
Find out about the key risks to this Sensirion Holding narrative.
Another view on Sensirion Holding’s valuation
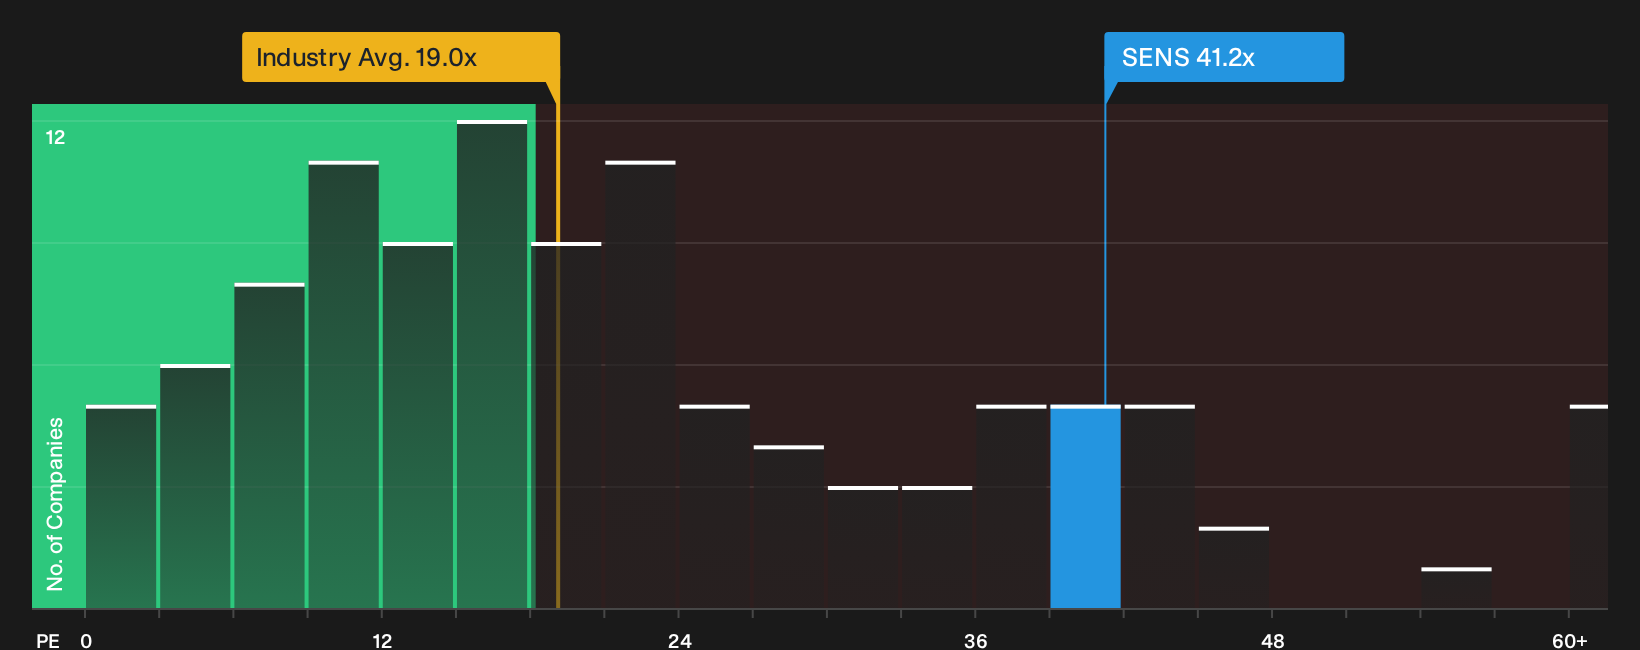
The fair value narrative presents Sensirion Holding as 14% undervalued at CHF 88.25. The market, however, is currently pricing the shares at a P/E of 41.2x, which is more than double the European Electronic sector at 20x and well above its own fair ratio of 27.8x. That gap may indicate notable valuation risk if sentiment cools.
Before relying on any single price target, it can be useful to stress test this higher P/E against earnings quality, sector comparisons and your own expectations, then decide whether the premium still feels appropriate. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around Sensirion Holding leaves you uncertain, it may be helpful to move quickly from headline impressions to hard numbers and primary sources. To see both sides set out clearly, review the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Sensirion Holding?
If Sensirion Holding has sharpened your focus on quality and price, broaden your watchlist with a few targeted idea lists built from hard numbers, not hype.
- Hunt for resilient value by scanning a curated set of 230 high quality undervalued stocks that combine appealing valuations with stronger fundamentals than the broader market.
- Strengthen your downside protection by reviewing a list of solid balance sheet and fundamentals (193 results) that can help you focus on financially robust businesses when conditions turn rough.
- Stay a step ahead of the crowd by checking a 591 high quality undiscovered gems before attention and capital rush to the same crowded tickers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com