


- Neogen reported first quarter fiscal 2027 adjusted earnings and revenue that were above expectations, alongside higher guidance for full year revenue and adjusted EBITDA.
- The update highlighted better gross profit, stronger cash flow, and further debt reduction, which together point to tighter cost control and a more resilient balance sheet for Neogen.
- We now examine how Neogen's stronger guidance and margin progress could influence the longer term investment narrative for investors.
Compare Neogen's tighter cost control and legal scrutiny with other businesses that have resilient balance sheets and disciplined execution by scanning the 32 resilient stocks with low risk scores in the same sitting.
Neogen Investment Narrative Recap
To own Neogen, you need to believe the long term demand for food and animal safety testing remains intact while the business keeps tightening execution. The recent beat and higher guidance support the idea that operational fixes in areas like inventory and production are starting to show through. In the short term, the key swing factor is whether those efficiency gains can keep offsetting a soft backdrop in parts of Animal Safety.
The largest risk right now sits around regulatory and legal exposure. The FDA warning and the Pomerantz securities investigation bring product quality, disclosure, and compliance to the foreground. If issues stay contained to HYCOAT and Neogen executes on remediation, the core food safety testing thesis is less affected. A broader regulatory overhang would be a different story.
The HYCOAT episode is the most relevant development for you to track alongside the positive Q1 numbers. Management had already been focusing investors on better gross profit, stronger cash flow, and lower debt. Those operational gains matter more now because they build some financial resilience while the business addresses the FDA warning and any fallout from the Pomerantz review.
From here, the operational lens becomes very practical. Watch how Neogen handles product quality controls, recall processes, and communication with regulators, since any misstep could weigh on Animal Safety and slow progress on the wider food diagnostics opportunity. At the same time, investors will likely keep an eye on whether integration work around 3M Food Safety and Petrifilm still tracks with margin goals in spite of this extra scrutiny.
Neogen's narrative projects US$896.0 million revenue and US$112.7 million earnings by 2029. This implies relatively flat yearly revenue growth and an earnings increase of about US$120.6 million from today's earnings, which currently stand at a US$7.9 million loss.
Discover how Neogen's fair value points to a 20% potential upside from its current price before the gap closes.
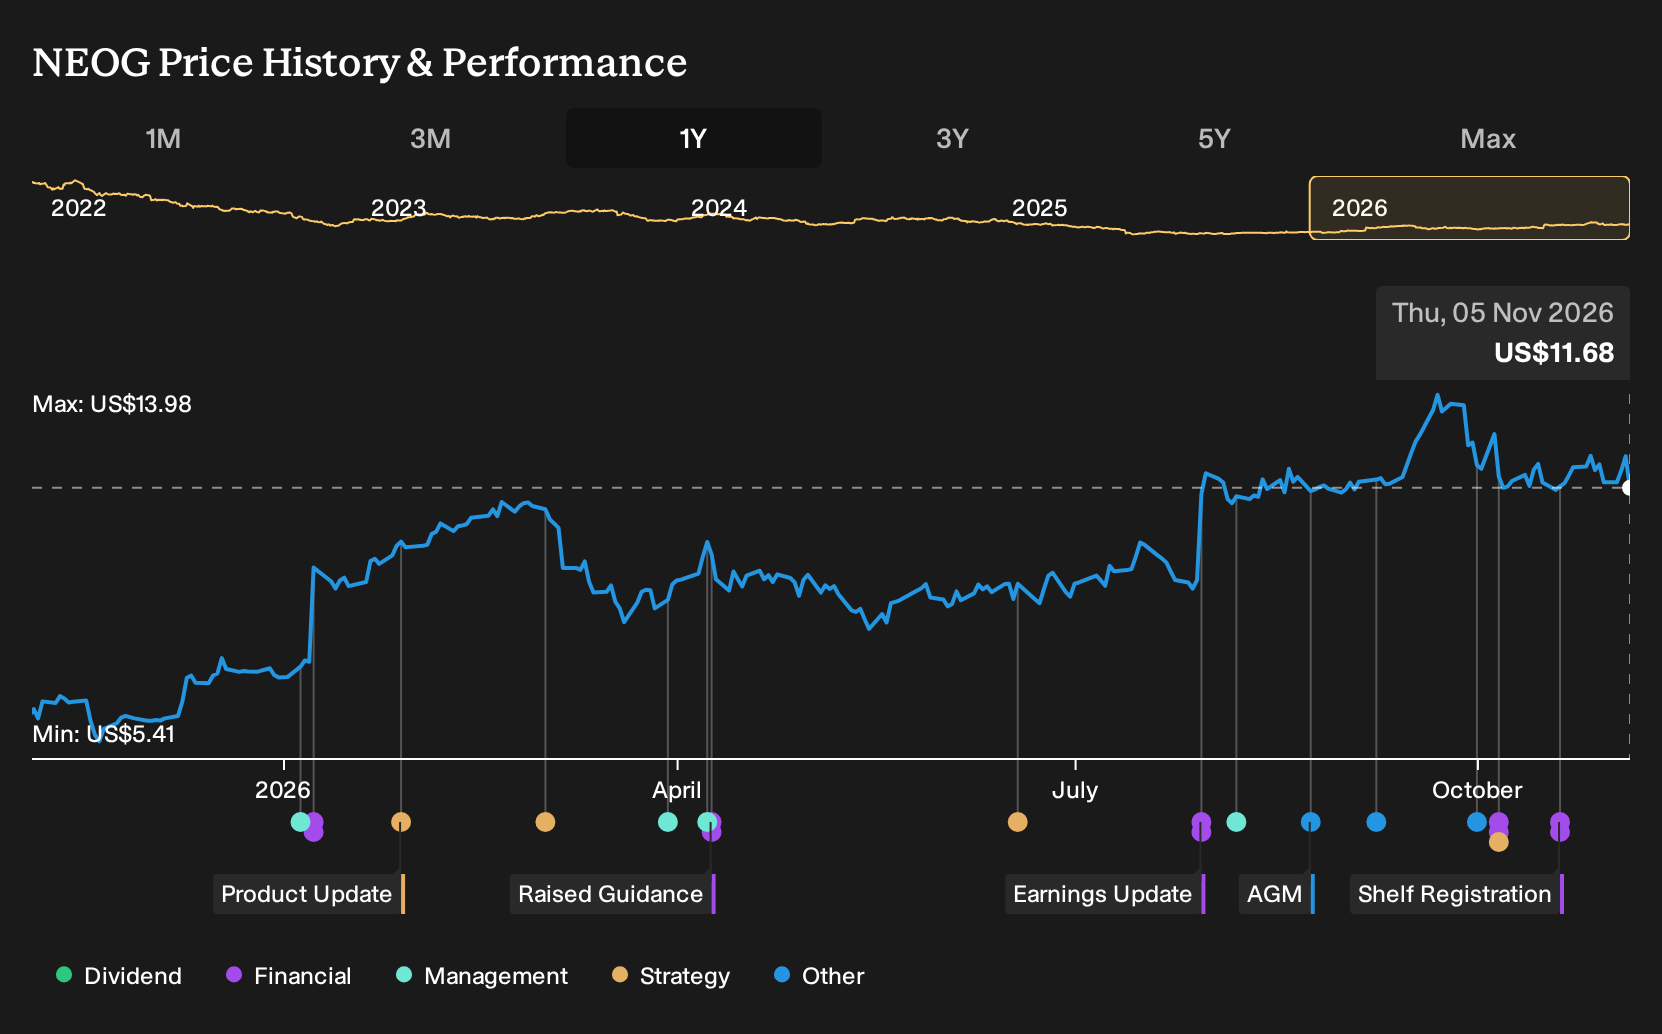
Exploring Other Perspectives
You are seeing a clear split in how people view Neogen. The most cautious analysts focus on regulatory risk from HYCOAT and the securities investigation, and had already been penciling in revenue of about US$866.7 million and earnings of US$29.2 million by 2029 before this news. Those forecasts and today’s developments may look very different once fresh views come through, so it helps to compare several narratives, not just one.
Explore another Neogen fair value estimate, including one that suggests there may be as much as 20% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Neogen research is our analysis highlighting 1 key reward that could impact your investment decision.
- See our latest analysis for Neogen. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Neogen's overall financial health at a glance.
Looking for more investment ideas beyond Neogen?
If Neogen has you thinking about risk, balance sheets, and long term potential, it can help to line it up against a wider watchlist of opportunities using the Simply Wall St Screener.
- For investors who want steadier profiles with room to compound, consider a 21 high quality undiscovered gems that pair solid fundamentals with quieter market attention.
- If resilience and financial strength sit at the top of your checklist, filter for companies with robust balance sheets using this list of solid balance sheet and fundamentals (24 results) to anchor the core of your portfolio.
- Income focused readers who care about reliability can focus on cash return potential by scanning this 6 dividend fortresses that meet a 5%+ yield hurdle.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com