


Alliance Resource Partners has seen its unit price move around in recent weeks, yet the real question for investors is whether that latest quote still lines up with the earnings power of the business. With a long run of returns already on the table and fresh financial news in play, the focus naturally shifts to what buyers today are paying for each dollar of profit.
- Over the past 5 years, Alliance Resource Partners has returned about 271.9%, which puts a lot of past success on the line when you ask if the current valuation is still grounded in its earnings.
- Recent financial updates, including a declared cash distribution of US$0.60 per unit and comments around strong coal sales and Oil & Gas Royalties, can shape how sustainable the partnership's earnings profile looks and how investors think about its ability to keep funding payouts from profits.
- Your read on Alliance Resource Partners is one view; the desks covering it have another. See what analysts think Alliance Resource Partners's shares could be worth.
The issue now is whether Alliance Resource Partners' current price fairly reflects its earnings when set against the Fair Ratio benchmark.
If you are weighing Alliance Resource Partners against other income focused ideas, a targeted starting point is a list of 6 dividend fortresses.
Does Alliance Resource Partners Look Undervalued on Earnings?
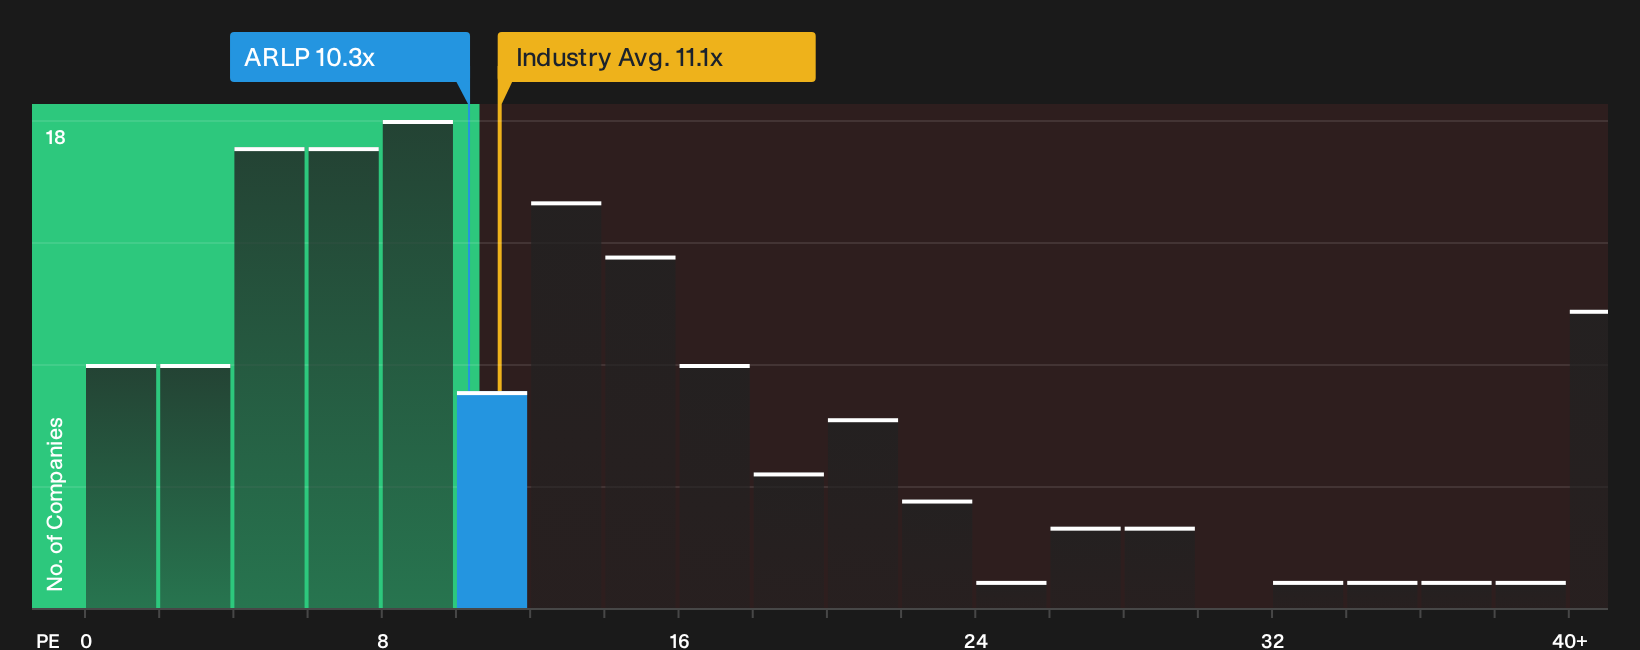
The P/E ratio is a useful shorthand for Alliance Resource Partners because earnings remain the key anchor for how this partnership is valued. Right now the units trade at roughly 10.3x earnings, which sits just under the Oil and Gas sector average of about 11.1x and well below the broader peer group closer to 23.4x. On this measure the stock changes hands at a lower price per dollar of profit than many comparable businesses.
Because the Fair Ratio framework looks at factors like profitability, risk and size for Alliance Resource Partners, it suggests a higher multiple might be justified than the current 10.3x. Despite strong third quarter 2026 results and a declared US$0.60 per unit cash distribution, the market price still values the partnership at a discount to what this tailored benchmark implies. Explore the numbers behind Alliance Resource Partners's P/E valuation.
The Alliance Resource Partners Narrative: What Would Justify Today's Price?
Alliance Resource Partners' valuation puzzle turns into a set of concrete "if this, then that" paths once you move into Simply Wall St Narratives, which lay out what kind of future for volumes, margins and overall earnings would need to hold for the units to be worth materially more or materially less than today’s price on the Community page. Where a single ratio offers one point estimate, these storylines spell out the business outcomes that figure relies on so you can watch how reality compares over time.
One of the top community narratives on Alliance Resource Partners: 21% undervalued
"Robust coal contracting, with 2026 volumes essentially fully committed and priced and 29.4 million tons already committed and priced for 2027..."
Discover why this Narrative puts Alliance Resource Partners at 21% undervalued.
The price is only one piece of the Alliance Resource Partners puzzle
Market ratios tell you what you pay today, but analyst projections sketch out where earnings and cash flows could be a few years from now and how that compares with this valuation snapshot. Explore where analysts expect Alliance Resource Partners to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com