


Why this new cancer trial matters for Erasca stock
Tango Therapeutics and Erasca (ERAS) have started a Phase 1/2 trial combining PRMT5 inhibitor vopimetostat with pan RAS molecular glue ERAS-0015 in MTAP-deleted pancreatic and RAS-mutant lung cancers.
The study focuses on dose finding, safety and early antitumor activity for this dual targeted approach. This puts fresh attention on Erasca’s clinical pipeline and the potential role of ERAS-0015 in difficult solid tumors.
Erasca’s share price has been volatile around this update, with the stock falling 11% over the past day and 28% over 90 days. However, it has still posted a strong year-to-date share price return alongside a very large 1-year total shareholder return that reflects earlier oncology pipeline optimism.
Scan beyond Erasca and this single trial update by reviewing a curated set of oncology and biotech names in the 21 high quality undiscovered gems that are still flying under most investors’ radar.
Erasca now trades at a steep discount to the average analyst price target, even after the sharp pullback. Investors may therefore ask where a reasonable fair value range falls between the current price and that cluster of estimates.
Most Popular Narrative: 45% Undervalued
The most followed valuation view puts Erasca’s fair value at $24.11, compared with a last close of $13.27, which is a wide gap for any clinical stage biotech focused on one primary asset.
The main factor that needs to go right is that ERAS-0015 converts its early efficacy and tolerability profile into successful global registration-enabling trials while managing safety, regulatory scrutiny, and intellectual property disputes.
The current valuation implies that the market heavily discounts Erasca despite analyst price targets in the $18 to $24 range and large institutional buying, which is consistent with a view that the stock is undervalued and the setup is favorable.
See why 2 investors see Erasca as 45% undervalued.
Result: Fair Value of $24.11 (UNDERVALUED)
Still, the bull case for Erasca quickly encounters trial risk and the possibility that safety events or legal setbacks derail expectations for ERAS-0015.
Find out about the key risks to this Erasca narrative.
Another View: Erasca valuation through the P/B lens
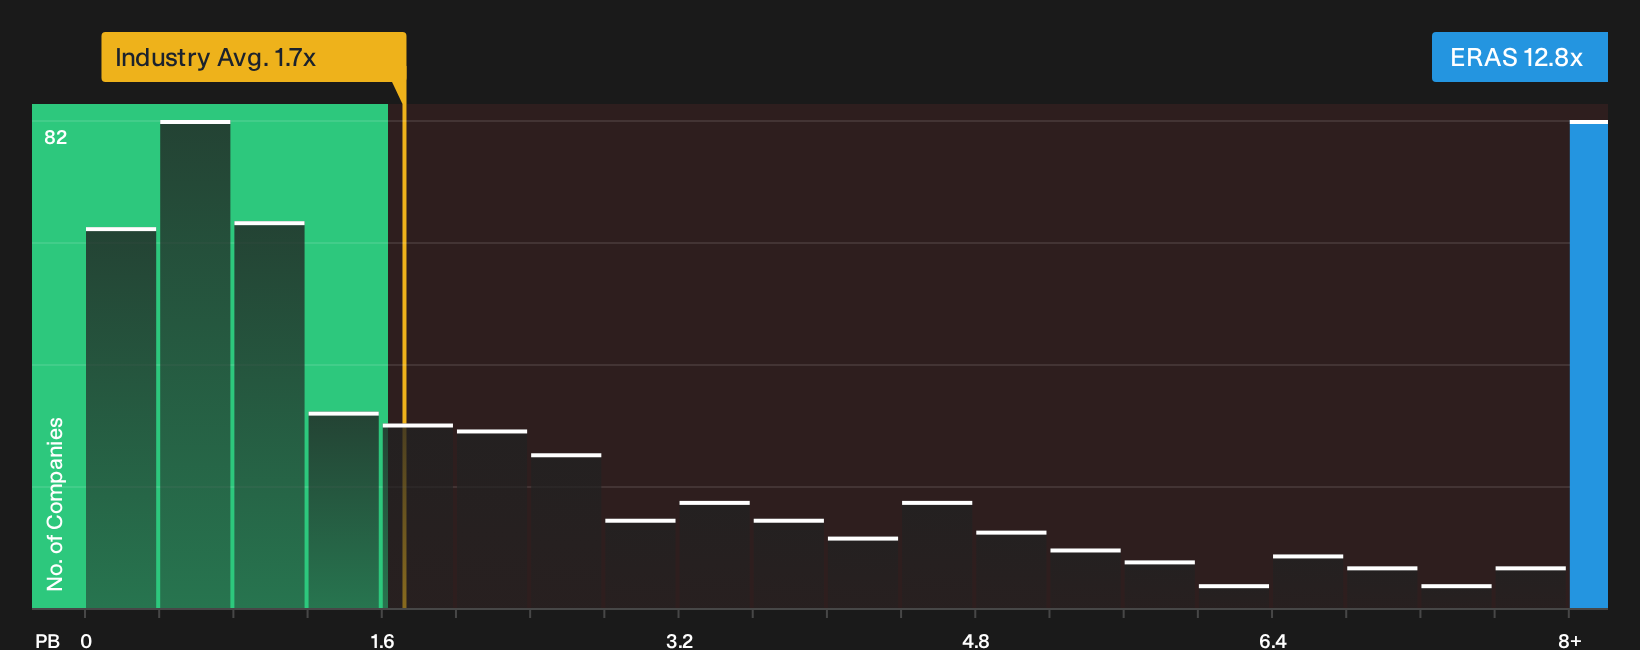
The analyst narrative points to Erasca trading well below a $24.11 fair value, yet the P/B ratio tells a tougher story. At 12.8x, the stock is far more expensive than the US Biotechs industry on 1.7x, even if it still sits below a peer group average of 60.8x.
That wide gap between Erasca’s own P/B and both the sector and its closest rivals points to real valuation risk if sentiment cools or trial news disappoints. It also raises a simple question for you as an investor: Which signal carries more weight, the target-driven upside case or a premium multiple on a business with no revenue today?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mix of enthusiasm and caution around Erasca feels hard to reconcile, act quickly, review the underlying data, and pressure test every assumption against the 3 important warning signs.
Looking for more Erasca-sized investment ideas?
If Erasca has sharpened your focus on risk and opportunity, do not stop here. Use the Simply Wall Street Screener to quickly surface fresh, data driven ideas before the crowd.
- Target resilient potential by scanning a 32 resilient stocks with low risk scores that can help you keep portfolio swings in check when sentiment turns fast.
- Hunt for quality at a discount with the 42 high quality undervalued stocks and spot companies where fundamentals and current prices look out of sync.
- Build staying power into your holdings by reviewing a list of solid balance sheet and fundamentals (24 results) that can better handle shocks without constant refinancing risk.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com