


Xencor has logged a sharp move in its share price over the past year, which raises a straightforward question for you as an investor. Is the recent enthusiasm around the stock matched by what the business is actually generating in sales today?
- The stock is up 143.2% over the past year, putting real pressure on the question of whether the current valuation can be backed by the revenue base.
- Fresh profit and revenue figures that came in ahead of analyst expectations may support a case for stronger future sales and cash generation than the market once assumed.
- The analysts covering Xencor have run their own numbers. See what analysts think Xencor's shares could be worth.
The issue now is whether Xencor's recent share price level is justified by its sales when measured against the Fair Ratio benchmark.
If you want to test this same sales based valuation question beyond Xencor, scan the wider market using the 42 high quality undervalued stocks.
Has Xencor Run Too Far on Sales?
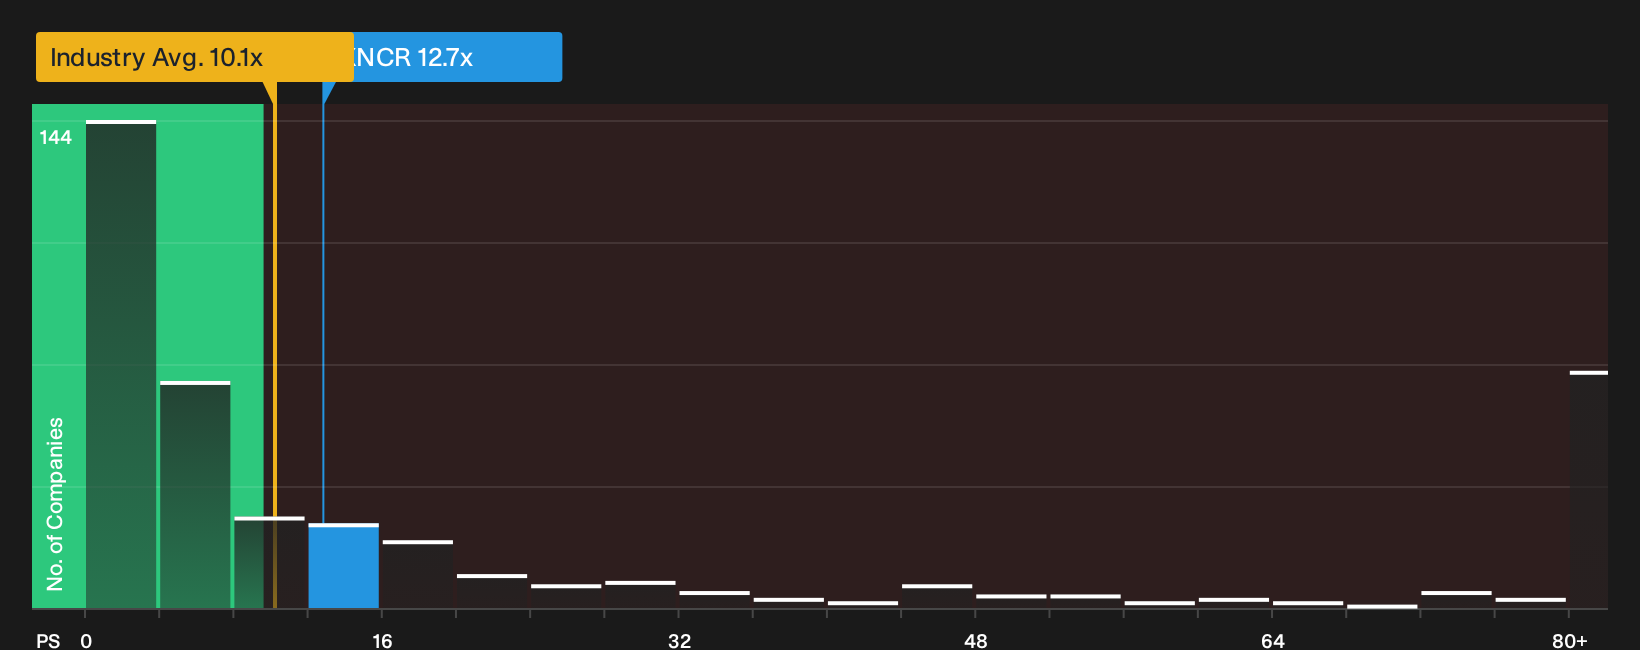
The P/S ratio fits Xencor because investors are currently paying far more attention to its revenue line than to free cash flow or earnings. On this lens, the stock trades on a P/S of 12.7x, which is above the broader biotech industry average of 10.1x and sits below the 19.7x level seen across closest peers. That mix suggests the market already ascribes a premium to Xencor relative to the sector as a whole, while still pricing it less aggressively than some comparable developers.
The Fair Ratio model, which adjusts the P/S benchmark for Xencor's margins, growth profile, scale and risk, flags the current multiple as overvalued on this framework and indicates a wide gap. Fresh Q3 numbers showed a profit of US$39.4 million on US$116.5 million of sales and beat analyst expectations. However, the present P/S still embeds a richer valuation than this tailored yardstick suggests, because the model heavily penalises the ongoing losses expected in future cash flow projections rather than treating the recent quarter as a full reset. Explore the numbers behind Xencor's P/S valuation.
The Xencor Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where the Xencor valuation puzzle leaves off by spelling out which future paths for growth, margins and earnings would need to play out for today’s share price to look materially cheap or expensive. Each scenario on the Community page is framed as a thesis about how Xencor's business could develop over time, so you can watch whether the underlying assumptions hold up as fresh information arrives.
One of the top community narratives on Xencor: 11% undervalued
"Xencor's lead program XmAb942 is positioned to address significant unmet need in inflammatory bowel disease by offering longer dosing intervals..."
Discover why this Narrative puts Xencor at 11% undervalued.
The open question for Xencor, what are analysts really building into their models?
Sales multiples and recent results only tell part of the story, because professional forecasts a few years out offer a separate lens on where this business might be heading. Explore where analysts expect Xencor to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com