


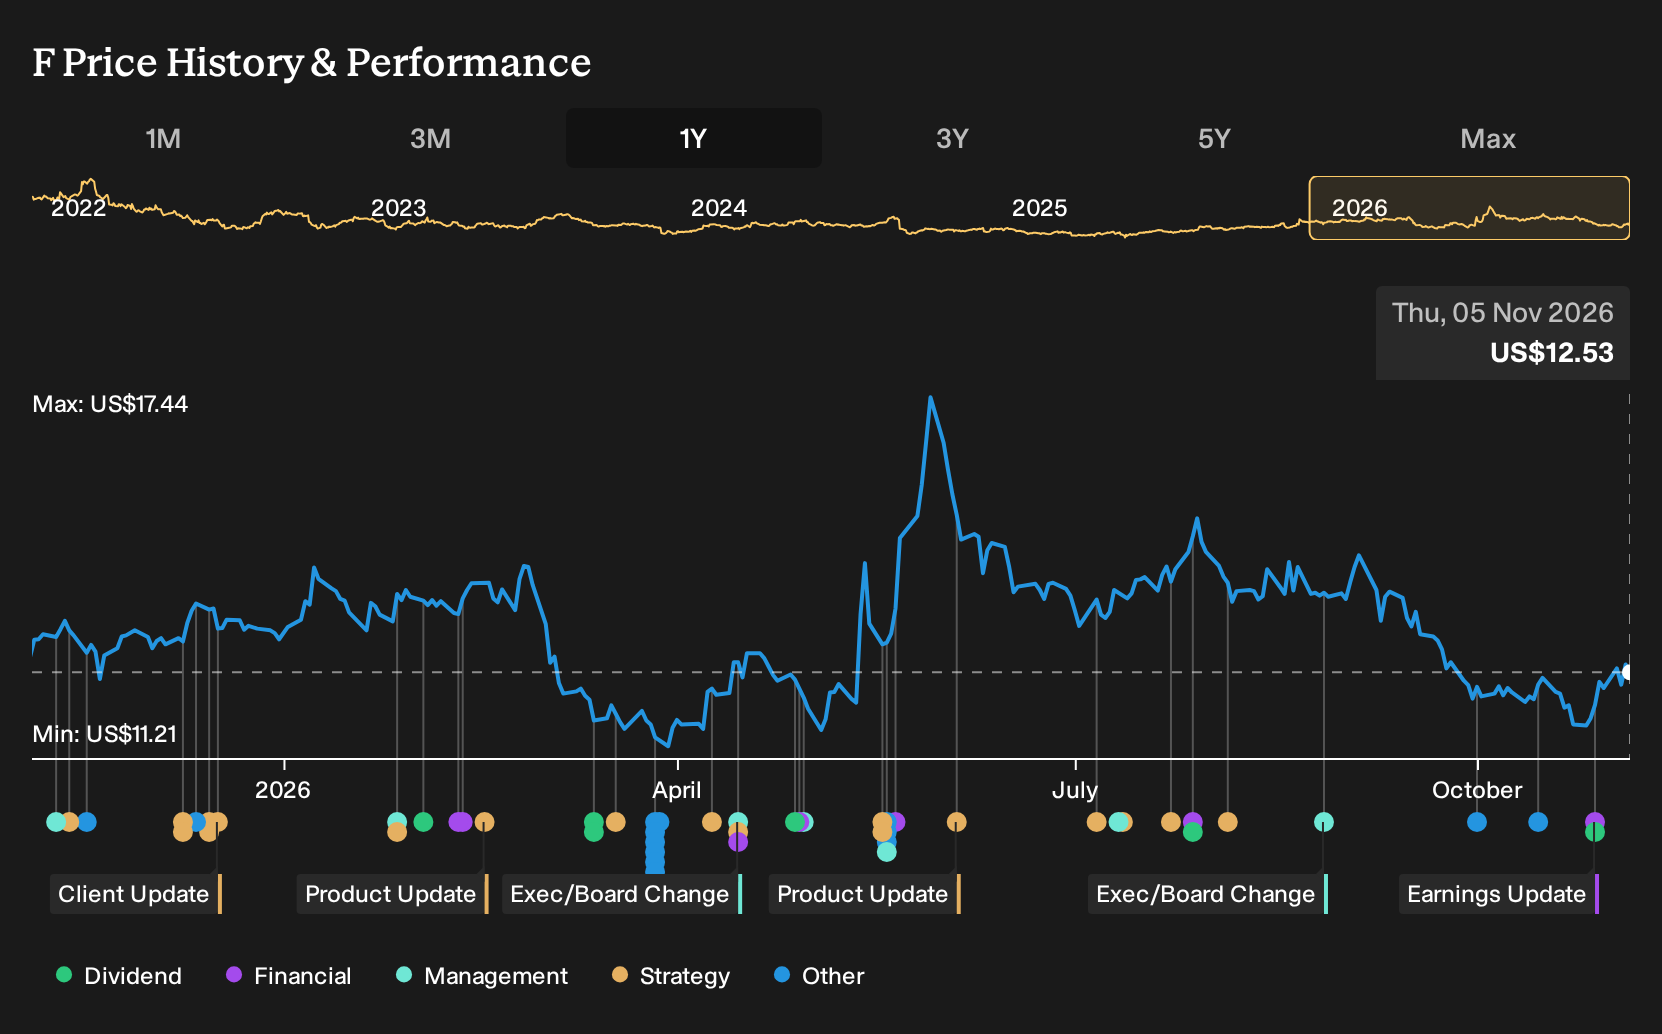
- Ford Motor reported third quarter 2026 revenue of US$49,526 million and net income of US$2,049 million, while also affirming a US$0.15 per share fourth quarter dividend and outlining materially higher expected commodity costs for 2026 and 2027.
- The update that commodity costs are now expected to total nearly US$2.5 billion in 2026, with a further US$2 billion step up in 2027, highlights how input inflation is already weighing on Ford Pro and Ford Blue operating profit and keeps execution on cost offsets firmly in focus.
- We will now explore how Ford Motor's investment narrative, built around margin targets and cost discipline, could be tested by this commodity cost reset.
Ford Motor Investment Narrative Recap
To own Ford Motor today, you need to believe the business can turn its huge truck and commercial base into steadier, higher quality earnings while keeping capital intensive bets like EVs under control. The latest quarter points to that balance becoming harder. Revenue in Q3 slipped to US$49,526 million and net income fell to US$2,049 million, while commodity costs are now expected to move materially higher in 2026 and 2027.
In the short term, the key positive catalyst is execution on cost discipline and mix, especially through Ford Pro, software subscriptions and higher value trims. The biggest near term risk sits squarely in affordability pressure and rising input costs. Higher commodity expense is already pressuring Ford Pro and Ford Blue margins, and it narrows the room for error if EV demand stays weak and pricing power fades.
The dividend affirmation to US$0.15 per share for the fourth quarter is the most directly relevant update for you as a shareholder. Management is choosing to keep cash returns steady after a quarter where earnings were lower than a year ago and commodity cost expectations rose by about US$500 million for 2026, with a further step up signalled for 2027.
That decision keeps income investors engaged but also sharpens focus on cash generation and balance sheet risk, given earlier flags that debt is not well covered by operating cash flow and that the dividend is not well covered by earnings. For Ford Motor, holding the payout while input costs rise raises the bar on execution in quality, software driven revenue and Pro profitability. Those areas need to fund both investment and distributions without stretching the balance sheet.
Ford Motor's narrative projects US$197.0b revenue and US$15.2b earnings by 2029. That framework assumes 1.8% yearly revenue growth and an earnings swing of about US$23.0b from earnings today of a US$7.8b loss.
Uncover why Ford Motor's fair value indicates a 22% potential upside to its current price, which could narrow quickly as sentiment around Ford Motor shifts.
Exploring Other Perspectives
Some of the most optimistic analysts focus less on Ford Motor’s trucks and more on software and energy as potential profit engines. Before this earnings update, that group was pencilling in about US$201.5b of 2029 revenue and US$16.6b of earnings. You can treat this as one possible path that may shift as higher commodity costs filter through.
Explore 6 other Ford Motor fair value estimates, including one that suggests as much as 86% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ford Motor research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ford Motor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ford Motor's overall financial health at a glance.
Looking For More Ideas Beyond Ford Motor?
If this Ford Motor update has sharpened your thinking but you also want a broader watchlist, the Simply Wall St Screener can help you quickly surface other stocks that match your risk and income preferences.
- If you care most about resilient balance sheets and solid fundamentals, start with a curated list of solid balance sheet and fundamentals (24 results) that keeps financial strength front and center.
- Income focused investors can prioritize stability and yield by scanning a hand picked 6 dividend fortresses that aims to pair high payouts with staying power.
- For those hunting for quality at a reasonable price, widen the lens beyond Ford Motor with a 42 high quality undervalued stocks that filters for strong businesses trading below their estimated worth.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com