


- nLIGHT reported third quarter 2026 revenue of US$73.76 million versus US$66.74 million a year earlier, with a quarterly net loss of US$7.18 million and basic and diluted loss per share of US$0.12 from continuing operations.
- Across the first nine months of 2026, nLIGHT recorded US$236.54 million in revenue and a reduced net loss of US$7.87 million, which tightens loss per share from continuing operations to US$0.14.
- We will look at how nLIGHT's investment narrative is influenced by rising year to date revenue alongside a smaller cumulative net loss.
Scan other laser and advanced manufacturing plays with tightening losses and growing top lines by checking out the 53 AI infrastructure stocks alongside nLIGHT's latest results.
nLIGHT Investment Narrative Recap
To own nLIGHT, you need to believe the shift toward directed energy and sensing can outweigh the drag from legacy cutting and welding and ongoing losses. The latest quarter shows higher revenue with a continued quarterly loss of US$7.18 million, so the near term story still hinges on scaling higher margin defense work without letting costs creep.
The key short term catalyst remains execution on large laser weapon and sensing programs as the Longmont facility ramps. The biggest risk is still concentration around complex supply chains and Chinese scrutiny of dual use components, which has already pushed revenue out of Q3 2026. This earnings print does not meaningfully change that balance.
The most relevant piece of context for this quarter is the earlier decision to raise more than US$190 million of equity and build the 50,000 square foot Longmont, Colorado site for high energy laser production. That capital raise left nLIGHT with roughly US$330 million in cash earmarked partly to support higher volume directed energy output.
Against the latest results, that investment looks central to whether growing defense and sensing awards can move the firm toward better gross margin and more predictable earnings. If Longmont hits planned scale while supply chain constraints around China stay contained, the operational story strengthens. If delays stack up or disruptions broaden, those same fixed costs can amplify the risk around ongoing losses.
nLIGHT's current earnings sit at a loss of US$12.5 million, while analysts model earnings of US$11.4 million by 2029 on forecast revenue of US$456.1 million. That view builds in 13.7% yearly revenue growth and an earnings swing of about US$23.9 million from earnings today.
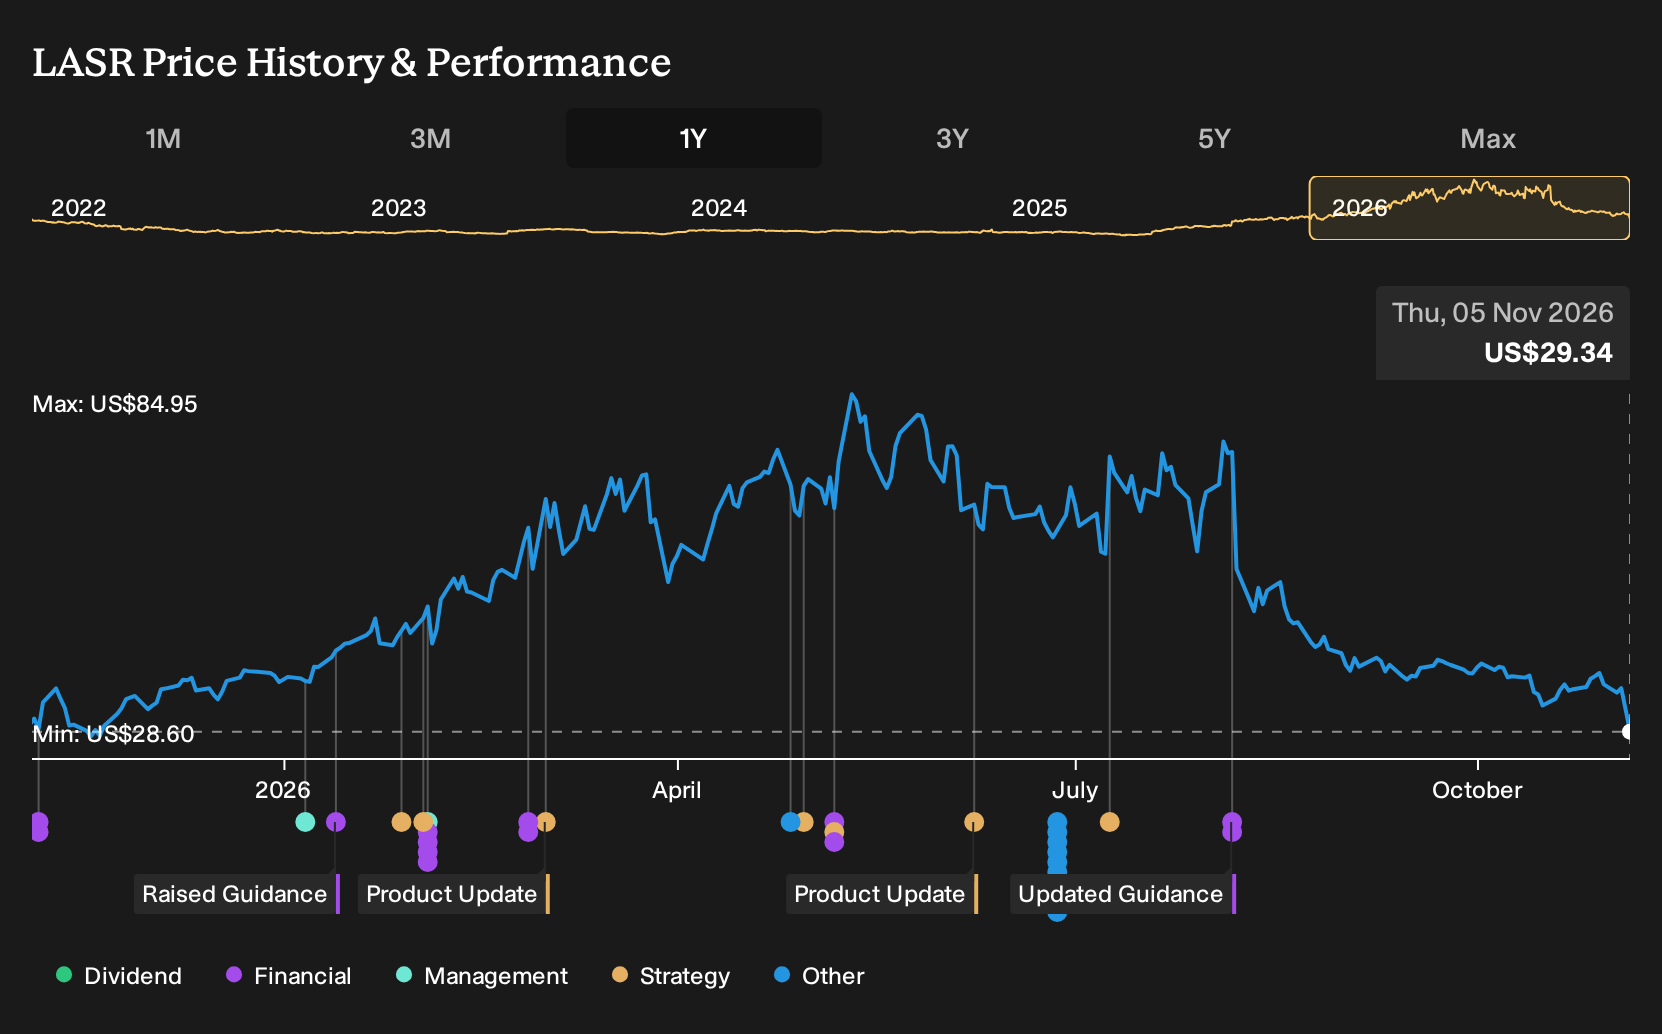
Discover how nLIGHT's fair value indicates a 180% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Supply chain friction is where the lowest analysts lean in hardest on nLIGHT. They were only looking for roughly US$419.6 million in 2029 revenue and about US$4.3 million in earnings, which paints a far slower payoff from Longmont. Treat this Q3 update as a fresh data point that could shift those views in either direction.
Explore 4 other nLIGHT fair value estimates, including one that suggests as much as 40% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your nLIGHT research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for nLIGHT. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake. This makes it easy to evaluate nLIGHT's overall financial health at a glance.
Looking For More Ideas Beyond nLIGHT?
If nLIGHT has sharpened your interest in this corner of the market, broaden your watchlist by scanning other stocks through the Simply Wall St Screener before you make your next move.
- For investors hunting for resilient balance sheets and healthier fundamentals, start with a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions.
- If capital protection sits high on your priority list, narrow your focus to companies in the 32 resilient stocks with low risk scores that score well on stability and downside control.
- When you want to uncover potential future leaders before they gain wider attention, sort through the 21 high quality undiscovered gems and see which profiles fit your own criteria.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com