


Cipher Digital has seen its share price swing sharply in recent years, and those moves put a spotlight on a simple question for investors who care about fundamentals. Is the current US$5.55 price tag supported by the sales the business is generating today and what those revenues may grow into over time.
- The share price has gained 86.2% over the past 3 years, which puts real weight on whether that move lines up with the scale and quality of Cipher Digital's sales base.
- Recent expansion plans in bitcoin mining and high performance computing data centers, including a new 70MW Texas site, can reshape expectations for future revenue and the timing of cash needs tied to that growth.
- The analysts covering Cipher Digital have run their own numbers. See what analysts think Cipher Digital's shares could be worth.
The issue now is whether Cipher Digital's current share price is justified by its sales when set against the Fair Ratio benchmark.
If you want to test the same sales based valuation question across a broader set of bitcoin and crypto related plays rather than just Cipher Digital, take a look at 18 cryptocurrency and blockchain stocks.
Does Cipher Digital Look Pricey on Sales?
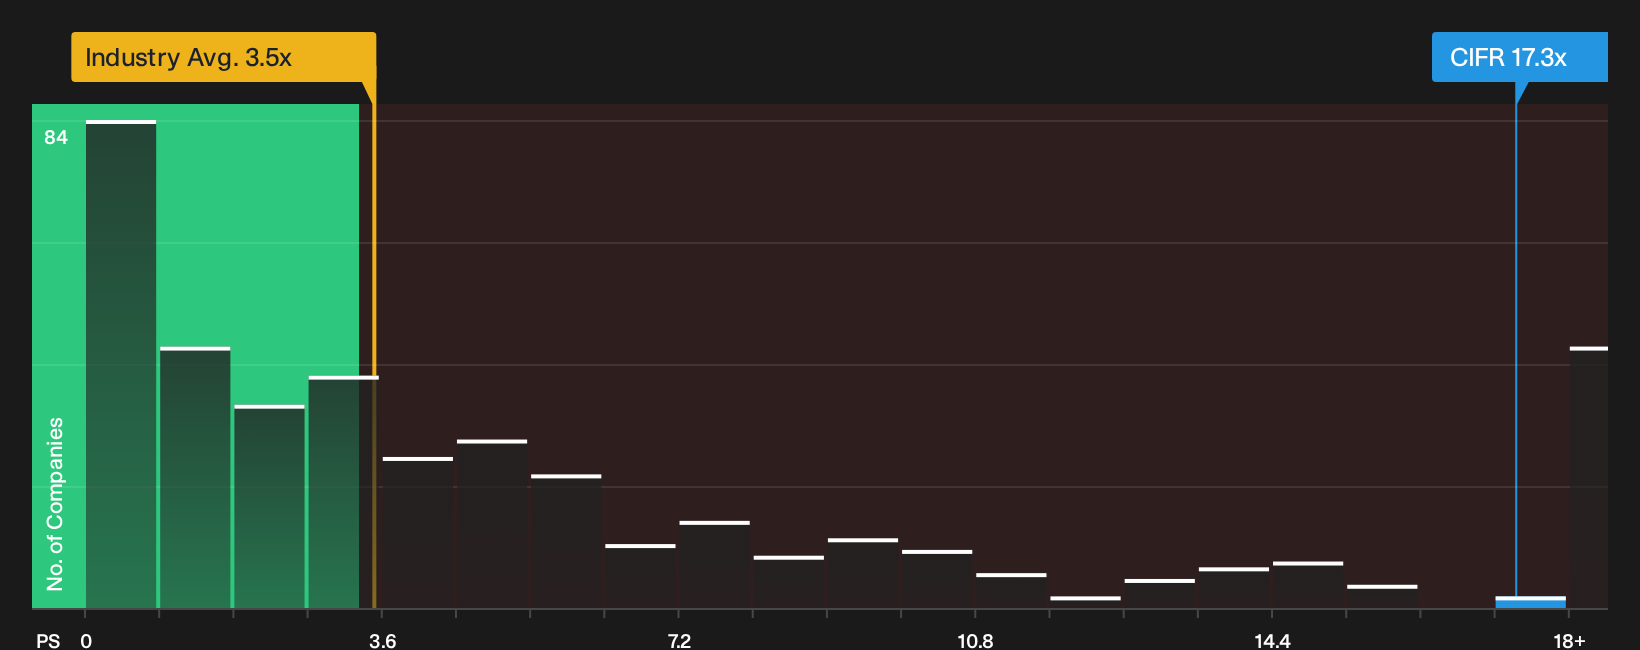
P/S is a useful lens for Cipher Digital because the business is still focused on scaling revenue rather than generating consistent profits. On this measure, the stock trades on a P/S of 17.3x, which is well above the broader software industry average of 3.5x and also ahead of the peer group around 5.7x. Despite KBW reiterating an Outperform rating and pointing to expansion in bitcoin mining and high performance computing facilities, the current pricing already builds in a rich value for each dollar of current sales.
The Fair Ratio framework, which adjusts for Cipher Digital's growth profile, margins, size and risk, flags the P/S as meaningfully higher than the level implied by those fundamentals. The model is heavily penalising ongoing losses and the quality of revenues, so the gap looks more like a warning signal that the shares screen overvalued on sales than a precise estimate of where the multiple should land. That difference can matter a lot for anyone assuming the recent development pipeline will fully support today’s revenue multiple without hiccups. Explore the numbers behind Cipher Digital's P/S valuation.
The Cipher Digital Narrative: What Would Justify Today's Price?
Narratives pick up where Cipher Digital's valuation puzzle leaves off. They explain what kind of future for growth, margins and earnings would need to occur for the stock to appear meaningfully cheap or expensive relative to today's price. Each narrative ties a specific fair value to a clear set of potential catalysts and risks, so you can see over time which version of the story is actually unfolding on Simply Wall St's Community page.
One of the top community narratives on Cipher Digital: 81% undervalued
Analysts expect Cipher Digital to keep converting its gigawatt scale power pipeline and existing hyperscale relationships into long term AI and high performance computing leases.
Discover why this Narrative puts Cipher Digital at 81% undervalued.
The Cipher Digital share price is only one side of your decision
Before you anchor too firmly on Cipher Digital's valuation story, it is worth knowing that Simply Wall St's checks have flagged specific areas of concern that can change how you weigh the opportunity. Take a closer look at 3 warning signs (2 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com