


Kimbell Royalty Partners has delivered strong gains for long term holders, yet the recent pullback puts fresh focus on a simple question: Is the current US$15.03 share price still supported by the earnings that the partnership generates from its royalty interests?
- Over the past 5 years, Kimbell Royalty Partners has returned 83.4%, which puts real weight on whether its earnings profile can carry that performance further.
- The partnership collects revenue from a broad base of oil and gas wells, so the durability of those cash flows and how efficiently they convert into earnings may be critical for how you judge today’s pricing.
- Your read on Kimbell Royalty Partners is one view; the desks covering it have another. See what analysts think Kimbell Royalty Partners's shares could be worth.
The issue now is whether Kimbell Royalty Partners' current market price is justified by the earnings that underpin it.
If you are weighing whether Kimbell Royalty Partners' US$15.03 price fairly reflects its earnings profile, it can help to compare that question with other income focused ideas screened for 6 dividend fortresses.
Has Kimbell Royalty Partners Run Too Far on Earnings?
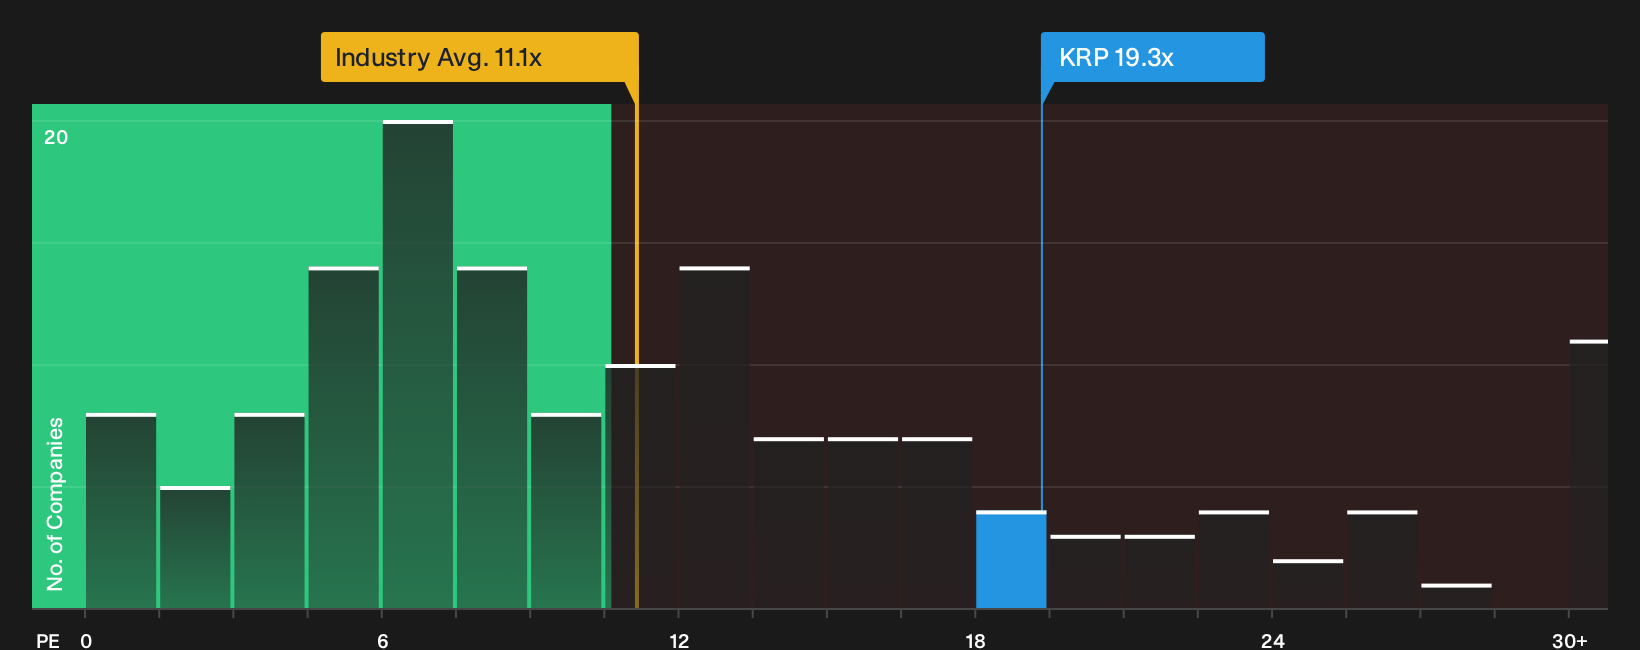
The P/E ratio fits Kimbell Royalty Partners well because earnings from its royalty interests are a key reference point for owners. On this measure, the stock trades on roughly 19.3x earnings, compared with about 11.1x for the broader Oil and Gas sector and 11.4x across direct peers. That premium indicates the market is placing a higher value on each dollar of Kimbell Royalty Partners' profit than on most similar businesses.
A fair value framework that adjusts for the partnership's size, risk profile and earnings quality indicates a lower P/E would be more typical for Kimbell Royalty Partners, so the current 19.3x screens as overvalued on this basis. For anyone assessing the US$15.03 price, the key question is whether the quality and resilience of the royalty income stream justify paying a richer multiple than both the sector and this tailored benchmark. Explore the numbers behind Kimbell Royalty Partners's P/E valuation.
The Kimbell Royalty Partners Narrative: What Would Justify Today's Price?
Narratives for Kimbell Royalty Partners pick up where the valuation puzzle leaves off by spelling out which paths for earnings, margins and reinvestment would need to play out for the units to be worth materially more or less than today’s price, and they sit on Simply Wall St's Community page. Rather than relying on a single multiple or model output, each narrative lays out the assumptions behind its view of fair value so you can compare them with future results as they are reported.
One of the top community narratives on Kimbell Royalty Partners: 22% undervalued
"The main thing that has to go right is that Kimbell Royalty Partners continues to source accretive deals and manage leverage around its stated target…"
Discover why this Narrative puts Kimbell Royalty Partners at 22% undervalued.
Before acting on Kimbell Royalty Partners' valuation, there is one more factor to check
Price and earnings only tell part of the story for Kimbell Royalty Partners, because the research has also surfaced potential weak spots that could change how you view the whole picture. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com