


Pursuit Attractions and Hospitality has delivered a powerful share price run in recent years, which naturally puts its earnings under the microscope. With the stock now around US$54, the key issue for investors is whether that climb lines up with the profit engine behind the business.
- The share price is up about 80.9% over 3 years, which puts real weight on the question of how much earnings can carry from here.
- Recent record revenue and higher adjusted EBITDA suggest the attractions and tours portfolio may support different assumptions about future profitability and cash generation than in the past.
- There is a second opinion on Pursuit Attractions and Hospitality worth weighing. See what analysts think Pursuit Attractions and Hospitality's shares could be worth.
The issue now is whether Pursuit Attractions and Hospitality's current price is adequately supported by its earnings when set against a Fair Ratio benchmark.
If you want to test the same earnings question that hangs over Pursuit Attractions and Hospitality against a wider field, run those filters across 42 high quality undervalued stocks.
Has Pursuit Attractions and Hospitality Run Too Far on Earnings?
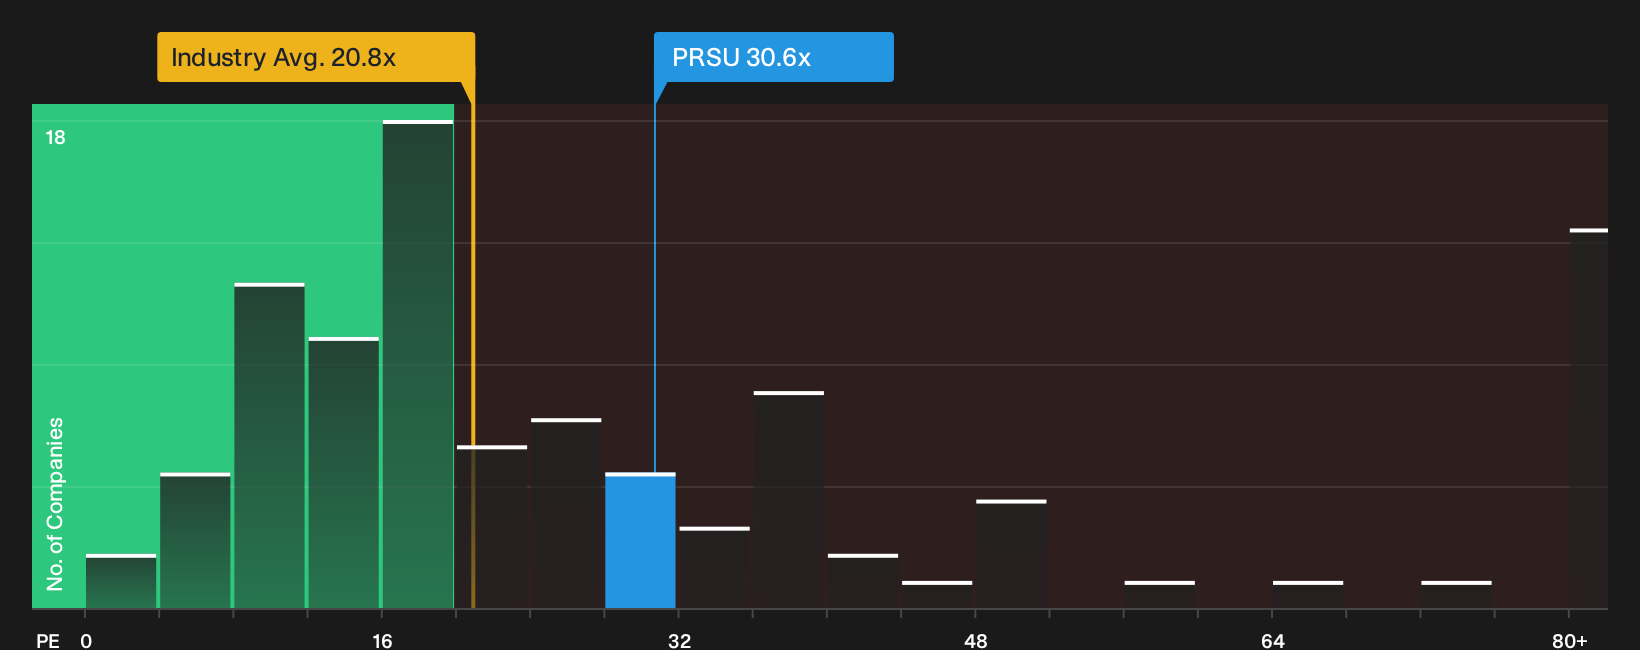
The P/E ratio suits Pursuit Attractions and Hospitality because earnings now sit at the center of how the market is framing the story. The stock trades on a P/E of about 30.6x, compared with roughly 20.8x for the wider Hospitality industry and around 23.9x for peers. That puts a clear premium on each dollar of profit the business generates.
The Fair Ratio model, which blends the company’s growth profile, profitability, size and risk into a tailored yardstick, points to a lower earnings multiple than the current share price implies. Despite the Q3 2026 update highlighting record revenue and firmer adjusted EBITDA guidance, the present 30.6x P/E screens as overvalued against this benchmark. Investors need to decide whether Pursuit Attractions and Hospitality’s earnings quality and long term potential truly justify paying that kind of mark up. Explore the numbers behind Pursuit Attractions and Hospitality's P/E valuation.
The Pursuit Attractions and Hospitality Narrative: What Would Justify Today's Price?
Narratives for Pursuit Attractions and Hospitality pick up exactly where the P/E puzzle leaves off, by spelling out which paths for growth, margins and earnings would need to play out for the current price to look cheap or expensive on Simply Wall St's Community page. Instead of a single output from a ratio or model, they set out the future those numbers assume, so you can watch how the real business lines up with that script over time.
One of the top community narratives on Pursuit Attractions and Hospitality: 13% undervalued
"Disciplined acquisitions of high-margin, scarce assets such as Tabacón and Eagle Wing Tours, typically at 6x to 9x EBITDA with targeted returns above 15%..."
Discover why this Narrative puts Pursuit Attractions and Hospitality at 13% undervalued.
The share price is only one piece of the Pursuit Attractions and Hospitality puzzle
Market multiples tell you what investors pay today, while professional forecasts sketch out where they think Pursuit Attractions and Hospitality might realistically be a few years from now. Explore where analysts expect Pursuit Attractions and Hospitality to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com