


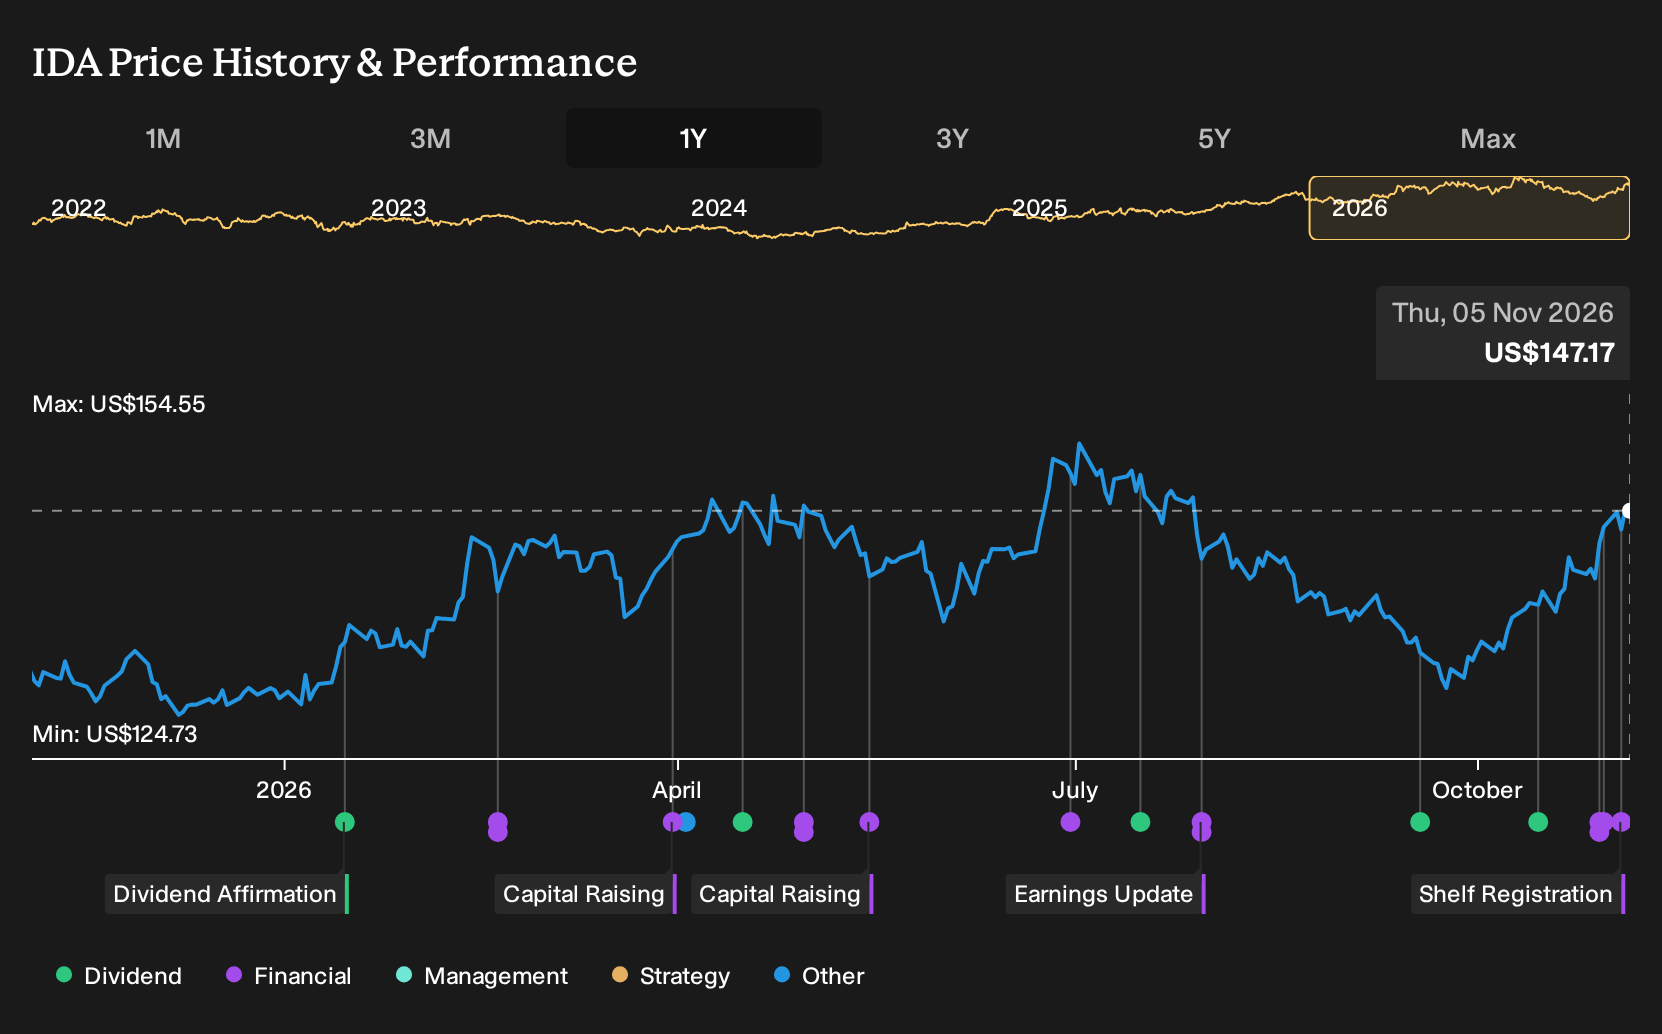
- IDACORP reported third quarter 2026 revenue of US$608.04 million and net income of US$160.21 million, with earnings per diluted share from continuing operations of US$2.73. The company lifted full year 2026 earnings guidance to a range of US$6.40 to US$6.50 per diluted share.
- The parallel shelf registrations for up to 600,000 common shares, including through a dividend reinvestment plan, indicate that IDACORP is preparing additional equity capacity that can support its ongoing capital needs while aligning with its regulated utility model.
- Investors will now be able to assess how IDACORP's higher full year earnings guidance could reshape the investment narrative they had been using.
IDACORP Investment Narrative Recap
To own IDACORP, you need to be comfortable with a regulated utility that is leaning into heavy capital spending while managing weather exposure and a growing large load pipeline. The raised 2026 earnings guidance depends on normal conditions and continued cost recovery, so the key near term catalyst is clean execution against that outlook.
The biggest current risk sits in the mix of hydropower sensitivity and funding needs for US$1.3b to US$1.5b of annual CapEx through 2030. Recent quarterly numbers and guidance do not remove that risk. They suggest that management currently sees enough operational support to reaffirm the investment and load plan.
The parallel shelf registrations for a combined 600,000 IDACORP common shares, including 300,000 tied to a dividend reinvestment plan, connect directly to that CapEx and rate base build narrative. Fresh equity capacity gives the business another funding lever as it pursues roughly US$7b of projects through 2030 while trying to hold a balanced capital structure.
For you as a shareholder, the practical question is how this incremental issuance potential interacts with the higher 2026 earnings guidance and existing risks around interest coverage and hydropower volumes. The filings do not change the core thesis, but they frame dilution, funding costs and regulatory recovery as live execution points to track.
IDACORP's current earnings of $338.6 million sit against analyst forecasts for revenue of $2.5 billion and earnings of $525.8 million by 2029. This forecast assumes 11.5% yearly revenue growth and an earnings increase of about $187 million from today.
Uncover why IDACORP's fair value indicates a 3% potential upside to its current price before the market prices away the discount.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about US$112 and US$151 per share, so some contributors see IDACORP as materially mispriced in both directions. Those retail viewpoints predate the raised earnings outlook and fresh shelf registrations, so you may want to contrast them with updated hydropower, CapEx and regulatory risk assessments.
Explore 2 other IDACORP fair value estimates, including one that suggests as much as 24% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your IDACORP research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for IDACORP. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate IDACORP's overall financial health at a glance.
Looking for more investment ideas beyond IDACORP?
Once you have formed a view on IDACORP, it can help to set it beside a few other possibilities that fit different risk and income profiles. The Simply Wall St Screener lets you do that quickly by lining up stocks against clear, data driven filters.
- If capital preservation comes first for you, scan companies that score well on balance sheet strength with our list of solid balance sheet and fundamentals (24 results).
- If you are hunting for potential mispriced opportunities, line up candidates that pair quality fundamentals with valuation support using the 42 high quality undervalued stocks.
- If reliable income is a priority, filter for payouts above 5% and assess which businesses look more resilient with the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com