


- Entegris announced an expanded partnership with Kioxia that links its materials science, AI driven modeling and digital twin tools to Kioxia’s BiCS FLASH 3D memory development at the Geino Technology Center in Japan.
- The agreement connects Entegris’ materials design and experimental validation directly to Kioxia’s future device requirements, aligning Entegris’ R&D spending more closely with real manufacturing roadmaps in advanced memory.
- We will now assess how Entegris’ investment narrative is affected by this deeper Kioxia collaboration around AI enabled materials design.
Entegris Investment Narrative Recap
For an investor to own Entegris, there needs to be confidence that AI driven demand for advanced logic and memory keeps pulling through more materials content, while management continues to convert that into better margins and cash generation. The expanded Kioxia partnership fits that belief by tying Entegris’ materials work more tightly to real 3D NAND roadmaps, although the impact is likely gradual rather than an immediate swing factor.
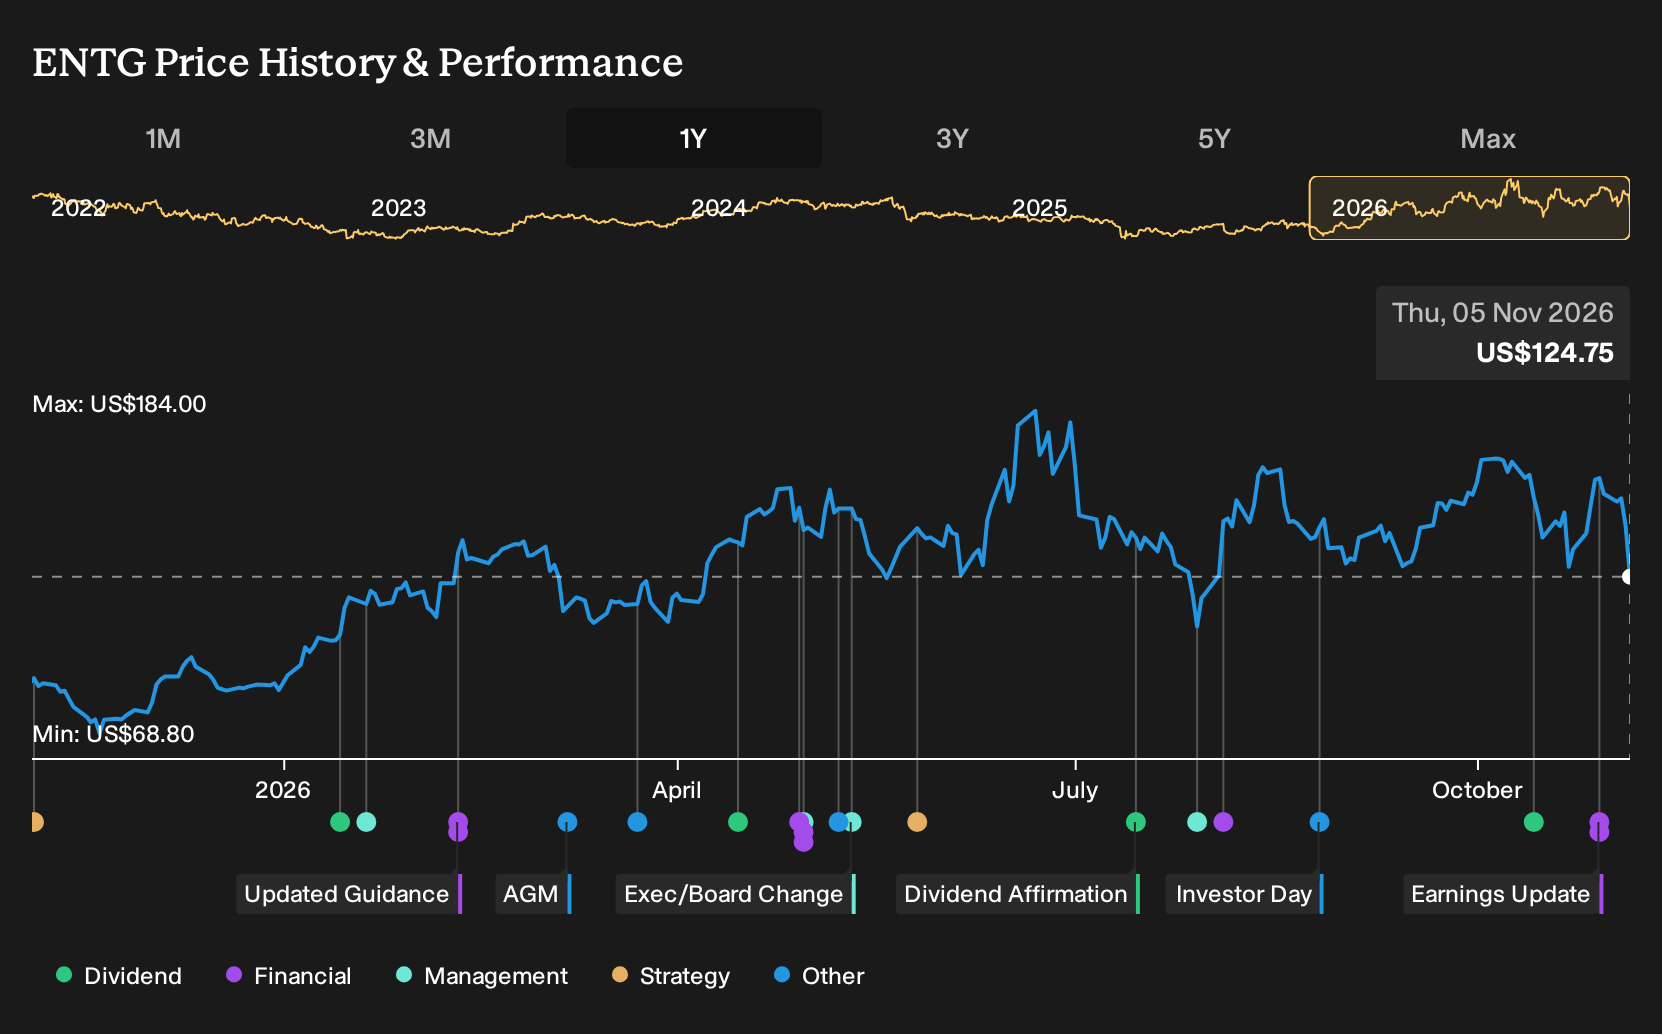
In the short term, the main swing factor remains execution on margin and cash flow goals as new facilities ramp and capex normalizes. The biggest risk is that sentiment cools on a still expensive stock after a strong multi year run, especially if revenue or free cash flow soften or sector wide AI expectations wobble again.
The recent third quarter report is the most relevant backdrop for this Kioxia news. Entegris reported US$1,005.7m of sales, up from US$807.1m a year earlier, with net income of US$157.8m versus US$70.5m. Those numbers show the business entering this deeper collaboration from a position of improving profitability and scale, not from a point of stress.
Guidance for the fourth quarter points to expected sales between US$1,025m and US$1,055m and GAAP net income between US$168m and US$181m. That outlook keeps attention on execution, cost discipline and debt reduction as key catalysts. The Kioxia partnership adds another operational lever around AI centric memory materials, while valuation, leverage and sector volatility remain important watchpoints.
Entegris' narrative projects US$4.9b revenue and US$807.5m earnings by 2029. This implies analysts are assuming 11.4% yearly revenue growth and an earnings increase of about US$414.7m from US$392.8m today.
Uncover why Entegris' fair value indicates a 52% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate take on Entegris leans hard on valuation risk rather than technology upside. The most cautious analysts were working off about US$4.8b of 2029 revenue and US$1.1b of earnings before this Kioxia update, and still landed on lower price targets. That view shows how far opinions can spread, so it can help to explore several competing narratives before deciding how this new partnership might reshape expectations.
Explore 4 other Entegris fair value estimates, including one that suggests as much as 13% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Entegris research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Entegris. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Entegris' overall financial health at a glance.
Looking For More Investment Ideas Beyond Entegris?
If the Entegris story has sharpened your thinking on where AI, materials and cash generation intersect, it can help to widen the lens and compare it with other listed businesses. The Simply Wall St Screener lets you move from one stock to a curated set of candidates that share traits you care about, whether that is quality, balance sheet strength or income potential.
- If you care most about balance sheet strength and resilience, start with a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions without leaning heavily on new funding.
- If value is your main focus, scan a 42 high quality undervalued stocks that combine solid fundamentals with prices that sit below many investors' implied expectations.
- If income matters to you, review a 6 dividend fortresses that aim to pair higher yields with businesses that still show financial discipline.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com