


The Morning Bull - Canadian Market Morning Update Friday, 6 Nov 2026
Canadian equities are set for a soft open, with S&P/TSX 60 futures slightly in the red as attention converges on today’s US jobs report. The tone is cautious rather than gloomy, with sentiment hinging on labour data.
The consensus looks for US non farm payrolls of 65,000 for October, up from 29,000 previously, while average hourly earnings are forecast at 0.3% month on month. These expectations shape views on whether US rate policy remains steady or leans tighter.
If payrolls and wage growth come in firmer than projected, investors tend to price in a higher path for borrowing costs. That can pressure rate sensitive areas of the Canadian market by lifting bond yields and compressing valuation multiples, especially for companies reliant on cheaper credit.
The real question for Canadian investors is simple: does the labour data validate current rate expectations, or force another reset in bond markets that drags local equities with it ahead of this afternoon’s domestic employment figures?
Stocks to Watch Before the Opening Bell
Enbridge (ENB)
Fresh Q3 2026 numbers from Enbridge put over $3b of gas transmission projects into service and keep 2026 guidance intact. The pipeline giant is adding crude and gas assets, including Tallgrass Energy and Salt Creek Midstream units, for nearly $3.5b. Investors can track the roughly $38b secured backlog and how new equity and partner capital shape funding needs.
TELUS (T)
TELUS is implementing a transformation plan that targets about $900m in annualized cash savings by the end of 2028. Management is trimming costs, investing in AI infrastructure and selling pieces of TELUS Health and TELUS Agriculture & Consumer Goods to reduce debt. A key watchpoint is execution on disposals while maintaining telecom growth and keeping 2026 guidance on track.
Gildan Activewear (GIL)
Gildan Activewear posted Q3 2026 results with net sales from continuing operations up 61.1%, supported by the HanesBrands deal, but demand came in softer than expected across Wholesale and Retail. The group sold its HanesBrands Australia unit and approved a buyback of up to 5% of its shares. Investors are likely to focus on the lower 2026 guidance and the withdrawn revenue forecast.
Top Movers
- Topicus.com (TSXV:TOI) jumped 7.39% after Q3 results showed higher revenue, positive net income, and improving earnings per share.
- Torex Resources (TSX:TXR) gained 6.81% as Q3 numbers highlighted higher net income and record free cash flow from operations.
- OceanaGold (TSX:OGC) advanced 6.46% following Q3 figures featuring higher sales, stronger earnings, and an announced Ausgold acquisition.

Top Losers
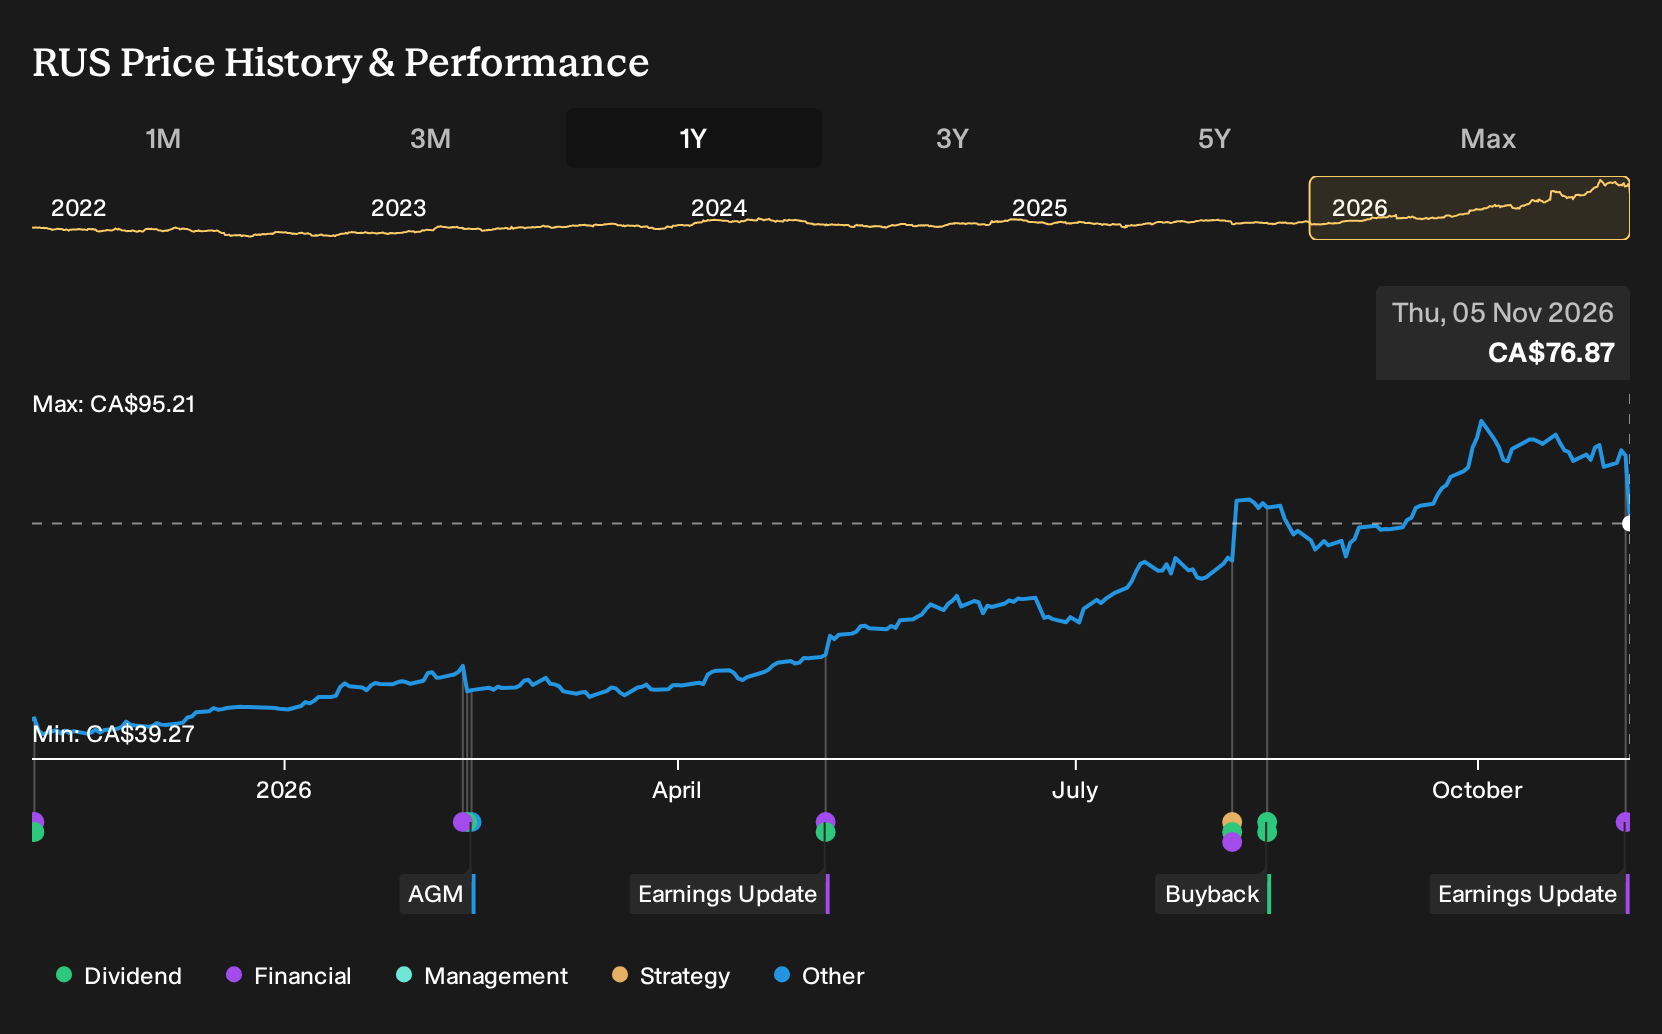
- Russel Metals (TSX:RUS) declined 13.62% after record Q3 results, dividend declaration and completion of the Color Steels sale.
- Celestica (TSX:CLS) fell 12.66% as the AI hardware selloff deepened and investors reassessed data center demand expectations.
- Lundin Mining (TSX:LUN) dropped 11.43% following Q3 results and lowered 2026 copper production guidance after weather related disruptions.
On The Radar
Canadian labour data and a heavy run of domestic earnings over the next few days line up directly against today’s US payrolls. This creates a tight feedback loop between the S&P/TSX, the Canadian dollar and rate expectations.
- Canada Unemployment Rate, Fri 6 Nov. The October jobless rate is projected to hold at 6.5%. A higher print would point to softer labour conditions and could ease pressure on borrowing costs. A lower figure risks firmer rate expectations and a stronger Canadian dollar.
- Canada Employment Change, Fri 6 Nov. Forecasters look for a 13.6k gain after a prior decline of 68.3k. Another weak hiring number would underline cooler demand for workers and may support interest rate sensitive parts of the Canadian market.
- United States Non Farm Payrolls, Fri 6 Nov. Consensus sits at 65k jobs after 29k previously. A result far above that band would reinforce a firmer US dollar and a higher global yield backdrop that often weighs on Canadian rate sensitive stocks.
- Brookfield Asset Management, Fri 6 Nov. Q3 2026 results at 7:00 AM Eastern put the focus on fee related earnings and capital deployment. These factors feed directly into how investors view cash generation and dividend capacity across Brookfield’s asset management platform.
- Canadian Tire Corporation, Thu 12 Nov. Q3 2026 numbers before the open will highlight how retail revenue and merchandise margins are tracking against cost pressures. The results will serve as an important reference point for broader Canadian consumer and discretionary spending trends.
Sector & Industry Watch
Tech: Selling pressure widens beyond chips
Tech stocks in Canada have slipped again over the past week, with the sector down about 6% while already weaker year to date. Semiconductors show an even steeper slide over 7 days and carry a very large 12 month decline, even as firms like Kraken Robotics report fresh order wins and Hydaway Digital cleans up its structure with a share consolidation and name change.
If you own Canadian software, hardware or chip exposure, the main trigger to watch now is today’s US non farm payrolls release, since any change in interest rate expectations can influence how investors price future oriented earnings for high growth tech after such a sharp reset.
Energy and Oil and Gas: Q3 strength meets short term slump
Energy and Oil and Gas have dropped sharply over the past 7 days, each down close to 9% despite solid 12 month gains and positive year to date returns. Q3 updates from Canadian Natural Resources, Enbridge, TC Energy, Pembina, InPlay Oil, Pason, Ensign and others highlight project backlogs, dividends and buybacks while share prices ease.
If your portfolio includes producers or pipelines, the single biggest swing factor now is Canada’s October employment report this afternoon, because any surprise on jobs can feed into fuel demand expectations and how investors view funding costs for multi year projects and payout plans across the sector.
Telecom: Rebound builds as spending ramps up
Telecom has pushed higher again over the past week and month, even though the 12 month return remains slightly weak. BCE’s heavy Q3 capital spending, TELUS’ cost saving program and asset sales, and Quebecor’s wireless subscriber gains show carriers spending heavily on fibre and data infrastructure while fighting for mobile share.
If you hold BCE, TELUS, Rogers or Quebecor, pay closest attention to upcoming Canadian inflation data, since price trends influence how regulators view phone and internet bills and how much room operators may have to pass big network budgets through to customers.
Real Estate: Early REIT recovery still tied to jobs
Real Estate has inched higher over the last 7 days and month, while 12 month and year to date returns stay slightly soft. Updates from Dream Office REIT and Chartwell plus new management wins at FirstService show landlords leaning on occupancy, rent collection and selective asset sales while higher interest expenses still matter.
If you rely on REIT distributions for income, today’s Canadian unemployment, employment change and participation figures are the key checks, since tenant paycheques and household formation feed directly into apartment rent growth and demand for office and seniors housing.
Consumer Staples and Food, Beverage & Tobacco: Everyday spending theme still resilient
Consumer Staples and Food, Beverage & Tobacco have continued to grind higher over the past week and month, with both sectors showing positive 12 month returns. Q3 reports from Loblaw, Premium Brands and Saputo point to steady demand for groceries and packaged food, backed by dividends, buybacks and product launches.
If your holdings lean toward grocery or food producers, the main macro data point to watch is Canada’s labour report this afternoon, because job security and wage income shape basket size, choices between private label and brands and how much pricing power retailers and suppliers can use without losing shoppers.
Build Your Perfect Portfolio
If dividend stability is what you care about while BCE, Enbridge and other payers keep investing heavily, start with this list of 3 dividend fortresses
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com