


Amylyx Pharmaceuticals (AMLX) drew attention after reporting a third quarter net loss of US$45.49 million, along with positive Phase 3 LUCIDITY data for avexitide and fresh capital from an upsized US$545 million equity offering.
The share price reaction has cooled in the very near term, with Amylyx Pharmaceuticals down 6.05% on a 1-day share price return and 3.70% over 7 days. However, the 90-day share price return of 21.03% and year-to-date gain of 141.86%, alongside a 1-year total shareholder return of 121.67% and 3-year total shareholder return of 125.29%, suggest that momentum has been building as investors weigh the LUCIDITY data, equity raise and future regulatory milestones against the enlarged net loss.
Scan Amylyx Pharmaceuticals alongside other late-stage biotech stories and see which ones are gaining momentum in our hand-picked 21 high quality undiscovered gems list.
Amylyx Pharmaceuticals now trades well below both analyst targets and intrinsic value estimates, after a sharp run and fresh capital in the door. Where does a reasonable fair value range actually land on that spread?
Most Popular Narrative: 35% Undervalued
The most followed narrative on Amylyx Pharmaceuticals pegs fair value at $42.36, compared with the recent $27.62 close. This points to a sizeable valuation gap built on the post bariatric hypoglycemia opportunity and a maturing endocrine and neurodegeneration pipeline.
The company is targeting post bariatric hypoglycemia, a condition with no FDA approved therapies and an estimated 160,000 patients in the U.S., which creates room for a first approved product like avexitide to establish a new revenue line if pricing and access are secured.
Amylyx is building a broader GLP 1 antagonist franchise with AMX0318 for PBH and other rare conditions. If successful, this could extend the product life cycle and spread fixed costs over more revenue sources, which may support longer term earnings potential.
See why 2 investors see Amylyx Pharmaceuticals as 35% undervalued.
Analysts behind this narrative apply a discount rate of 7.24% and arrive at a fair value of $42.36 per share, which is about 35% above the last close and roughly in line with the current $42.64 consensus price target. That framework leans on forecasts that Amylyx Pharmaceuticals could reach $343.4m of revenue and $86.8m of earnings by around September 2029, coupled with an assumed future P/E of 70x that is much higher than the 15.8x multiple cited for the broader US pharmaceuticals group.
Those inputs imply a valuation that depends heavily on avexitide moving from successful Phase 3 data to approval and then into meaningful uptake in a market that currently has no approved treatment options. They also assume the wider GLP 1 antagonist franchise and neurology assets eventually help shift Amylyx Pharmaceuticals from a current net loss of $152.1m and no revenue to positive profit margins above 25%, while managing funding needs and potential dilution along the way.
Result: Fair Value of $42.36 (UNDERVALUED)
Still, Amylyx Pharmaceuticals depends heavily on avexitide clearing regulatory hurdles and on future funding needs not forcing equity raises that further dilute existing shareholders.
Find out about the key risks to this Amylyx Pharmaceuticals narrative.
Another View: Amylyx Pharmaceuticals Looks Expensive On P/B
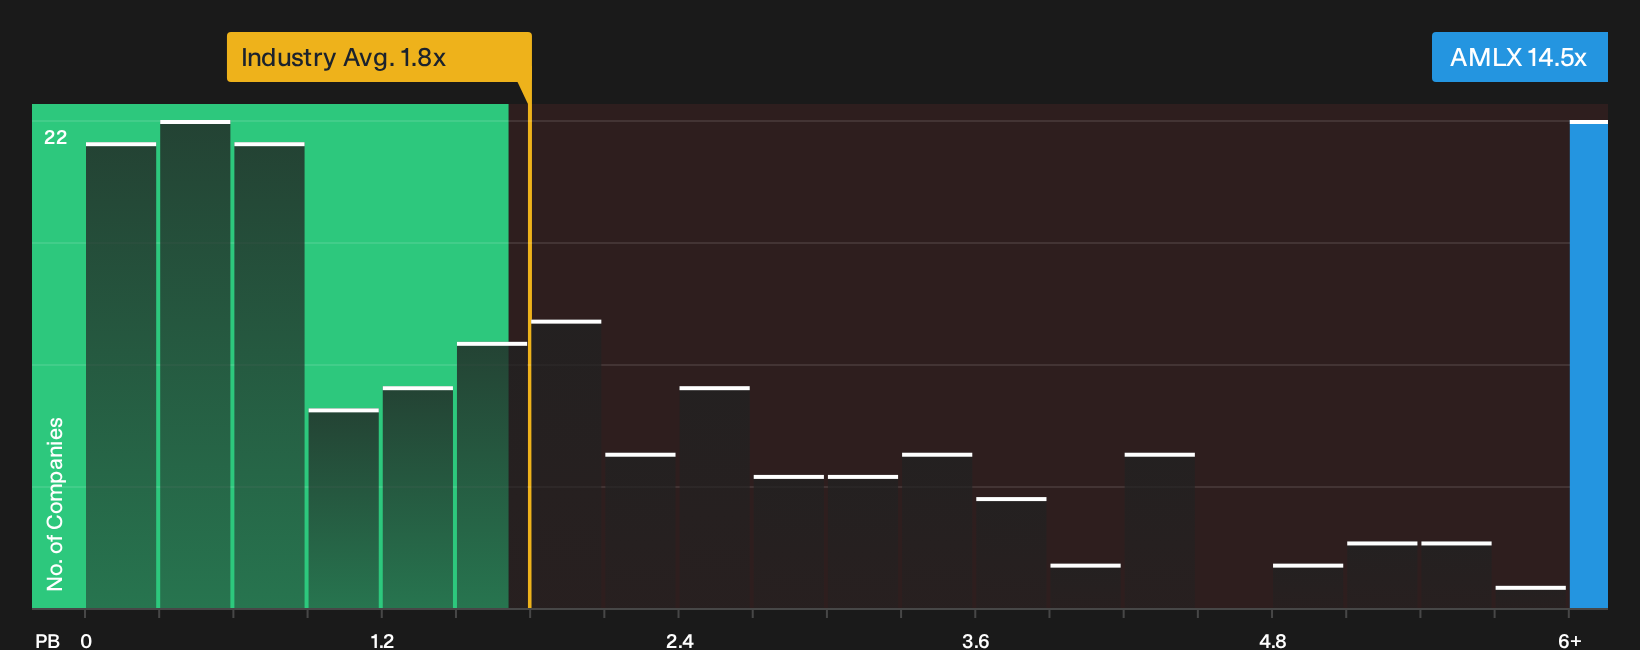
The first narrative leans on long range forecasts and a discounted cash flow framework. On a simpler check, Amylyx Pharmaceuticals trades on a P/B of 14.5x compared with 1.9x for the wider US pharmaceuticals group and 3.4x for peers, which points to rich expectations baked into the current price. How comfortable are you paying that kind of premium for a still loss making biotech?
To unpack what that premium might mean for upside and downside risk, and how it compares with other biopharma stocks using the same yardstick, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Amylyx Pharmaceuticals is mixed, with clear risks on one side and real upside arguments on the other. Consider moving quickly and stress testing the numbers yourself against the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Amylyx Pharmaceuticals?
If you want to pressure test your thinking and avoid anchoring only on Amylyx Pharmaceuticals, take a few minutes to scan other ideas with clear financial filters.
- Target resilient balance sheets and steady fundamentals by reviewing the list of solid balance sheet and fundamentals (24 results) so you are not relying on hope when conditions change.
- Zero in on companies that combine quality with attractive pricing and let the 42 high quality undervalued stocks highlight where the numbers look compelling before the crowd catches on.
- Stack your watchlist with businesses screened for stability and lower risk profiles by using the 32 resilient stocks with low risk scores and avoid missing quieter compounders while headlines chase volatility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com