


CSC Financial (SEHK:6066) is back in focus after reporting nine month 2026 results, with revenue of CNY 23,274.36 million and net income of CNY 10,257.03 million, drawing fresh attention to its fundamentals.
Despite the strong nine month earnings story, CSC Financial’s share price has been under pressure, with the stock down 8.97% over the past month and 21.93% year to date on a share price basis. However, the 5 year total shareholder return of 47.84% signals that longer term holders have still seen meaningful gains.
Compare CSC Financial’s earnings story with other potential opportunities by scanning our hand-picked 229 high quality undervalued stocks that currently combine stronger fundamentals with discounted share prices.
CSC Financial now trades at a clear discount to analyst targets after a weak share price stretch, even as recent earnings remain firm. Is that gap mispricing, or caution that still makes sense?
Preferred P/E of 5.8x: Is it justified?
CSC Financial trades on a P/E of 5.8x at a last close of HK$10.25, which screens as inexpensive compared with both peers and the wider Hong Kong market on earnings based metrics.
The P/E ratio compares the current share price with earnings per share. For a capital markets player like CSC Financial that already reports high quality earnings and a 40.2% net margin, this measure gives a direct read on how much investors are paying for each unit of current profit.
Earnings have grown 2.7% per year over the past 5 years and are forecast to grow a further 4.4% per year. A P/E below the Hong Kong market average of 10.4x suggests the stock is pricing in more muted expectations than the headline profitability might imply. Relative to its own fair P/E estimate of 8.8x, the current multiple looks materially compressed and signals room for the valuation to move closer to that fair ratio level if sentiment or fundamentals line up.
Compared with the Hong Kong Capital Markets industry P/E of 8.5x and a peer average of 7.3x, CSC Financial’s 5.8x multiple is markedly lower. This points to a steeper discount on current earnings than the sector and direct competitors enjoy.
Explore the SWS fair ratio for CSC Financial.
Result: Price-to-earnings of 5.8x (UNDERVALUED).
Still, CSC Financial carries clear risks if sentiment toward Chinese capital markets weakens further or if its investment banking and trading revenues prove more cyclical than expected.
Find out about the key risks to this CSC Financial narrative.
Another view on CSC Financial’s value
The P/E story points to CSC Financial looking inexpensive, yet the SWS DCF model produces a fair value estimate of HK$9.08, which is below the current HK$10.25 share price. That suggests the stock screens as overvalued on a cash flow basis and raises the question of which signal deserves more weight.
Look into how the SWS DCF model arrives at its fair value.
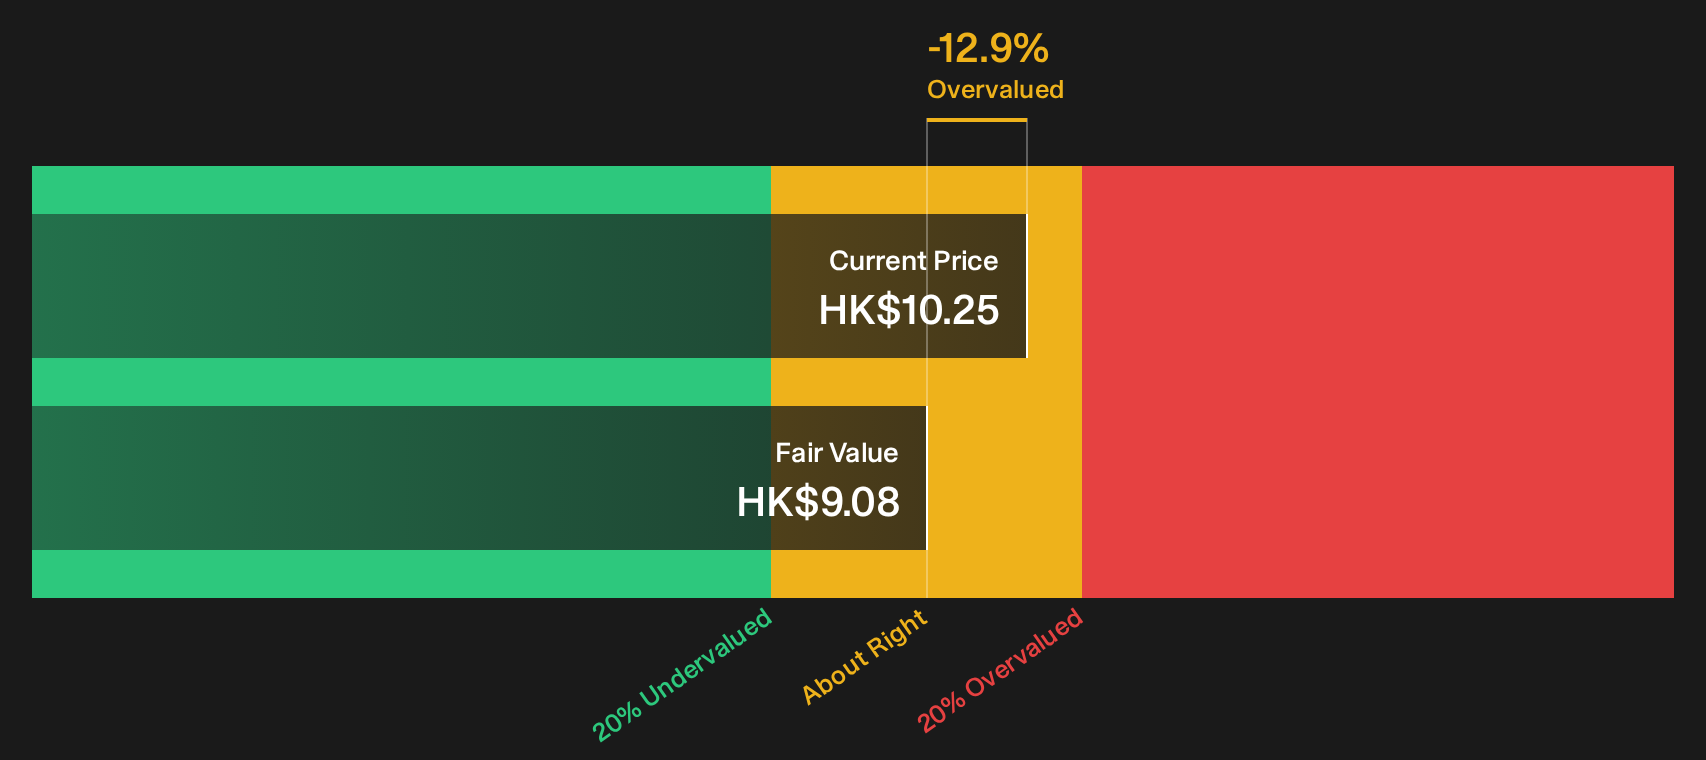
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out CSC Financial for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 229 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty of signals here point in different directions, which is exactly why your own work matters. Move quickly, stress test the data, and weigh both sides by checking the 5 key rewards and 1 important warning sign.
Looking for more CSC Financial style investment ideas?
If you stop with CSC Financial, you risk missing other opportunities that better match your goals, risk comfort, and time horizon across the market.
- Target potential mispricing by reviewing companies that combine strong cash generation with discounted valuations through our 229 high quality undervalued stocks.
- Build more resilience into your holdings by scanning a list of solid balance sheet and fundamentals (192 results) that can better handle shocks and funding pressures.
- Hunt for overlooked opportunities by checking a curated pool of 591 high quality undiscovered gems that pair quality fundamentals with limited current attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com