


WillScot Holdings (WSC) is back in focus after reporting third quarter results on November 5, with higher quarterly revenue and net income than in the same period a year earlier.
The stock closed at US$17.84 on November 5 and has been under pressure in recent months, with the 90-day share price return down 26.8% even though the 30-day share price return is up 2.8%. The 1-year total shareholder return is down 7.5% and the 5-year total shareholder return is down 52.5%, pointing to weak long term momentum despite the latest quarterly results from WillScot Holdings hinting at a shift in how investors weigh its earnings progress against past risks.
Scan beyond WillScot Holdings and compare how other capital goods players are trading by reviewing our curated list of 42 high quality undervalued stocks with resilient fundamentals and compressed expectations.
Bulls point to WillScot Holdings’ recent revenue and earnings progress, while bears highlight years of weak total returns and a market cap near US$3.5b. Which side does the current valuation actually support?
Most Popular Narrative: 31.9% Undervalued
On the most followed narrative, WillScot Holdings screens as undervalued, with a fair value estimate of $26.20 against the last close of $17.84. This puts the current share price at a steep discount to those long term assumptions.
Growing modular pending orders, up in a 13% to 17% range year over year with a large and mega project pipeline that extends into 2027 and includes data centers, power generation and manufacturing, point to future leasing revenue that the market may not be fully pricing into WillScot Holdings yet.
See why 5 investors see WillScot Holdings as 32% undervalued.
Result: Fair Value of $26.20 (UNDERVALUED)
Still, WillScot Holdings faces pressure from weaker portable storage demand and compressed adjusted EBITDA margins, which could limit how much of that project pipeline translates into earnings.
Find out about the key risks to this WillScot Holdings narrative.
Another View: What Multiples Say About WillScot Holdings
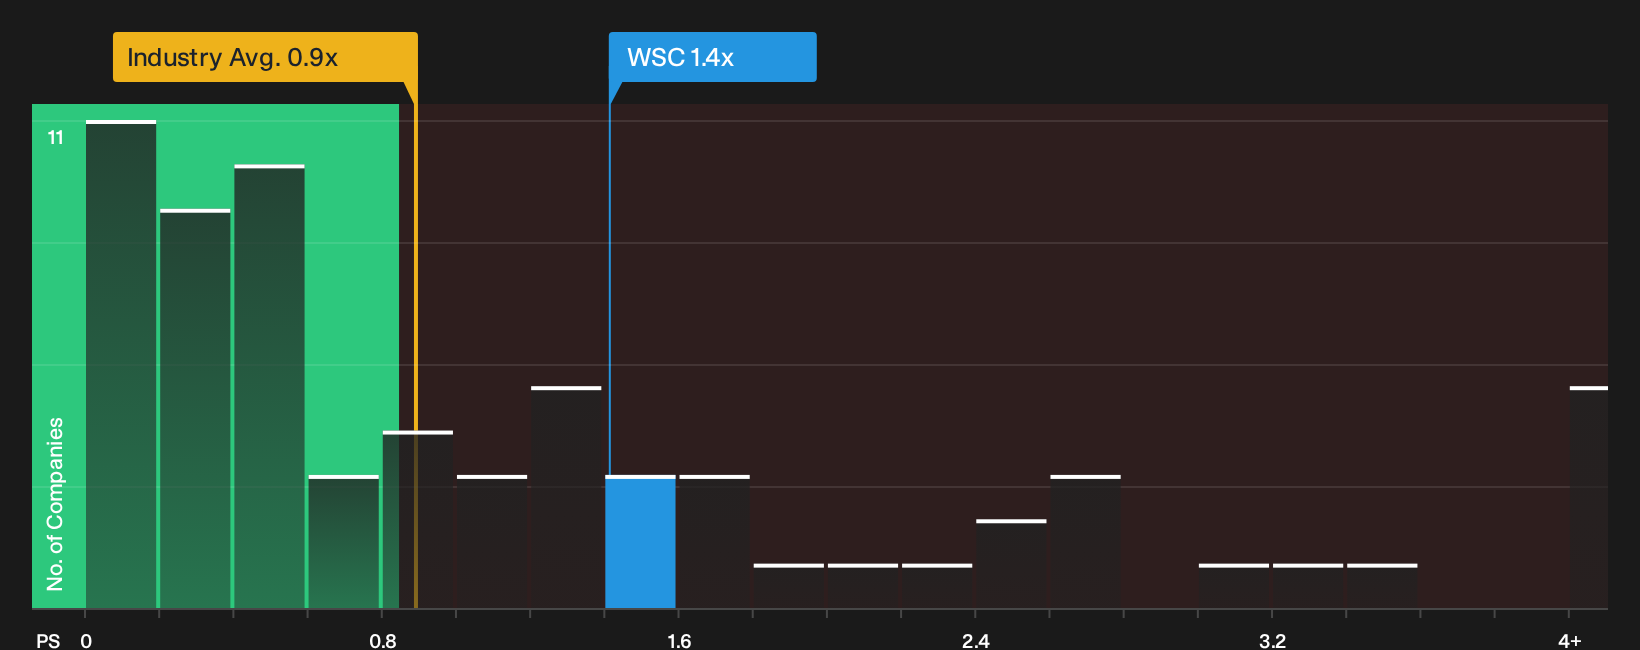
The DCF work suggests WillScot Holdings is trading below an estimated future cash flow value of $24.87, yet the P/S ratio tells a tougher story. At 1.4x sales, the stock trades richer than the US Construction industry at 0.9x and peers at 0.7x, even though the fair ratio sits higher at 2.4x. Is the discount in the cash flow model or the premium in the sales multiple sending the stronger signal?
For anyone weighing those competing signals, it helps to see how the current pricing lines up against a fuller valuation breakdown, including that fair ratio context, before deciding which story feels more convincing See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals or fresh opportunity, either way the faster you get familiar with WillScot Holdings’ story the sooner you can judge it on your terms. To weigh the downside against the potential upside for yourself, start with the full breakdown of 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond WillScot Holdings?
If WillScot Holdings has your attention, do not stop here. Broaden your watchlist now so you are not relying on a single story.
- Target potential upside in beaten down opportunities by scanning our 21 high quality undiscovered gems that pair solid fundamentals with limited market attention.
- Prioritise sleep at night holdings with the 32 resilient stocks with low risk scores that focus on resilience and lower overall risk scores.
- Focus on financial strength first by using the list of solid balance sheet and fundamentals (24 results) to concentrate on businesses with sturdier balance sheets and cleaner fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com