


Snap Inc. has seen its share price come under heavy pressure over the past few years, and that slide puts a sharper spotlight on whether the current US$5.09 tag is sensible when lined up against its sales base. With investors weighing product headlines, legal challenges, and shifting user trends, the key issue is how much revenue power the market is really paying for in Snap stock today.
- Over the past 5 years the share price has fallen 90.4%, which raises the question of how much of Snap's sales potential investors are now pricing into the stock.
- Recent reports of softer revenue momentum and slower user additions in key regions may influence how the market thinks about Snap's ability to convert engagement into future sales growth and cash generation.
- There is a second opinion on Snap worth weighing. See what analysts think Snap's shares could be worth.
For investors, the debate is whether Snap's current market value is adequately supported by the sales it is generating today and what that implies for its revenue base ahead.
If you want to stress test this same sales question beyond Snap, you can compare it with other companies using the 42 high quality undervalued stocks.
Is Snap Still Cheap on Sales?
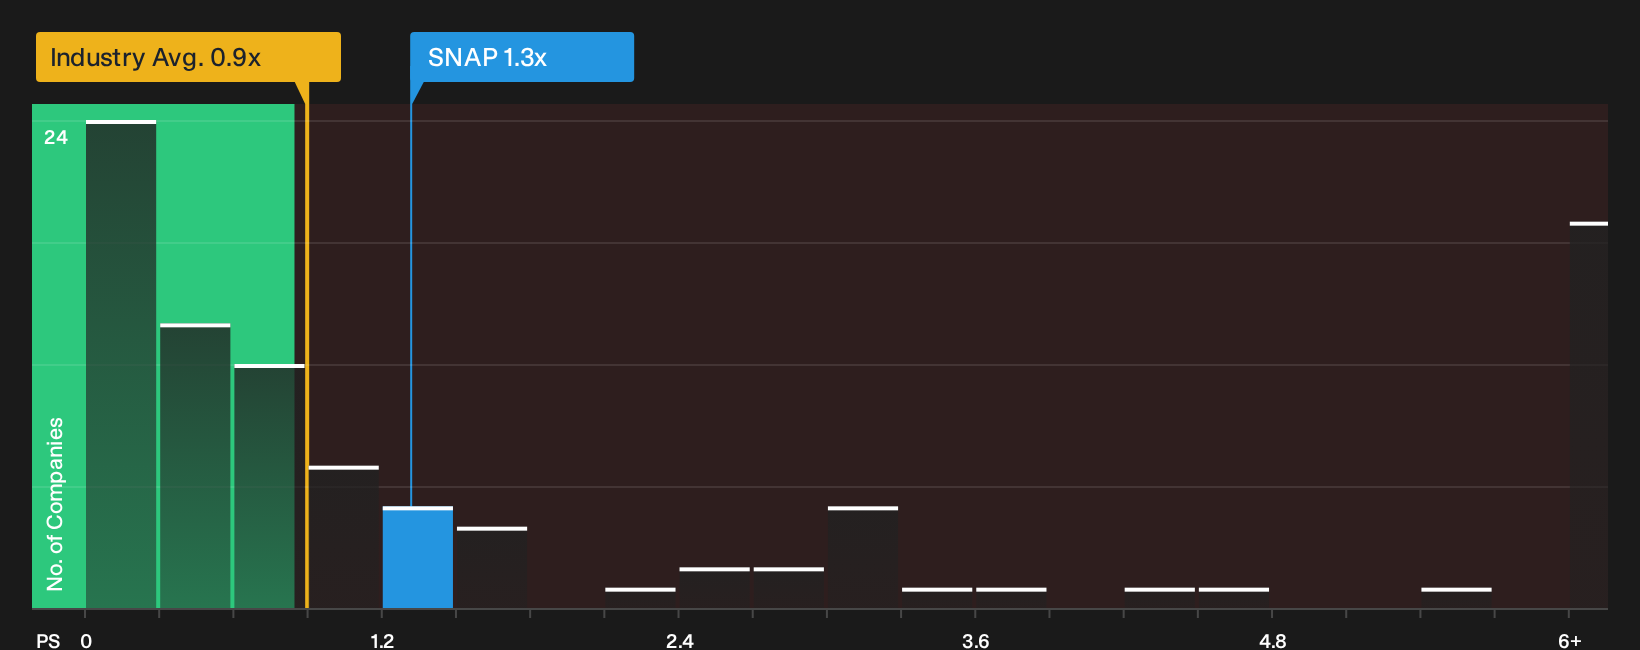
P/S is a clean way to look at Snap because the business is still better framed by revenue than by earnings. On this measure, Snap trades on a P/S of 1.3x, which is below both the Interactive Media and Services industry average of 0.9x and a peer group average of 2.0x. The Fair Ratio model, which estimates the kind of P/S that might fit Snap's growth profile, profitability pattern, size and risk, points to a higher level than where the shares change hands today. On this basis, the stock screens as undervalued on this lens.
Recent pressure after the Q3 revenue and user shortfall has pulled the P/S multiple down. Yet even after that reaction, Snap still trades below the level implied by that tailored Fair Ratio benchmark. For anyone weighing the lawsuits and product headlines against the current tag on each dollar of sales, the gap on this metric suggests the market is not paying up aggressively for Snap's existing revenue base. Explore the numbers behind Snap's P/S valuation.
The Snap Narrative: What Would Justify Today's Price?
Snap Narratives on Simply Wall St pick up where this valuation puzzle leaves off, by spelling out which paths for growth, margins and earnings would need to play out for Snap to trade meaningfully above or below today's level, and they sit on the stock's Community page. Rather than leaning on a single multiple or model output, each one lays out the assumptions behind its view of fair value so you can later compare those inputs with the actual results Snap reports.
The Snap conversation on Simply Wall St splits into two camps, with one community view seeing more upside in the story than the other.
Bull case: 31% undervalued
"Accelerating innovation in augmented reality (AR), including the upcoming public launch of Specs AR glasses in 2026 and continuous expansion of the AR developer ecosystem, positions Snap to benefit from both increased user engagement and the creation of premium advertising and subscription revenue streams…"
Discover why this Narrative puts Snap at 31% undervalued.
Bear case: roughly fairly valued
"While Snap is increasing AI and machine learning capacity to support its ad platform and internal tools, the higher 2026 infrastructure cost guidance of US$1.65b to US$1.70b risks eroding the intended gross margin gains if revenue does not keep pace…"
Explore why this Narrative puts Snap at roughly fairly valued.
One more Snap check that belongs next to the price tag
Who actually runs Snap, how their pay is structured, and whether those incentives align with long term shareholders is a separate piece of homework that can change how the whole story reads. See who runs Snap and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com