


U.S. Bancorp (USB) has reshaped its payments sales leadership, appointing Lauren Massuci to lead Financial Institutions Group Sales and Jose Quevedo to run Diversified Industries Sales, with the goal of sharpening its focus on industry specific client coverage.
The executive reshuffle lands after a mixed run in the market, with U.S. Bancorp’s share price up 4.3% over the past month but down 6.6% over ninety days, while total shareholder return has reached 32.4% over one year and roughly doubled over three years. This points to momentum built over longer horizons, even as recent moves, preferred stock changes and fresh bond issuance reset how investors think about risk and capital structure.
Scan the payments and banking space for other potential movers by checking the hand picked 42 high quality undervalued stocks that share some of U.S. Bancorp’s balance sheet and cash flow traits.
After a one month rebound but a softer ninety day stretch, U.S. Bancorp now sits at a crossroads for fresh money. Do current valuation markers still tip the risk reward balance toward buyers?
Most Popular Narrative: 13% Undervalued
At a last close of $59.75 against a narrative fair value of $68.50, U.S. Bancorp screens as discounted on this widely followed framework, with the gap hinging heavily on fee income durability and capital markets build out.
U.S. Bancorp's earlier focus on payments volumes, trust and investment management fees is now supported by fee income at 44% of total revenue in 2Q26 and low teens fee growth year over year, including about 10% excluding BTIG. This points to a larger and more durable fee base that can support revenue and earnings mix over time.
See why 98 investors see U.S. Bancorp as 13% undervalued.
Result: Fair Value of $68.50 (UNDERVALUED)
Still, the story around U.S. Bancorp can change if commercial real estate stresses worsen or if fintech competitors chip away at its payments and fee engine.
Find out about the key risks to this U.S. Bancorp narrative.
Another View: What U.S. Bancorp’s P/E Is Saying
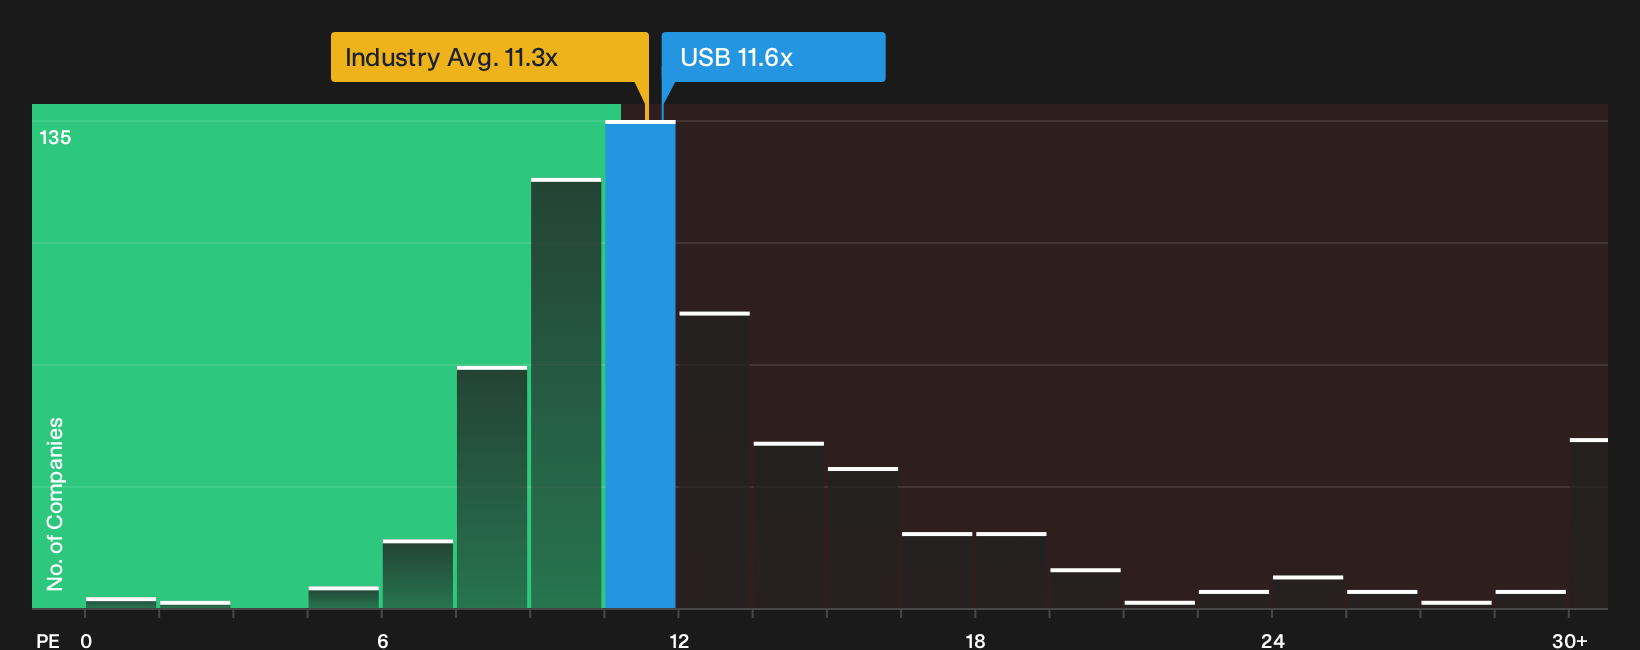
On the story driven fair value, U.S. Bancorp looks 13% undervalued. The P/E picture is less one sided. USB trades on 11.6x earnings, a touch above the US Banks industry at 11.3x. It is, however, below peers at 13.6x and under a fair ratio of 13.8x. That mix suggests some room for rerating but also reminds you that sentiment already prices in part of the quality story. Which signal do you trust more when putting fresh capital to work?
To see how this pricing gap could change if earnings or sentiment reset, take a closer look at the valuation breakdown built off this earnings multiple view: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or quiet opportunity? If U.S. Bancorp has your attention, move quickly from headlines to hard numbers and weigh the upside for yourself with the 4 key rewards.
Looking for more U.S. Bancorp sized investment ideas?
If U.S. Bancorp has sharpened your thinking, back it up with a wider watchlist so you are not relying on a single story or sector.
- Target steady income first by scanning companies in the 6 dividend fortresses that may help anchor returns when prices move around.
- Hunt for resilient balance sheets using the list of solid balance sheet and fundamentals (24 results) so potential blow ups do not quietly creep into your portfolio.
- Chase under followed quality by checking the 21 high quality undiscovered gems before the rest of the market pays attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com