


On Holding (ONON) is back in focus after reporting revenue growth of 13.5% year over year and an 81.1% jump in earnings per share, alongside net cash of CHF 439.4 million.
Recent trading in On Holding has been choppy, with the share price up 14.45% over the past week and 13.31% over the past month, yet still down 20.04% on a year to date basis. Despite that pullback, total shareholder return of 5.72% over one year and 39.14% across three years indicates that longer term holders have been rewarded as sentiment has gradually improved around the growth story.
Look beyond On Holding and compare its momentum and balance sheet strength with a curated set of list of solid balance sheet and fundamentals (24 results).
The share price reset, the earnings jump, and a roughly 14% discount to analyst targets leave On Holding looking cheaper on paper, yet market caution lingers. Does the current valuation fairly reflect that hesitancy?
Most Popular Narrative: 13% Undervalued
On Holding's most followed narrative pegs fair value at $43.27, above the recent $37.54 close, which frames the current discount as valuation rather than just sentiment. That lens puts more weight on how the premium brand and direct sales mix evolve than on short term share price swings.
The acceleration in DTC and e commerce channels remains a live driver, with DTC reaching 45.7% of Q2 2026 net sales and growing faster than the group, which gives On Holding more control over pricing and merchandising and can support higher gross margin and EBITDA margin over time.
See why 129 investors see On Holding as 13% undervalued.
Result: Fair Value of $43.27 (UNDERVALUED)
Still, the bullish On Holding narrative depends on premium pricing holding with consumers, and on heavy DTC and store investment not eroding margins if returns disappoint.
Find out about the key risks to this On Holding narrative.
Another View: What Multiples Say About On Holding
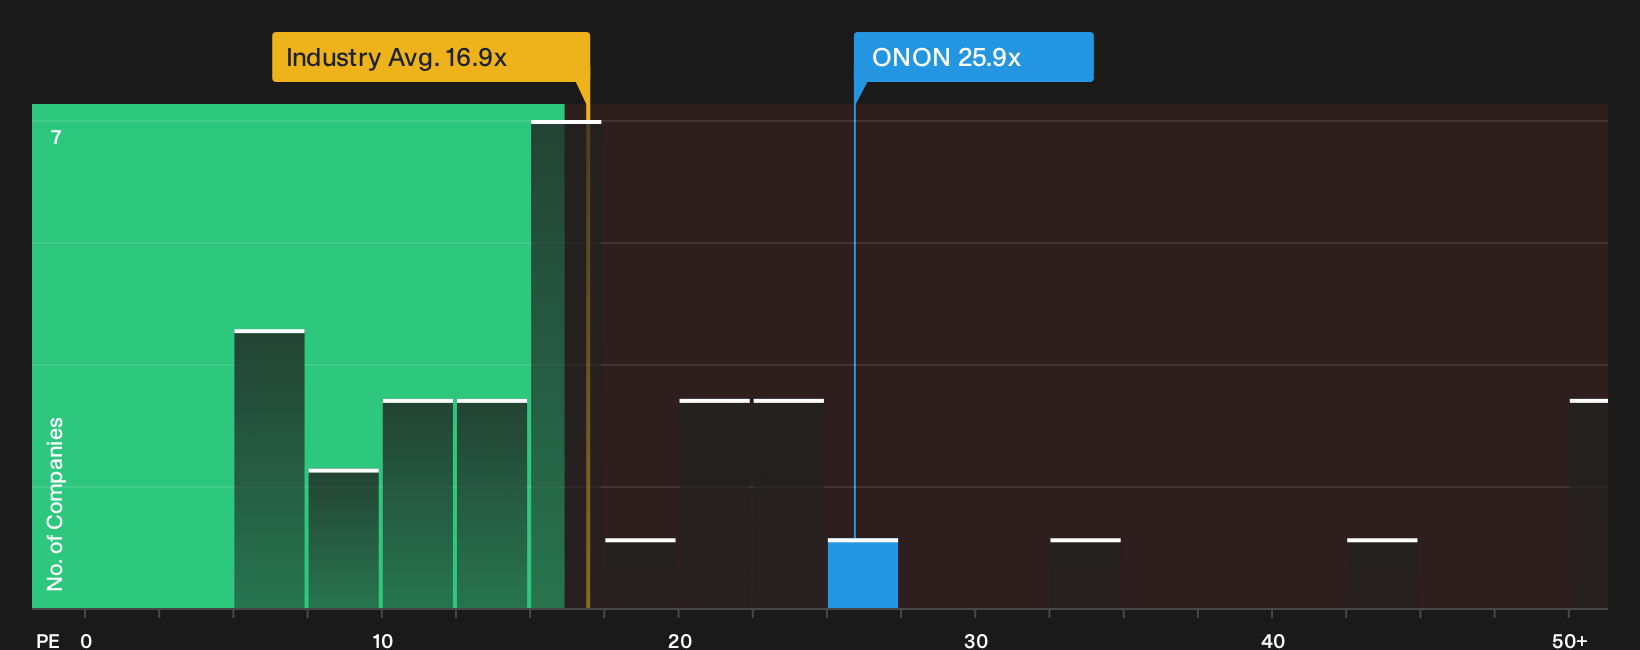
That 13% discount to fair value from the narrative and future earnings work is only one lens. On Holding trades on a P/E of 25.9x, compared with a fair ratio of 24.4x, the US Luxury industry at 16.9x and peers at 14.7x, which signals investors are already paying a clear premium. Is that extra valuation comfort, or extra risk if the growth story hits a bump?
To see how this premium stacks up against the underlying numbers, and where the ratio could drift if sentiment cools or improves, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Reading this, you might sense optimism tugging against caution. The only way to balance that is to interrogate the numbers yourself and move decisively. To see what has investors excited about On Holding right now, take a closer look at its 3 key rewards.
Looking for more investment ideas beyond On Holding?
On Holding may be front of mind today, yet your next strong opportunity could sit in a very different corner of the market. Do not leave that on the table.
- Hunt for overlooked quality by scanning a 21 high quality undiscovered gems list that filters for strong fundamentals and solid business profiles.
- Prioritise resilience by reviewing a 32 resilient stocks with low risk scores that highlights companies with stronger balance sheets and fewer red flags.
- Target stability and income by checking a 6 dividend fortresses focused on higher yielding payers that still keep an eye on financial health.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com