


Shift4 Payments (FOUR) has dropped into focus after its Q3 2026 update, where revenue and adjusted earnings surpassed expectations, but a cut to full year EPS guidance pulled sentiment in the other direction.
For context, Shift4 Payments shares closed at US$42.79. The 7 day share price return of 9.02% and 30 day share price return of 11.14% show a short burst of momentum after a difficult year in which total shareholder return fell 35.96%, and longer term 3 and 5 year total shareholder returns also moved lower.
The 1 day share price return declined 4.53% around the Q3 release. This lines up with investors reacting to the reduced full year EPS guidance, even as the business reported an earnings beat and announced an expanded share repurchase plan that affects how future returns are split across a smaller pool of shares.
Scan how the guidance cut at Shift4 Payments compares with other listed processors by reviewing hand picked 42 high quality undervalued stocks, which pair solid cash flows with balance sheets the market may be underpricing.
After that earnings beat, guidance cut and fresh buyback, the question around Shift4 Payments is simple: Has the recent rebound already captured most of the upside, or is the valuation still leaving meaningful room ahead?
Most Popular Narrative: 19% Undervalued
Based on the most followed narrative, Shift4 Payments is framed as undervalued, with a fair value of $52.55 against the last close at $42.79. The valuation hinges on how well management turns international expansion and acquisitions into sustained free cash flow.
Ongoing consolidation in the payments industry, coupled with Shift4 Payments three part capital allocation approach that includes tuck in M&A and a planned roughly US$300 million account to account payments acquisition that is not yet in guidance, supports further scale benefits on top of a 46% adjusted EBITDA margin in Q2 2026 and a stated aim for roughly 60% incremental EBITDA to free cash flow conversion. This can increase free cash flow per share as integration progresses.
See why 69 investors see Shift4 Payments as 19% undervalued.
Result: Fair Value of $52.55 (UNDERVALUED)
Still, the Shift4 Payments story can break if prolonged travel disruption keeps squeezing tax free shopping volumes, or if higher interest costs and leverage cap future earnings progress.
Find out about the key risks to this Shift4 Payments narrative.
Another View: What Multiples Say About Shift4 Payments
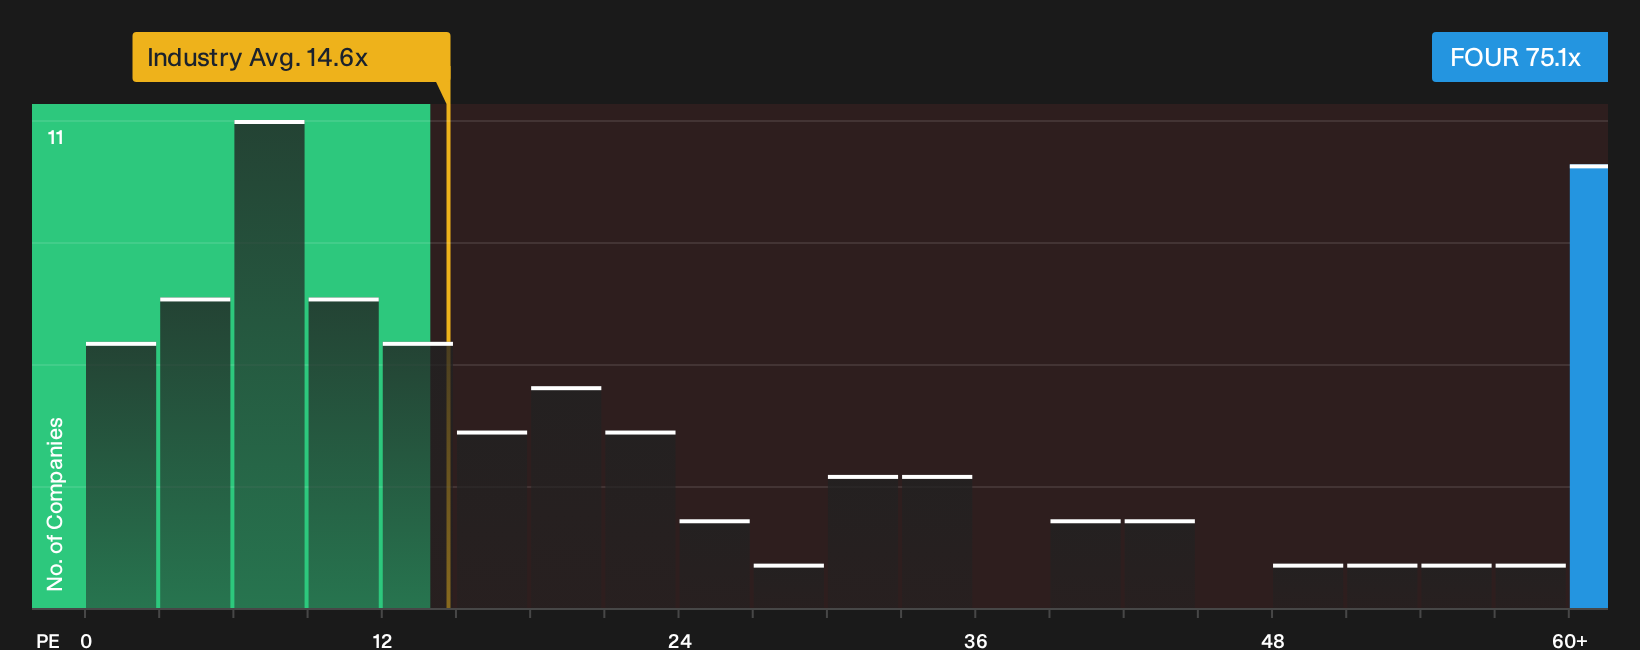
The narrative around Shift4 Payments leans on a fair value of $52.55, yet the current P/E of 75.1x tells a different story. That multiple is far above the US Diversified Financial industry at 14.7x, the peer average at 36.3x, and even the 21.5x fair ratio.
Such a gap can mean investors are paying a high price today for earnings that analysts still disagree on. This raises the risk that sentiment shifts hit the share price harder if expectations change. The question for you is whether that premium feels earned, or simply fragile.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around Shift4 Payments feels familiar, that is exactly why it pays to dig into the underlying data yourself right now and test whether the balance of risks and rewards fits your own tolerance and time horizon by reviewing the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Shift4 Payments?
If Shift4 Payments has sharpened your thinking, use that momentum and line up a shortlist of fresh ideas that suit your goals before the next move hits.
- Target potential mispricing and upgrade your watchlist with the 42 high quality undervalued stocks that combine quality fundamentals with market skepticism.
- Lock in potential income streams by reviewing the 6 dividend fortresses that focus on higher yields alongside durability.
- Protect your downside and stress test your risk tolerance using the 32 resilient stocks with low risk scores that highlight more resilient balance sheets and earnings profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com