


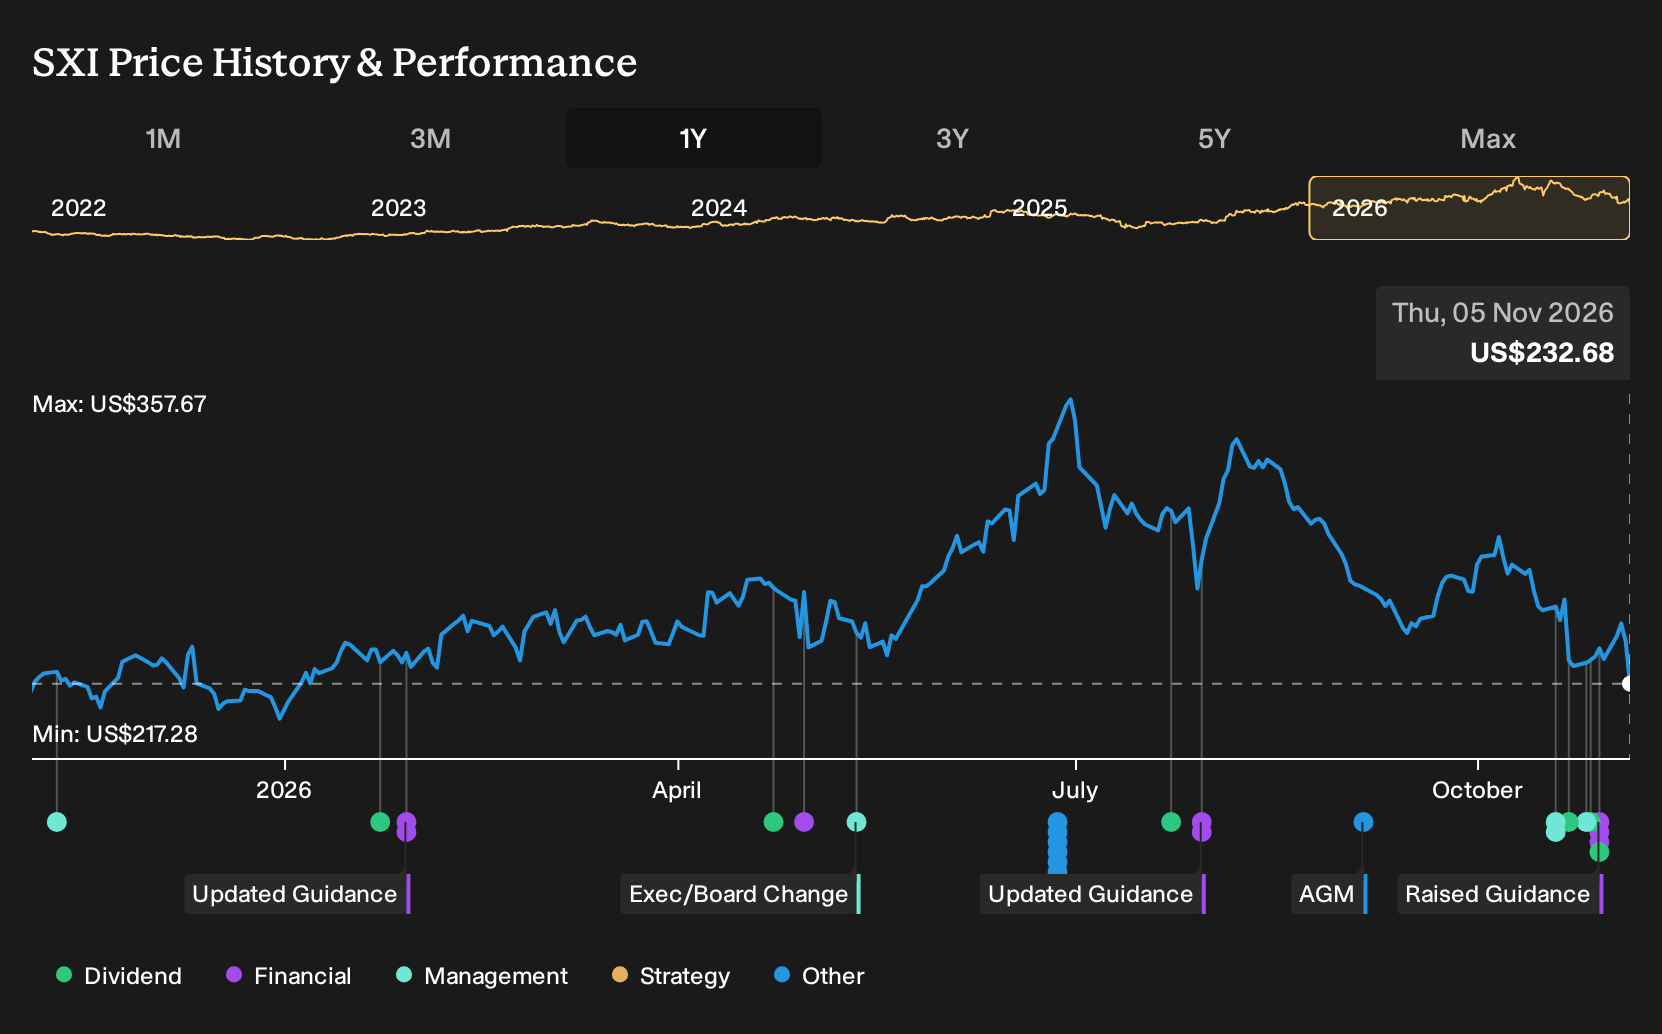
- Standex International reported first quarter 2027 sales of US$232.58 million and net income of US$24.17 million, with basic earnings per share of US$2 and diluted earnings per share of US$1.98. The company now guides to moderately higher revenue for the fiscal second quarter.
- Management raised its Fiscal Year 2027 total sales outlook to high single digit growth and paired that with a fresh US$100 million share repurchase authorization, following completion of a prior buyback plan that retired 596,592 shares for US$77.03 million.
- We will now look at how Standex International's first quarter earnings and higher full year sales outlook shape the investment narrative.
Compare Standex International's guidance and fresh buyback with hand-picked peers by scanning for financially resilient companies in the 32 resilient stocks with low risk scores that are also returning capital to shareholders.
Standex International Investment Narrative Recap
For a shareholder in Standex International, the core belief is that the shift toward higher margin electronics, grid, and aerospace and defense components can keep translating into healthy earnings and cash generation. The first quarter of fiscal 2027 fits that story, with higher sales and net income, plus raised full year sales guidance to high single digit growth. The near term swing factor is whether organic demand in these focus areas holds up.
The biggest operational risk right now sits around a potential slowdown in that organic growth, especially after a year that included a large one off gain and very strong earnings expansion. The new guidance for moderately higher fiscal second quarter revenue is helpful but not transformational on its own. Debt coverage by operating cash flow also still needs close watching.
The fresh US$100 million share repurchase authorization is the development that ties closest to this update. It follows completion of the May 2022 program that retired 596,592 shares for US$77.03 million and arrives just as Standex International raises its sales outlook. For investors, the plan directly links capital returns to the firm’s confidence in its balance sheet and earnings profile.
Execution remains the key catalyst. Progress on grid capacity builds, new product launches, and aerospace and defense programs will likely do more to support the long term narrative than the buyback itself, which does not change the underlying business trajectory. The plan does introduce another lever on per share metrics at a time when the stock trades at a P/E above some peer and fair value estimates.
Standex International's current analyst narrative points to revenues of US$1.1b and earnings of US$164.5 million by 2029, based on an assumed 7.7% yearly revenue growth rate and an earnings increase of about US$59.7 million from US$104.8 million today.
Uncover how Standex International's fair value indicates a 45% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Fair value estimates for Standex International from 2 individual views in the Simply Wall St Community range from about US$244.53 to US$338.40, so retail opinions already span a wide band. Consider that in light of risks around a potential slowdown in organic growth and return on invested capital, and it becomes clearer why investor opinions can differ sharply. Explore several of these alternative viewpoints before deciding how this mix of raised guidance, fresh buybacks, and grid and defense projects fits into your own framework.
Explore another Standex International fair value estimate, including one that suggests as much as 45% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Standex International research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Standex International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Standex International's overall financial health at a glance.
Looking For More Investment Ideas Beyond Standex International?
Standex International may fit parts of your checklist, but the market is full of other companies with different risk and return profiles that could match your goals even better. Use the Simply Wall St Screener to systematically filter for financial strength, valuation, and income characteristics rather than relying on headlines or hunches.
- If capital preservation and a smoother ride matter most to you, start with a curated set of resilient businesses in the 32 resilient stocks with low risk scores that score well on stability and risk controls.
- For investors hunting for quality at a sensible entry point, scan through a focused pool of potential bargains in the 42 high quality undervalued stocks that pair healthy fundamentals with attractive pricing.
- If income is a priority and you want payments that aim to be both meaningful and supported by underlying cash flows, review the high yielding opportunities in the 6 dividend fortresses that meet a 5%+ threshold.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com