


Coinbase Global has seen its share price fall 60.1% over the past five years, and with crypto sentiment swinging on security scares and regulation, the question now is whether today’s valuation can still be explained by its sales base.
- That 60.1% five year decline means anyone looking at Coinbase today is effectively reassessing what the current revenue line is worth after a long and volatile journey.
- The company’s push into prediction markets, stablecoin payments and staking, alongside tighter security credentials after the Binance hack, can influence how durable and diversified its future sales mix looks to investors.
- There is a second opinion on Coinbase Global worth weighing. See what analysts think Coinbase Global's shares could be worth.
The stock's next move may depend on whether Coinbase's current share price asks too much of its sales or still leaves room against what the business is generating today.
If you want to test the same sales based valuation question that Coinbase Global now faces across a wider set of crypto exposed stocks, take a look at 18 cryptocurrency and blockchain stocks.
Has Coinbase Global Run Too Far on Sales?
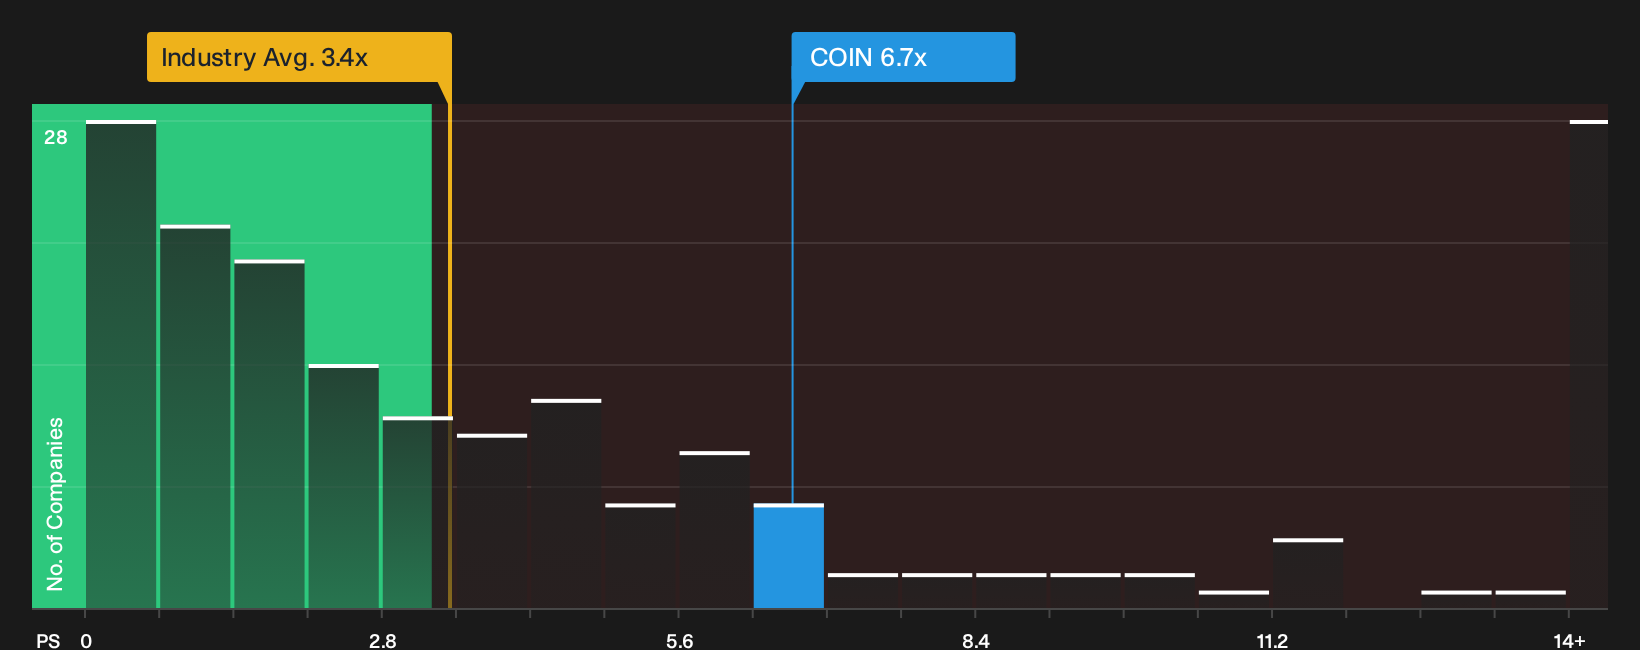
P/S is usually a better yardstick for Coinbase Global than P/E, because earnings tend to be more volatile than revenue in this kind of fee based platform. On that basis, the stock trades on a P/S of 6.7x, compared with an industry average of 3.4x and a peer group closer to 10.6x. That leaves Coinbase valued at a premium to broader capital markets players, but at a lower revenue multiple than more crypto focused comparables.
The fair multiple model, which adjusts for Coinbase Global’s growth profile, profitability and risk versus similar businesses, points to a lower P/S than the market is currently paying, so the shares appear overvalued on this metric. Despite the recent Binance hack putting more attention on Coinbase’s security record, the valuation still reflects a higher price per dollar of current sales than the tailored benchmark suggests. Explore the numbers behind Coinbase Global's P/S valuation.
The Coinbase Global Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Coinbase Global valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than today. Each scenario ties its number to a clear view on how Coinbase Global's expansion, profitability and risk profile could evolve, giving you a reference point you can revisit as fresh information arrives on the Community page.
Community views on Coinbase Global split between those who see more upside in the current mix of products and those who treat it as closer to fully valued.
Bull case: 35% undervalued
"Expansion of Coinbase Global from a primarily spot crypto venue to an 'Everything Exchange' with four trading verticals and 12 product lines, each around or above US$100 million in annual revenue, could support a broader, more diversified transaction fee base over time, which can influence revenue resilience and earnings quality..."
Discover why this Narrative puts Coinbase Global at 35% undervalued.
Bear case: roughly fairly valued
"Bearish analysts expect Coinbase Global to remain heavily exposed to crypto trading cycles, with fee compression and volatile activity keeping earnings and cash flow at risk..."
Explore why this Narrative puts Coinbase Global at roughly fairly valued.
One more question for Coinbase Global that the valuation cannot answer alone
Price multiples tell you what investors pay for Coinbase Global today, but analyst projections for revenues and profits a few years out offer a different lens to compare with that price. Explore where analysts expect Coinbase Global to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com