


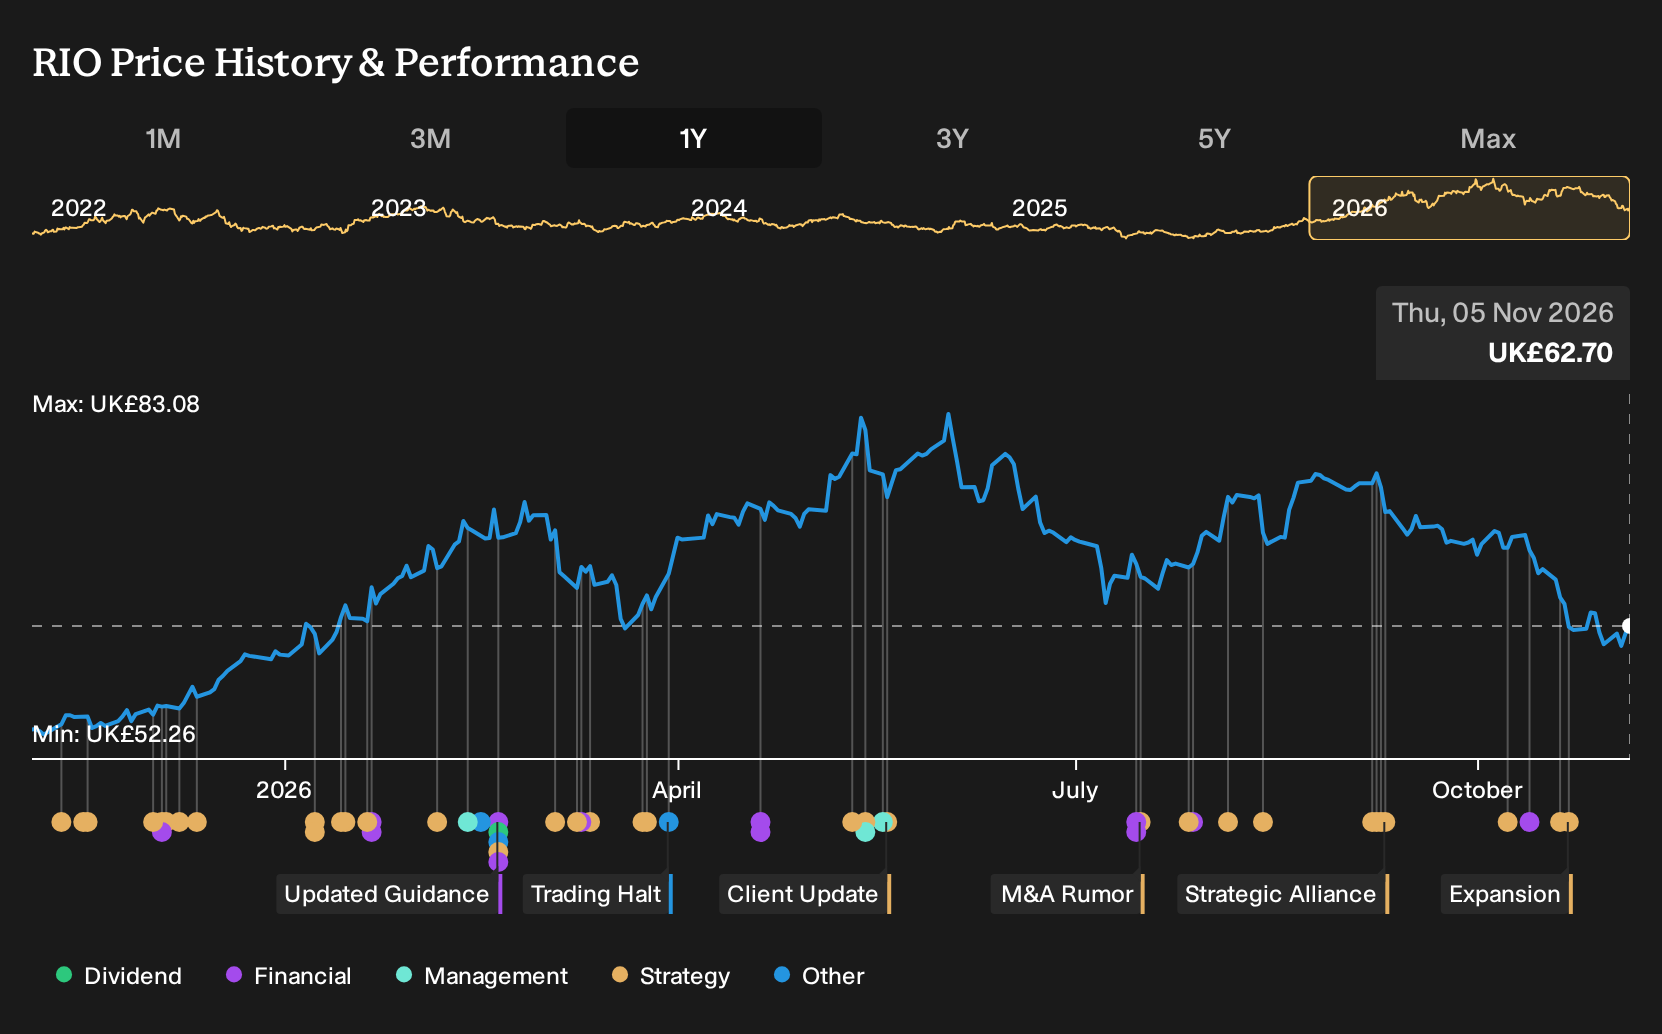
If you had bought Rio Tinto Group on 5 November 2025 and simply sat on your hands, the outcome would look very different today. Holding Rio Tinto Group over the past year would have returned 25.1%, including dividends. That result now sits alongside fresh headlines about new copper projects, low carbon aluminum expansions, class action claims and shifting analyst views. If you were staring at those competing stories back then, which signals would you have trusted enough to act on?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Rio Tinto Group has already moved. Pinpoint other ways to investigate the theme among 16 top copper producer stocks.
The Two Rio Tinto Stories Investors Were Arguing About
The shares cost £52.78 at the start of the period, and anyone looking at Rio Tinto Group then had to choose between two very different stories about where the miner might be heading.
On the bullish side, one Narrative put Fair Value at £67.78. That view leaned on faster project ramp ups at Oyu Tolgoi, Simandou and Rincon, with revenue growth assumptions of 4.6% a year and profit margins rising from 19.1% to 20.0% by about 2028.
The bearish Narrative argued Fair Value was £39.91. It focused on aging Pilbara iron ore assets, rising costs and decarbonization pressures, with revenue assumed to decline 1.8% a year and margins easing from 19.1% to 16.9% over the next 3 years.
What The Results Changed For The Rio Tinto Group Debate
Fresh H1 2026 numbers gave Rio Tinto Group bulls some backing. Revenue moved from US$26,873m to US$31,028m and net income from US$4,528m to US$6,664m. Net margin went from 16.8% to 21.5%. That combination leaned toward the optimistic case that argued for stronger profitability, even though future copper growth and project risk still keep the overall picture mixed.
The lesson is simple. When a story hinges on better margins, check whether net income and the reported net margin actually move in the direction the thesis needs, not just the top line.
What Rio Tinto’s Price Now Asks You To Believe
Rio Tinto Group trades at £62.7 today, up from £52.78 over the past year. The selected Narrative puts Fair Value above that level and ties the gap to how well the miner turns its copper, aluminum and lithium pipeline plus productivity plans into durable cash generation.
If you buy at today’s price, the key assumption to test is whether Rio Tinto Group can keep delivering its productivity and cost reduction program while bringing big projects like Simandou and Oyu Tolgoi online without major ESG or operational setbacks.
"Key Takeaways: Analysts expect Rio Tinto Group to use its growing copper, aluminum and lithium production and productivity gains to keep building exposure to long-term electrification, AI and urbanisation demand for its key commodities. The main thing that has to go right is continued delivery of the productivity and cost reduction program while executing large projects like Simandou, Oyu Tolgoi, lithium developments and Kangwinan without major ESG, safety or social licence setbacks."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
How Could You Get There Earlier?
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 38% below our estimate - uses an AI-enabled member ecosystem to drive higher margin referral revenue.
- Company 2 - 39% below our estimate - advances a late stage drug pipeline addressing patent expiries and reinvestment needs.
- Company 3 - 42% below our estimate - rolls out new leisure centres while applying pricing tools to protect cash margins.
Those are three of them. See all 15 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com