


Monster Beverage (MNST) just posted third quarter results that put international growth in the spotlight. Revenue and net income both moved higher year over year, while gross margin came under pressure from mix and cost headwinds.
The latest Q3 report has arrived during a strong period for Monster Beverage, with the share price delivering a 10.59% return over the past 30 days and a 25.60% share price return year to date. The 1-year total shareholder return of 44.26% and 5-year total shareholder return of 107.35% indicate momentum that long-term holders have already been rewarded for, as traders now weigh faster international growth against margin pressure at a recent share price of US$47.83.
Scan beyond Monster Beverage and compare its recent surge with hand picked 21 high quality undiscovered gems that have strong fundamentals but far less attention on them.
After a 44.26% 1 year total return and solid Q3 progress from Monster Beverage, the valuation question is simple: Is most of the upside already reflected, or is the recent move just the opening act?
Most Popular Narrative: 4.8% Undervalued
On the most followed view, Monster Beverage screens modestly below a fair value estimate of $50.24, compared with the latest $47.83 close. This puts the spotlight on how durable its international and mix driven story really is.
Strong double digit energy category value growth in regions such as APAC, EMEA and LATAM, combined with Monster Beverage’s 34.6% international net sales growth to US$1.16b in Q2 2026 and rising contribution from markets like China, India, Brazil and Mexico, reinforces the view that continued international expansion can increase revenue and diversify earnings.
See why 71 investors see Monster Beverage as 5% undervalued.
Result: Fair Value of $50.24 (UNDERVALUED)
Still, the story can break if distribution and freight expenses keep climbing faster than price increases, or if rising aluminum costs squeeze Monster Beverage gross margin more than expected.
Find out about the key risks to this Monster Beverage narrative.
Another View: Monster Beverage Through The P/E Lens
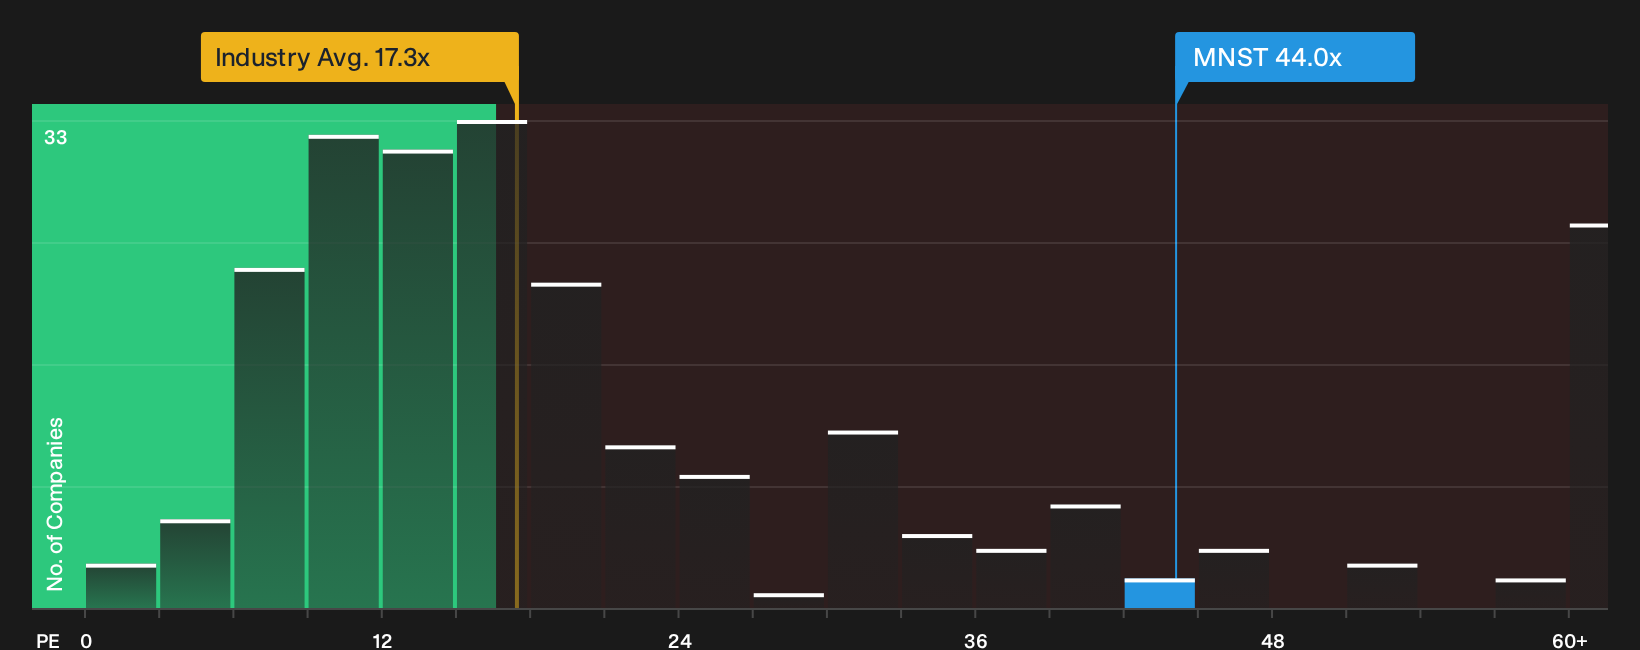
The story looks different when you park the fair value estimate and just look at what investors are paying for Monster Beverage’s earnings. The stock trades on a P/E of 44x, while the global beverage group averages 17.3x and direct peers sit around 24.5x.
The fair ratio for Monster Beverage is 25.2x, which is much closer to those peer and industry levels than to the current 44x. That gap points to valuation risk if sentiment cools, even if the underlying business keeps progressing. The question is whether you think Monster Beverage has enough quality and staying power to justify that premium multiple.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Monster Beverage is split between enthusiasm and caution, which is exactly why you should move quickly and inspect the numbers yourself. To see what optimistic investors are focusing on, review the 2 key rewards
Looking for more Monster Beverage style investment ideas?
If Monster Beverage has your attention, do not stop here. Broader opportunities often sit just outside the obvious tickers, and missing them can cost real upside.
- Target stronger potential value by scanning companies that combine quality fundamentals with attractive pricing through the 42 high quality undervalued stocks.
- Strengthen your income stream by reviewing a curated set of higher yielding payouts using the 6 dividend fortresses.
- Reduce portfolio stress by focusing on resilient businesses with sturdier financial profiles via the 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com