


Carlyle Group has seen its share price move in very different directions over recent periods, which raises a simple question for investors who focus on earnings. At today's level, is the stock price in line with what the business is actually earning for shareholders?
- Over the past 3 years the stock has gained 44.9%, which puts real weight on whether current earnings can carry that kind of share price progress.
- The recent deal where Oak Hill Capital agreed to acquire a majority stake in Wyyerd from Carlyle, with Carlyle keeping a minority position, may shift how quickly the firm realizes gains from that asset and how its fee and investment income profile evolves from here.
- There is a second opinion on Carlyle Group worth weighing. See what analysts think Carlyle Group's shares could be worth.
The issue now is whether Carlyle Group's current share price is adequately supported by the earnings that the business is generating today.
If you are weighing Carlyle Group's earnings against its recent 3 year gain, it can help to line it up against other companies through 42 high quality undervalued stocks.
Does Carlyle Group Look Pricey on Earnings?
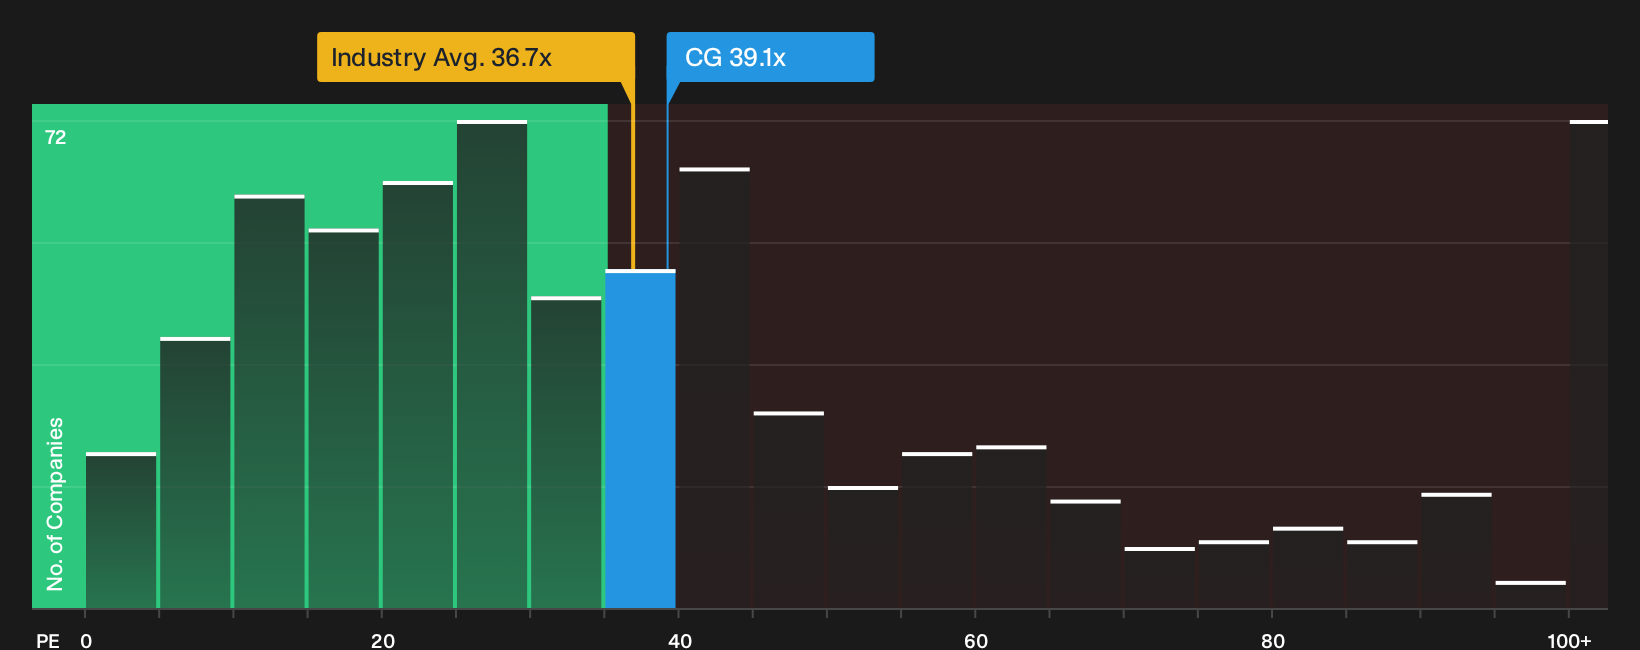
The P/E ratio fits Carlyle Group because earnings tend to matter more than revenue or assets for fee based asset managers. On this metric, Carlyle Group trades at about 39.1x earnings, compared with roughly 36.7x for the wider Capital Markets industry and about 30.6x for its peer set. This means the market is asking you to pay a higher price for each dollar of profit than both the sector and similar firms.
The Fair Ratio model, which blends the business's growth profile, margins, size and risk into a customised benchmark, sits below that current P/E. On this framework, the stock screens as overvalued. Because the recent Wyyerd deal underlines Carlyle Group's active portfolio reshaping, the premium multiple suggests investors are already assigning a full price to those repositioning efforts. Explore the numbers behind Carlyle Group's P/E valuation.
The Carlyle Group Narrative: What Would Justify Today's Price?
Narratives pick up where Carlyle Group's valuation puzzle leaves off by spelling out what would need to happen to growth, margins and earnings for the current share price to look too high or too low. Each scenario lays out the assumptions that sit behind its view of fair value so you can compare those expectations with Carlyle Group's actual results as new numbers are reported.
One of the top community narratives on Carlyle Group: 24% undervalued
"The valuation opportunity depends on Carlyle converting its operational improvements into more consistent earnings..."
Discover why this Narrative puts Carlyle Group at 24% undervalued.
One last check for Carlyle Group before you stop at the share price
Carlyle Group’s valuation only tells part of the story. The people making capital decisions and the way they are rewarded can pull outcomes in very different directions over time. See who runs Carlyle Group and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com