


Darden Restaurants (DRI) has been hit with a new class action lawsuit in California alleging multiple labor code violations, while almost simultaneously renewing and expanding its revolving credit facility to US$1.5b through 2031.
The new lawsuit and enlarged credit facility arrive after a strong run in Darden Restaurants’ shares, with a 30 day share price return of 12.57% and a year to date share price gain of 22.15%. Total shareholder return sits at 32.91% over one year and 69.95% across three years, suggesting that momentum has been building as investors weigh both growth ambitions and a changing risk profile.
Scan how the legal overhang and fresh US$1.5b credit line at Darden Restaurants compares to other consumer names with resilient balance sheets using our hand picked list of solid balance sheet and fundamentals (24 results)
Bulls see Darden Restaurants using its credit firepower and recent share price strength to keep rewarding patient holders. Bears point to legal risk and momentum fatigue. Which story do the current valuation markers support?
Most Popular Narrative: 2% Undervalued
Darden Restaurants closed at $228.67, sitting slightly below the most followed narrative’s fair value estimate of $233.44. This estimate is based on a 9.33% discount rate and long term earnings forecasts.
Darden Restaurants is stepping up unit growth with 71 openings in fiscal 2026 and guidance for 75 to 80 new openings plus 11 Bahama Breeze conversions in fiscal 2027, and is using smaller Yard House prototypes to lower build costs, which together can increase total system sales while spreading fixed costs and supporting earnings over time.
See why 17 investors see Darden Restaurants as 2% undervalued.
Result: Fair Value of $233.44 (UNDERVALUED)
Still, Darden Restaurants faces two swing factors: softer Olive Garden traffic in a weakening casual dining backdrop, and market sensitivity to any same restaurant sales miss.
Find out about the key risks to this Darden Restaurants narrative.
Another View: Darden Restaurants Through A DCF Lens
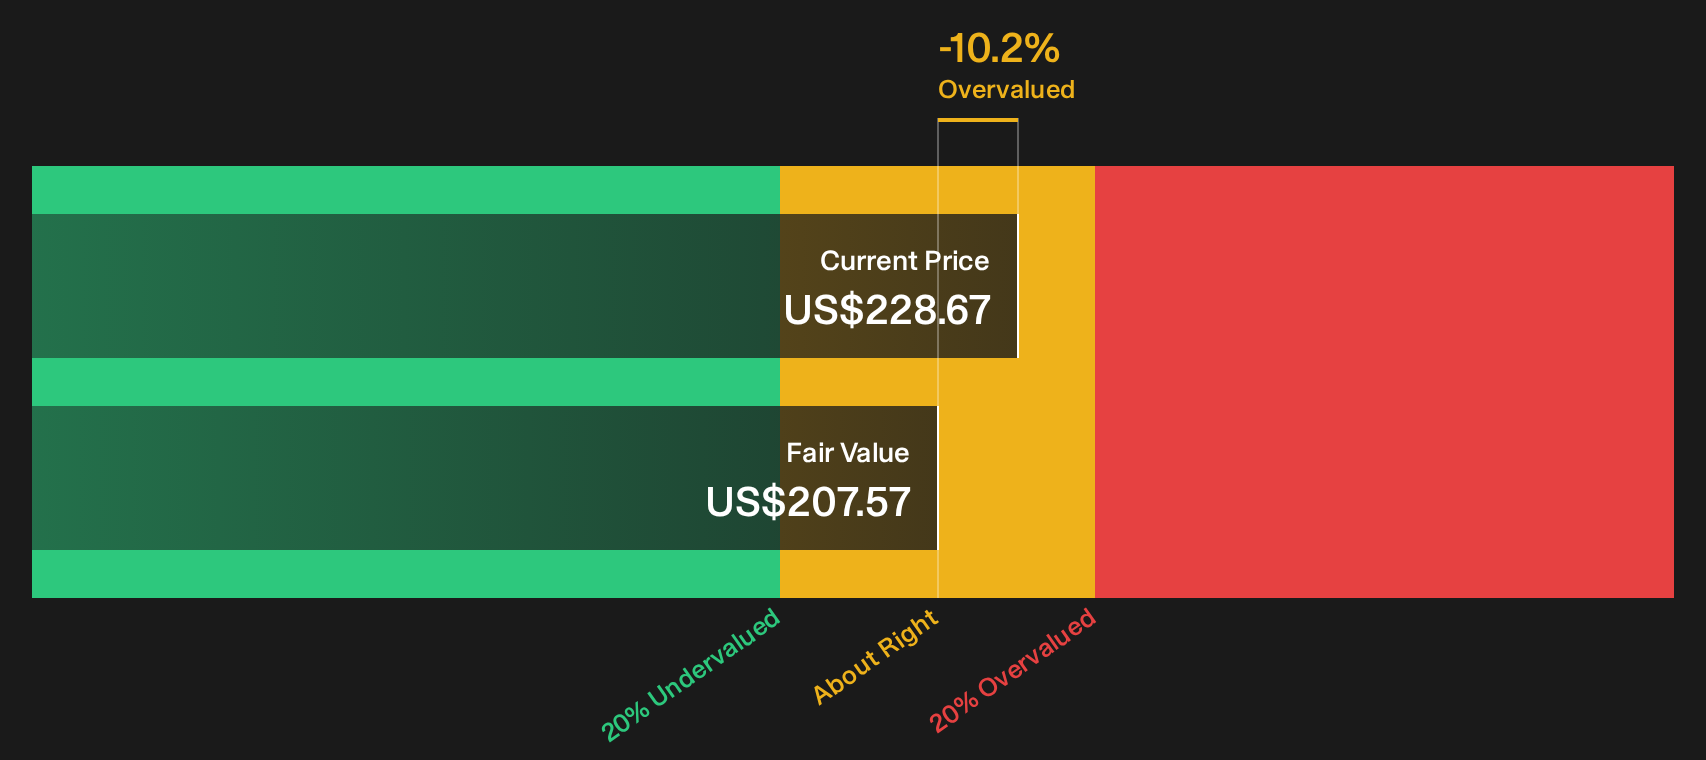
The crowd narrative sees Darden Restaurants as about 2% undervalued against a $233.44 fair value, yet the SWS DCF model points the other way. On that cash flow view, the shares at $228.67 sit above an estimated value of $207.57, which flags the stock as overvalued. Which signal do you put more weight on: earnings multiples or cash flows?
To understand how that cash flow result was built and what would need to change for the story to flip, take a closer look at the SWS DCF model output in full Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Darden Restaurants for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the data so far? Move quickly, review both the upside drivers and pressure points for yourself, then weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Darden Restaurants?
Do not stop your research with a single restaurant stock when the broader market may hold better fits for your goals and tolerance for risk.
- Target powerful upside potential by scanning focused opportunities through 9 elite penny stocks with strong financials.
- Strengthen your core holdings by reviewing companies that combine quality with attractive pricing using the curated 42 high quality undervalued stocks.
- Build a steadier income stream by checking out businesses filtered for resilience and reliability through the 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com