


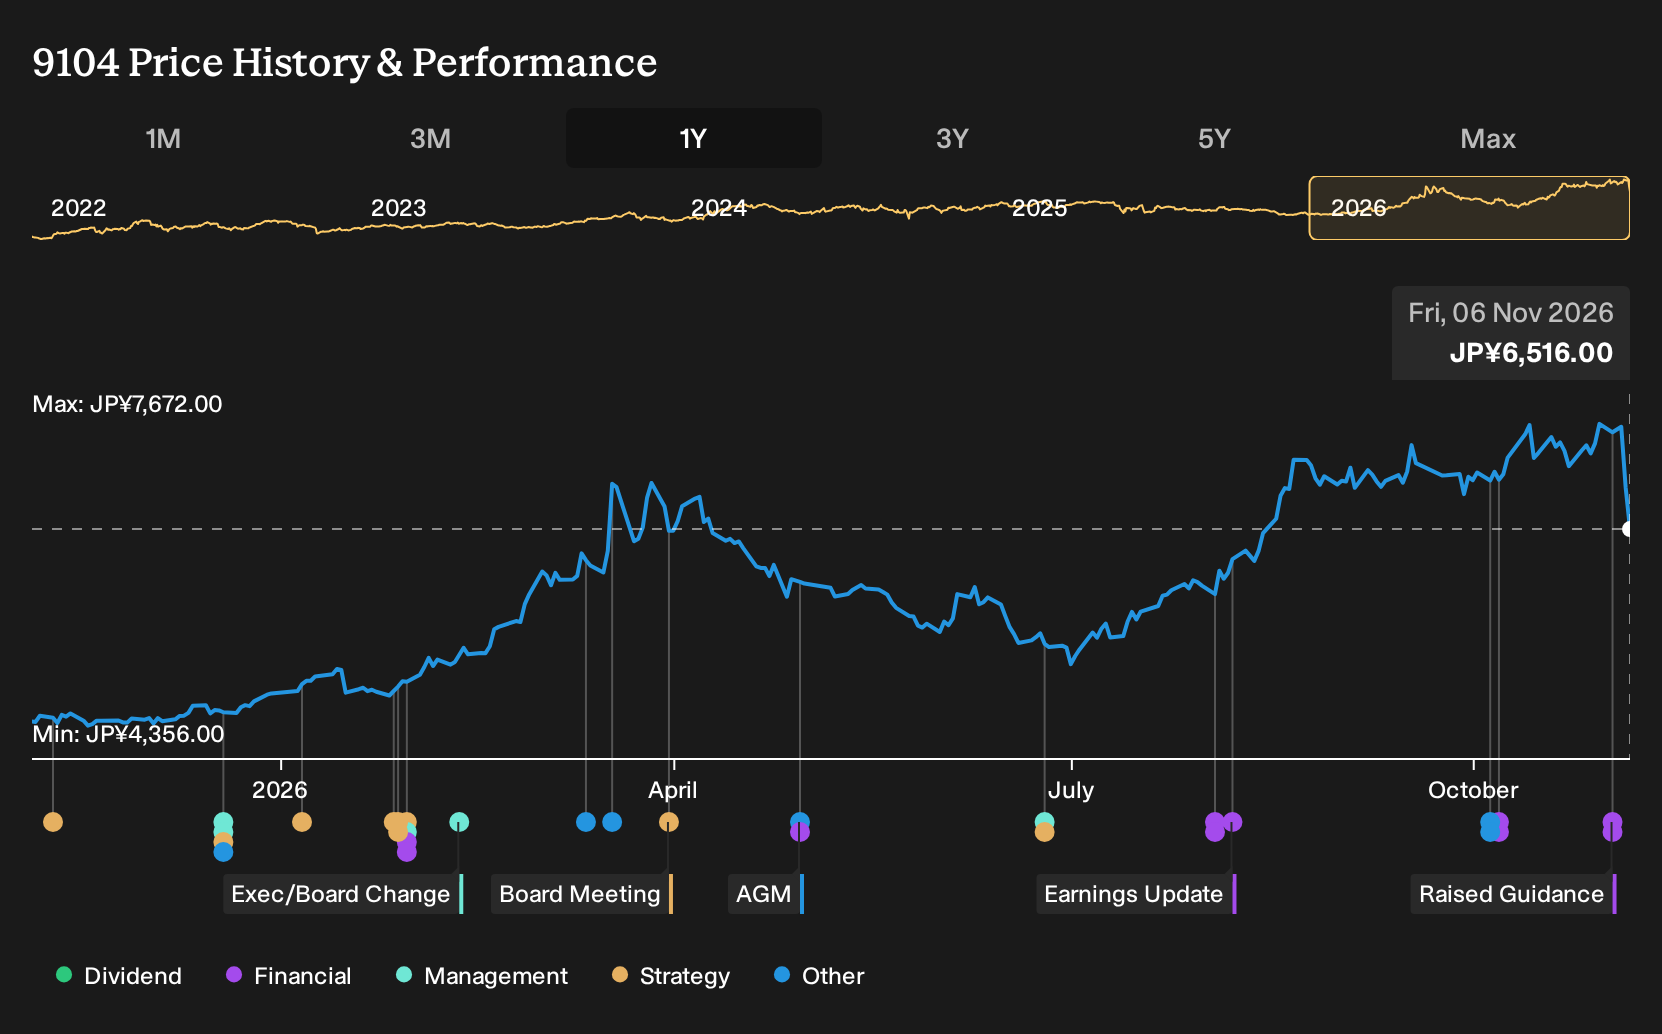
If you were watching Mitsui O.S.K. Lines this year, the headline items were tangible. JERA’s move to lock in four ammonia carriers and new approvals for liquid CO2 vessels showed actual contracts tied to decarbonization cargo, not just PowerPoint slides. Investors who held Mitsui O.S.K. Lines over the past year are up 50.5%, including dividends. If you had been deciding on 6 November 2025, what needed to be believed about those future fuel and CO2 flows to justify buying in?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Mitsui O.S.K. Lines has already moved. See which of 26 high quality undervalued stocks still trade below our estimates.
The Argument You Would Have Been Weighing On Mitsui O.S.K. Lines
The shares cost ¥4,387 at the start of the period, and Mitsui O.S.K. Lines sat between two very different stories about its future. Both were grounded in real numbers and real projects, not just hopes.
The bullish Narrative put Fair Value at ¥5,547. That view hinged on decarbonization-linked logistics paying off, with analysts assuming revenue would edge down 0.8% a year while profit margin settled at 11.6% and the shares traded on a future P/E of 10.2x.
The bearish case saw Fair Value at ¥4,081. That side focused on rising compliance costs and softer trade, with revenue expected to fall 8.8% annually, profit margin to land at 9.6%, and the future P/E assumed at 11.8x.
What The Results Changed For Mitsui O.S.K. Lines
The clearest test came from Mitsui O.S.K. Lines posting Q1 2027 revenue of ¥730,987m and net income of ¥61,056m, with both figures higher than Q1 2026. Net margin moved the other way, slipping from 12.2% to 8.4%. Contract wins in ammonia and liquid CO2 shipping supported the decarbonization story, but softer profitability meant the evidence cut both ways.
The key issue was not just new low carbon cargo; it was how much earnings quality those contracts would support. When you assess another shipping group, compare any growth narrative about cleaner fuels with the reported net margin and consider whether profitability is keeping pace with the project headlines.
What Mitsui O.S.K. Lines’ Price Already Assumes
Today Mitsui O.S.K. Lines trades at ¥6,516, and the selected Narrative’s Fair Value sits below that level. The stock has gained 50.5% over the past year, so the market is already paying up for a larger asset base and the BLUE ACTION 2035 plan.
A buyer now effectively assumes those investments convert into durable earnings and cash returns. The question is how the risks around capital intensity, asset recycling and container volatility in the selected Narrative affect that assumption.
"While management now highlights a shift from an investment first approach to balanced capital allocation, the Phase 2 plan still assumes around ¥2.3t of investment and roughly ¥1t growth in total assets to ¥7.7t by 2030. If follow on and new vessel orders in energy and hybrid shipping underperform, the company could be left with a larger, lower yielding balance sheet that weighs on net margins and depresses future EPS."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Another Route Beyond Mitsui O.S.K. Lines
Watching Mitsui O.S.K. Lines, you may already focus on freight, routes and fuel costs. One step away, a different logistics puzzle appears in plain sight.
Global trade also leans on time definite parcel delivery and intricate warehouse flows. Here, another transport group relies on its air network and proprietary data tools.
This business concentrates on routing software, hub integration and freight reorganisation. It aims to turn small operational changes into steadier internal cash generation.
Its daily shipping data also underpins new digital services for large clients. If those tools gain traction, earnings quality could depend less on pure volume growth.
One Narrative has already put a figure on it. → Uncover the company trading 34% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com