


Devon Energy has climbed 35.6% over the past year, which puts a bright spotlight on one question for anyone looking at the stock today. Is the current share price at US$42.88 adequately supported by the company’s earnings profile, or has sentiment raced ahead of what the business is actually generating per share?
- A 35.6% one year return raises the stakes on whether Devon Energy’s recent share price strength can be squared with its underlying earnings power.
- The planned US$4.2b sale of Eagle Ford assets and management’s focus on high return, long duration properties may reshape future profit mix and the timing of cash flows that support the valuation.
- Your read on Devon Energy is one view; the desks covering it have another. See what analysts think Devon Energy's shares could be worth.
The stock’s next move may depend on whether Devon Energy’s current valuation is justified by the earnings it is producing today and is expected to produce over time.
If you want to test the same earnings question you are asking of Devon Energy across a broader set of opportunities, take a look at 42 high quality undervalued stocks.
Is Devon Energy Still Cheap on Earnings?
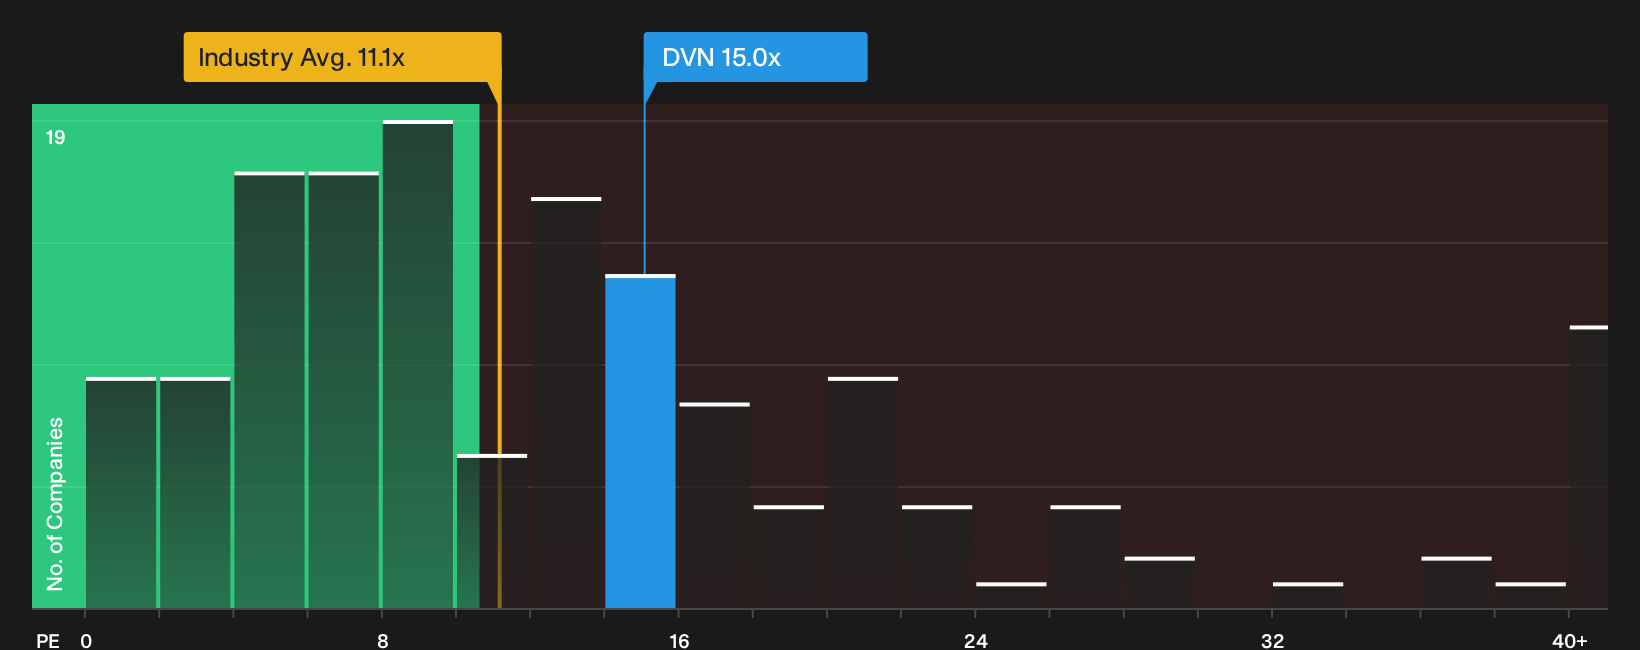
For Devon Energy, the P/E ratio fits neatly because earnings remain a central yardstick for how investors frame the business. The current P/E of 15.0x sits above the Oil and Gas sector average of 11.1x and is also a touch higher than the 14.0x level seen across close peers, so you are paying a richer price for each dollar of Devon’s profits than for the sector overall.
Because the fair multiple implied by Devon Energy’s own profile is above where the stock trades today, the P/E still screens as undervalued on this model even with that premium to peers. Despite the planned US$4.2b Eagle Ford sale sharpening the story around higher return, longer life assets, the market is pricing Devon at a P/E that remains below what this framework suggests would be typical for its risk and cash generation profile. Explore the numbers behind Devon Energy's P/E valuation.
The Devon Energy Narrative: What Would Justify Today's Price?
Narratives on Devon Energy pick up where the valuation question leaves off and spell out which earnings, growth and margin paths would need to hold for the stock to be worth materially more or less than today’s price. All of this is housed on Simply Wall St’s Community page. Each scenario lays out its own fair value assumptions in plain terms rather than pointing to a single P/E or model output, so you can compare those inputs with future results as they are reported.
One of the top community narratives on Devon Energy: 30% undervalued
"Current earnings, cash returns and analyst targets imply the share price still reflects a discount to what Devon Energy could be worth…"
Discover why this Narrative puts Devon Energy at 30% undervalued.
One more Devon Energy check that belongs beside the P/E work
Price multiples tell you what Devon Energy is worth right now, but the projections that analysts publish for the next few years give you a separate yardstick to compare with today’s share price. Explore where analysts expect Devon Energy to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com