


- Sarepta Therapeutics reported Q3 2026 results with revenue of US$381.35 million compared with US$399.36 million a year earlier, while quarterly net loss narrowed to US$28.46 million from US$50.57 million.
- Across the first nine months of 2026, Sarepta Therapeutics moved from a US$301.18 million loss to US$297.61 million of net income, indicating tighter cost control and improved operating efficiency despite lower year-to-date revenue.
- Next, the focus shifts to how Sarepta Therapeutics' improved earnings profile, despite softer sales, could reshape the existing investment narrative.
Scan beyond Sarepta Therapeutics and see how other biopharma players with shifting profit profiles are lining up in the market using our curated 21 high quality undiscovered gems.
Sarepta Therapeutics Investment Narrative Recap
To own Sarepta Therapeutics, you need to believe the Duchenne muscular dystrophy portfolio and newer genetic medicines can support a durable, cash generative rare disease platform despite lumpier sales. The latest quarter showed revenue softer than a year ago but a narrower loss, so the near term story still leans on cost discipline while management works to convert the order book into infusions.
The key near term swing factor remains ELEVIDYS uptake and safety. Any further serious adverse events could slow treatment volumes and pressure earnings. Friction in moving patients from enrollment to infusion, plus reliance on a few high volume centers, still feels like the biggest operational risk in the short run.
The fresh Q3 2026 release is the most relevant update for this story. Sarepta Therapeutics reported US$381.35 million of quarterly revenue and a loss of US$28.46 million. The first nine months of 2026 shifted from a US$301.18 million loss to US$297.61 million of net income. That pivot reflects tighter cost control rather than top line expansion.
Those numbers feed directly into the existing catalyst map. ELEVIDYS risk management work, the siRNA programs in FSHD and DM1, and the potential conversion of AMONDYS 45 and VYONDYS 53 to traditional approvals still anchor the medium term thesis. The new earnings figures simply show how much cushion Sarepta Therapeutics currently has to keep funding that pipeline while it works through near term revenue headwinds and operational bottlenecks.
Sarepta Therapeutics' current analyst narrative points to revenue of US$1.3b and earnings of US$36.4 million by 2029, based on a forecast 13.0% yearly revenue decline and an earnings move of roughly US$173 million from a loss of US$136.7 million today to the projected profit level.
Uncover why Sarepta Therapeutics' fair value indicates a 24% potential upside to its current price, which could narrow quickly.
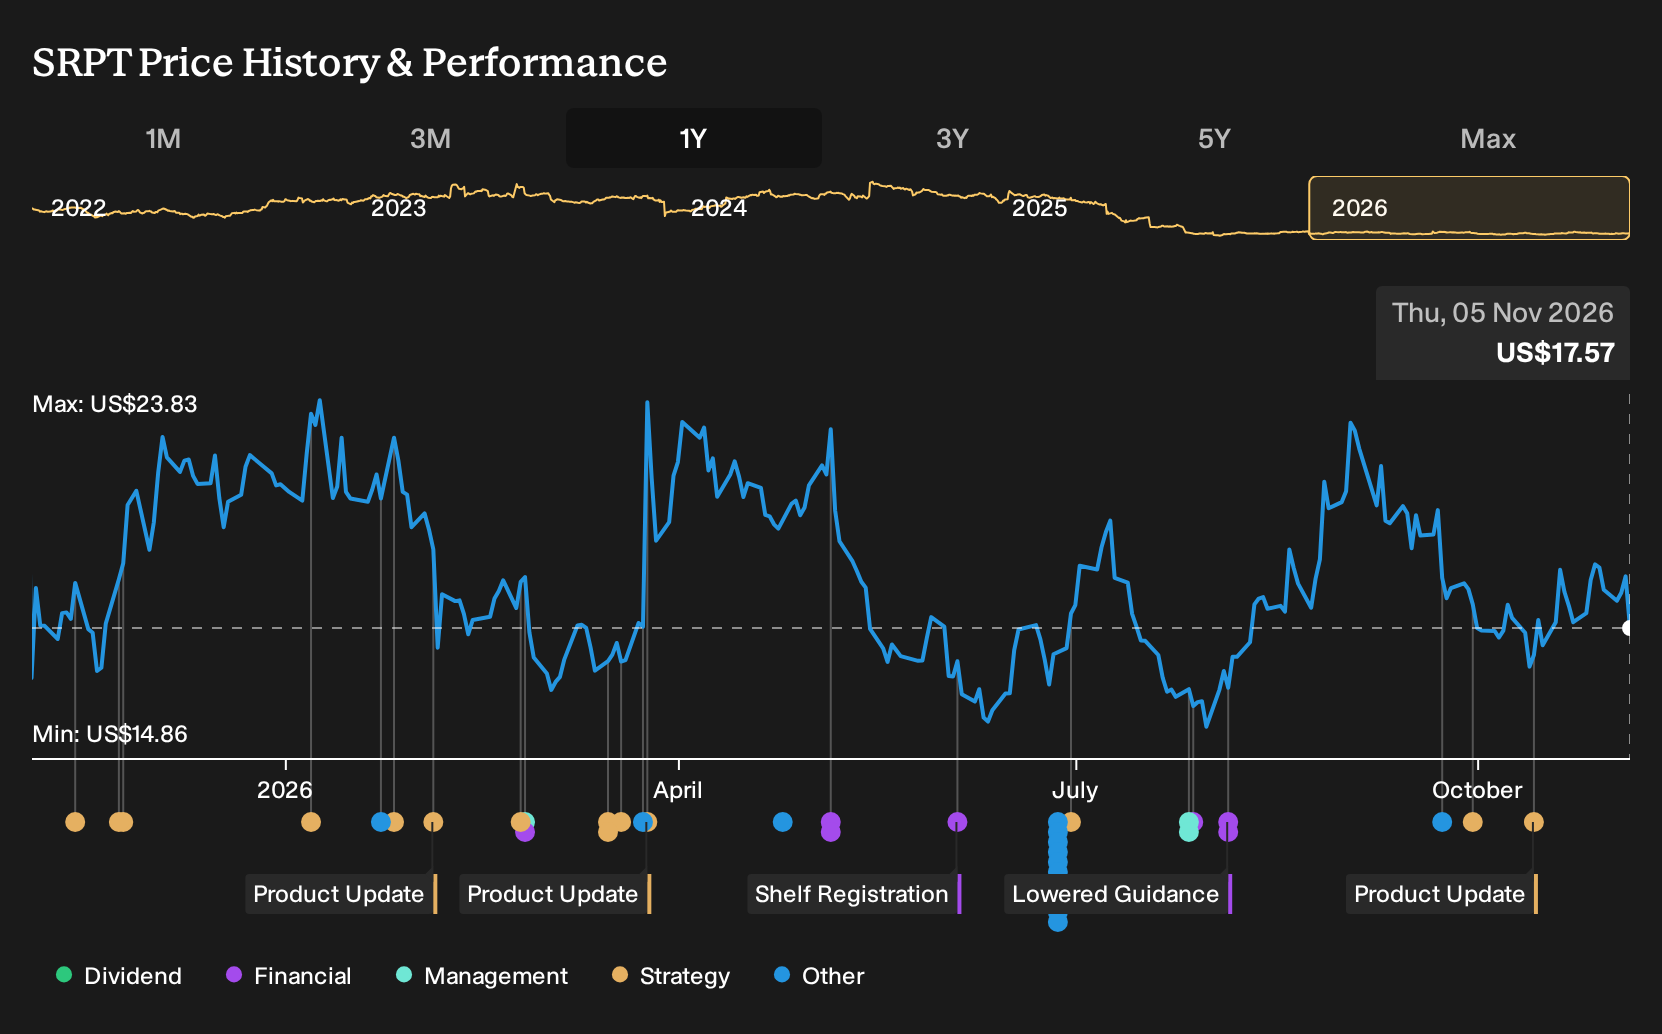
Exploring Other Perspectives
For Sarepta Therapeutics, the bullish twist is ELEVIDYS. The most optimistic analysts were banking on Duchenne gene therapy helping drive revenue toward about US$1.4b and earnings near US$159.6 million by 2029, far above consensus. Those views were set before this Q3 2026 update, so opinions may evolve. Explore the full range of forecasts before deciding what you think.
Explore 3 other Sarepta Therapeutics fair value estimates, including one that suggests up to 1309% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sarepta Therapeutics research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sarepta Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sarepta Therapeutics' overall financial health at a glance.
Looking for more investment ideas beyond Sarepta Therapeutics?
If Sarepta Therapeutics has sharpened your view on risk, reward, and timing, it can be useful to line that up against other opportunities. Use the Simply Wall St Screener to filter for traits that match your own tolerance for volatility, income needs, or balance sheet strength, and build a shortlist that actually fits how you invest.
- For investors who want potential upside in companies the market has not fully focused on yet, start with a curated group of 21 high quality undiscovered gems.
- If capital preservation sits high on your list, compare Sarepta Therapeutics with a pool of 32 resilient stocks with low risk scores that score well on financial stability.
- Income focused readers can benchmark Sarepta Therapeutics against a selection of 6 dividend fortresses that pair higher yields with an emphasis on resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com