


Global stocks recently sold off after worries about a slowdown in AI spending and fresh questions over how tightly regulators might oversee the sector. That shift has pushed many investors to look again at solid United Kingdom businesses where analysts still see strong earnings growth potential and balance sheets that pass basic health checks. This article highlights three such stocks picked from our high growth potential filter.
The three stocks highlighted here offer a compelling starting point if you want exposure to healthier high growth potential businesses where analysts still project robust earnings expansion and acceptable balance sheets. However, if you want the pick of this theme, these 8 best high growth potential stocks are the best of the best.
Saga (LSE:SAGA)
Saga is tightly linked to the Healthy high growth potential theme through its cruise holidays and insurance lines. Analysts see earnings as the key driver rather than sheer scale, and it has just moved back into profit with recovery momentum under close watch.
Saga focuses on UK over-50s through insurance broking and travel, with around £538 million from cruises and holidays and £144 million from insurance broking, plus smaller other services. It carries a market value of about £1.26b.
For this screen, Saga matters because the Insurance and Travel divisions give it a clear route to earnings growth if execution keeps pace with expectations. This is particularly important as the business rebuilds around higher value customers and more profitable products.
Although Saga highlights strong forward bookings in Ocean Cruise, with booked load factors into future years and higher per diems, the plan to keep adding value through onboard investment raises the hurdle for sustaining price led growth without eroding incremental margin if demand normalises. This could pressure operating margin expansion and profit growth.
The real swing factor is whether one pressure point in the model quietly reshapes how much of that expected earnings trajectory actually reaches shareholders.
If that pressure point interests you, read the full narrative for Saga to see how Saga's earnings path could be reshaped or quietly accelerated beyond headline bookings.

Burberry Group (LSE:BRBY)
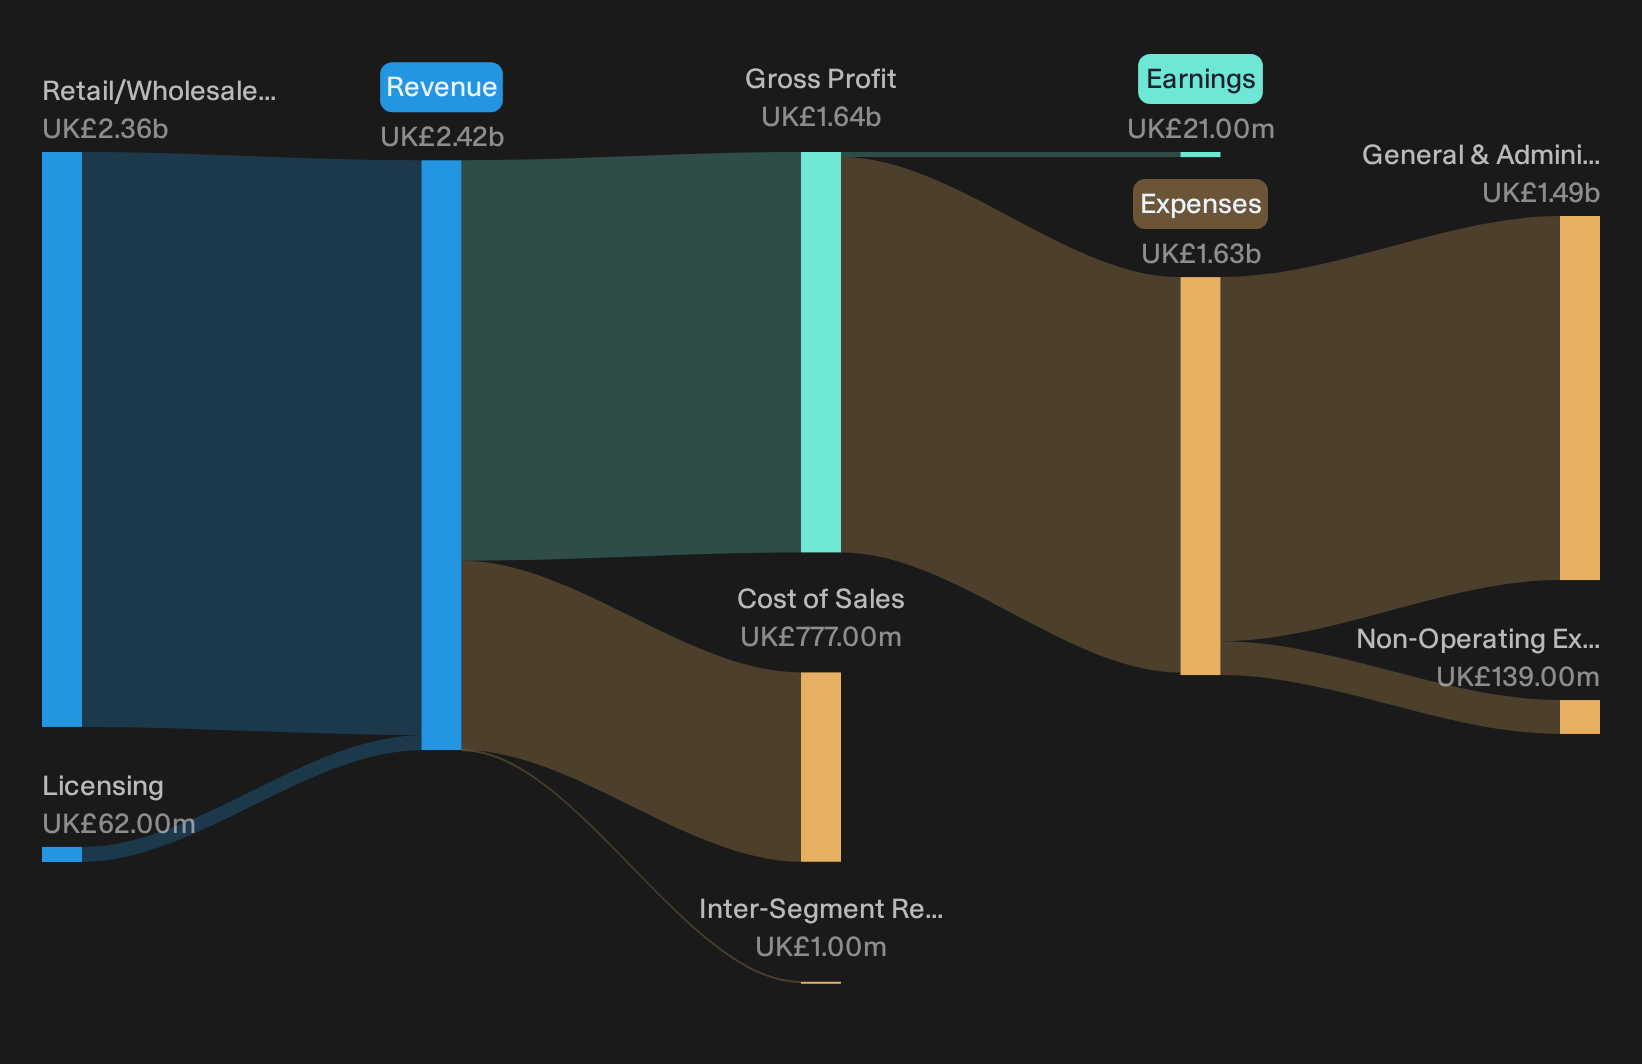
Burberry Group is a British luxury house focused on apparel, accessories and beauty. Its earnings story in this screener is tied mainly to the Retail/Wholesale arm that leans heavily on Asia-Pacific shoppers and digital commerce. That primary unit produced about £2.36b of revenue, compared with £62 million from Licensing, on a market value of roughly £4.0b.
Burberry Group sits in this Healthy high growth potential basket because the Retail/Wholesale operation links a heritage label with an earnings story built around full-price sales, Asia-Pacific demand and a steadily more important online channel.
The Burberry Forward focus on brand elevation and a Timeless British Luxury positioning is now linked with double-digit growth in hero categories such as outerwear and scarves, along with higher full-price sell-through, which can support further revenue growth and gross margin improvement.
The real test for Burberry Group is how far that positioning can stretch earnings if one less visible pressure on margins and cash generation does not break.
If that margin pressure is what you are weighing up, read the full narrative for Burberry Group to see whether Burberry Group's brand push is quietly decoupling profits from headline sales.
Airtel Africa (LSE:AAF)
Airtel Africa blends a traditional mobile network with a fast growing Airtel Money arm, which ties it directly into the Healthy high growth potential theme. Mobile services across Nigeria, East Africa and Francophone Africa generate around $7.6b of revenue, with Mobile Money at about $1.6b, and the group carries a market value near £10.5b.
Airtel Africa gives you a way into the growth of telecoms and fintech across multiple African markets, with mobile money as the clearest link to the earnings focused theme here, while the larger voice and data units still provide the bulk of cash generation.
The combination of continued strong population growth, a young demographic profile, and currently low mobile and data penetration rates across Airtel Africa's markets provides a long multi-year runway for organic customer expansion and ARPU growth, directly supporting sustained increases in revenue and EBITDA.
The real test is what happens to that earnings runway if one funding and regulation sensitive pressure point changes the path of future margins.
If that hinges on your view of this funding and regulation pressure point, read the full narrative for Airtel Africa to see whether Airtel Africa's growth runway is quietly accelerating.

Seeking Fresh Alternatives Before They Fly?
Markets move fast and the best breakout stories rarely stay under the radar for long. Scan these fresh ideas before momentum gets fully caught by the crowd and consider them while they are still emerging.
- Spot sturdy income opportunities early and check out the 4 dividend fortresses that could help keep cash flows coming while prices are still settling.
- Hunt for resilient businesses with real balance sheet strength using the curated list of solid balance sheet and fundamentals (9 results) that screens for quality before it is fully reflected in prices.
- Review the hand picked 88 robotics and automation stocks to explore the next automation wave while valuations and expectations are still resetting.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com