


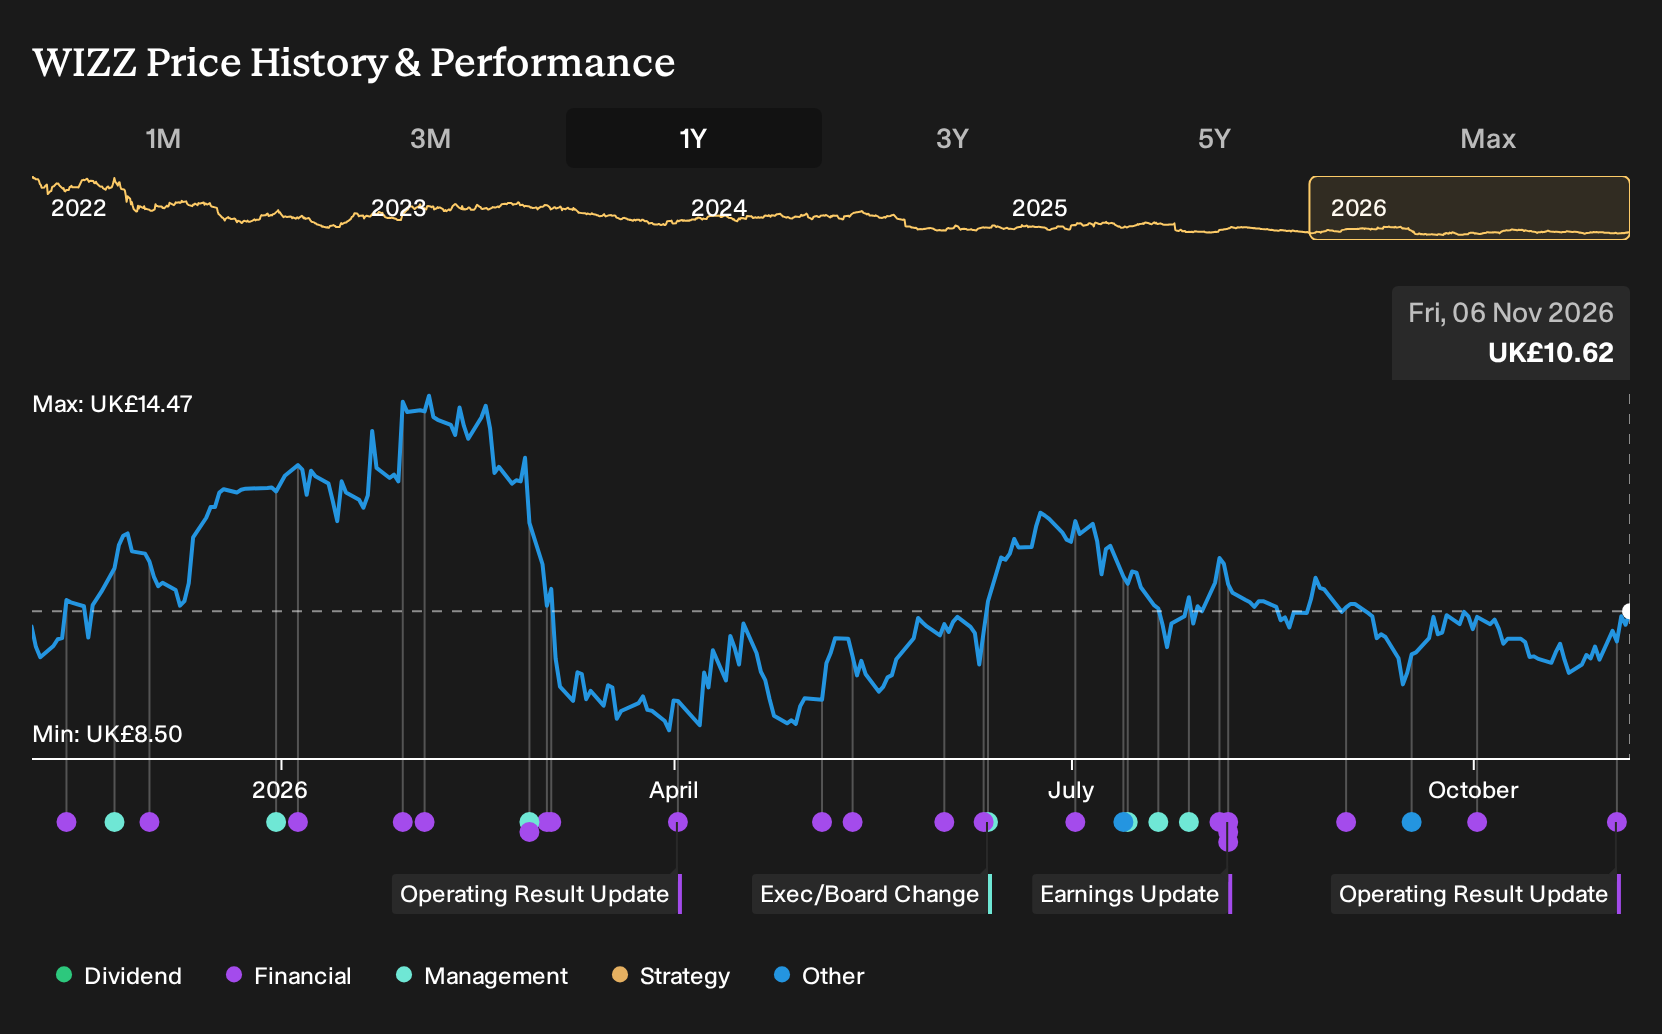
- Wizz Air Holdings reported October 2026 traffic data showing 8,361,193 seats and 7,624,319 passengers for the month, with a 91.2% load factor, alongside rolling twelve month figures of 88,712,795 seats, 80,588,509 passengers and a 90.8% load factor, all compared with the prior year.
- The airline's passenger volumes and capacity over both the month and the past year moved ahead of last year's levels, while load factors edged slightly lower. This highlights a focus on scaling the network even as seat utilisation efficiency tightens.
- We will now examine how Wizz Air Holdings' investment narrative might shift given the strong passenger growth alongside the slightly lower load factor.
Wizz Air Holdings Investment Narrative Recap
For an investor in Wizz Air Holdings, the core belief is that the low cost model can be scaled across Europe while unit costs are kept under tight control. The latest traffic release shows capacity and passenger volumes ahead of last year, with a slightly softer load factor. This keeps the focus firmly on whether the airline can fill a larger fleet without relying on discounting.
In the near term, the key catalyst is operational execution as grounded aircraft return, older jets leave the fleet and high network churn is managed. The main risk is that moderated growth, elevated maintenance and depreciation, and a softer load factor combine to keep unit economics tight, without enough offset from higher quality routes.
The October 2026 traffic update matters most when set against Wizz Air Holdings' broader plan to unground GTF powered aircraft and transition toward a more A321neo heavy fleet. Higher capacity and passenger numbers show that the platform can carry more travellers. However, the dip in load factor keeps attention on how efficiently that extra seating is used.
Regarding catalysts, rolling twelve month figures above the prior year support the idea that redeploying aircraft into denser Central and Eastern European and Italian routes, plus new domestic flying in Spain, can build scale. The risk side sits with Wizz Air Holdings' negative net margin, high net debt relative to EBITDA and guidance for elevated maintenance costs through FY27. Together, these make consistent route profitability and cost control the elements to watch.
Wizz Air Holdings' narrative projects €9.0b revenue and €287.8m earnings by 2029. This assumes 16.0% yearly revenue growth and an earnings swing of about €523.5m from current earnings of a €235.7m loss to the 2029 consensus forecast.
Uncover why Wizz Air Holdings' fair value is essentially aligned with its current price.
Exploring Other Perspectives
Some of the most optimistic analysts lean on the capacity growth moderation as a positive, arguing Wizz Air Holdings could push earnings toward about €639.6m and revenue toward €10.1b by 2029. You can compare that far more upbeat path with the latest traffic softness and decide whether this new data might shift those expectations.
Explore 4 other Wizz Air Holdings fair value estimates, including one that suggests as much as 86% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Wizz Air Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Wizz Air Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Wizz Air Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Wizz Air Holdings?
If the Wizz Air Holdings story has sharpened your thinking, use that same lens on a wider field of opportunities with the Simply Wall St Screener. Filter for the traits you care about most and build a shortlist that actually matches your risk tolerance and goals.
- If you prefer quality and valuation discipline together rather than chasing headlines, then start with a focused group of 15 high quality undervalued stocks that already combine strong fundamentals with sensible pricing.
- If resilience and balance sheet strength sit at the top of your checklist, narrow your hunt to a curated list of solid balance sheet and fundamentals (9 results) that can help you stress test defensiveness.
- For investors hunting for underfollowed opportunities before they hit the mainstream, scan a hand picked pool of 5 high quality undiscovered gems that pair robust metrics with lighter market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com