


Global stocks have just taken a sharp hit as worries about an AI slowdown ripple through markets, dragging the FTSE 100 lower and souring sentiment around high profile tech giants. That kind of broad selloff often pushes attention away from smaller, profitable UK shares that quietly keep their finances in order. This article highlights three lower priced British stocks screened for stronger balance sheets and healthier cash profiles.
The three stocks highlighted here offer a compelling starting point if you want exposure to lower risk early stage businesses with tighter financial discipline. However, if you want the pick of this theme, these 18 elite penny stocks are the best of the best.
Ashmore Group (LSE:ASHM)
Ashmore Group gives this screener direct access to emerging market penny stock exposure, but through a London based asset manager that aims to keep its own finances relatively robust while hunting for smaller, higher potential issuers for clients.
Ashmore Group plc manages emerging market equity, fixed income and alternatives portfolios, generating about £139 million from investment management services, and carries a market value of roughly £1.36 billion.
"The renewed net inflow phase into emerging markets, with Ashmore Group reporting FY26 net inflows of $2.7b alongside rising subscriptions and lower redemptions, creates scope for a longer period of higher fee earning AuM than consensus typically models."
What matters next is how one quiet shift inside that fee mix shapes future profitability and keeps the penny stock exposure feeling financially fit.
To see how that shift could accelerate or cap Ashmore Group's earnings power, read the full narrative for Ashmore Group for the full risk and reward story.

IntegraFin Holdings (LSE:IHP)
IntegraFin Holdings brings the Financially Fit Penny Stocks idea into the plumbing of the market, using its Transact wrap platform to help advisers manage smaller client portfolios, including penny stock positions, inside tax efficient structures rather than chasing individual high risk issuers.
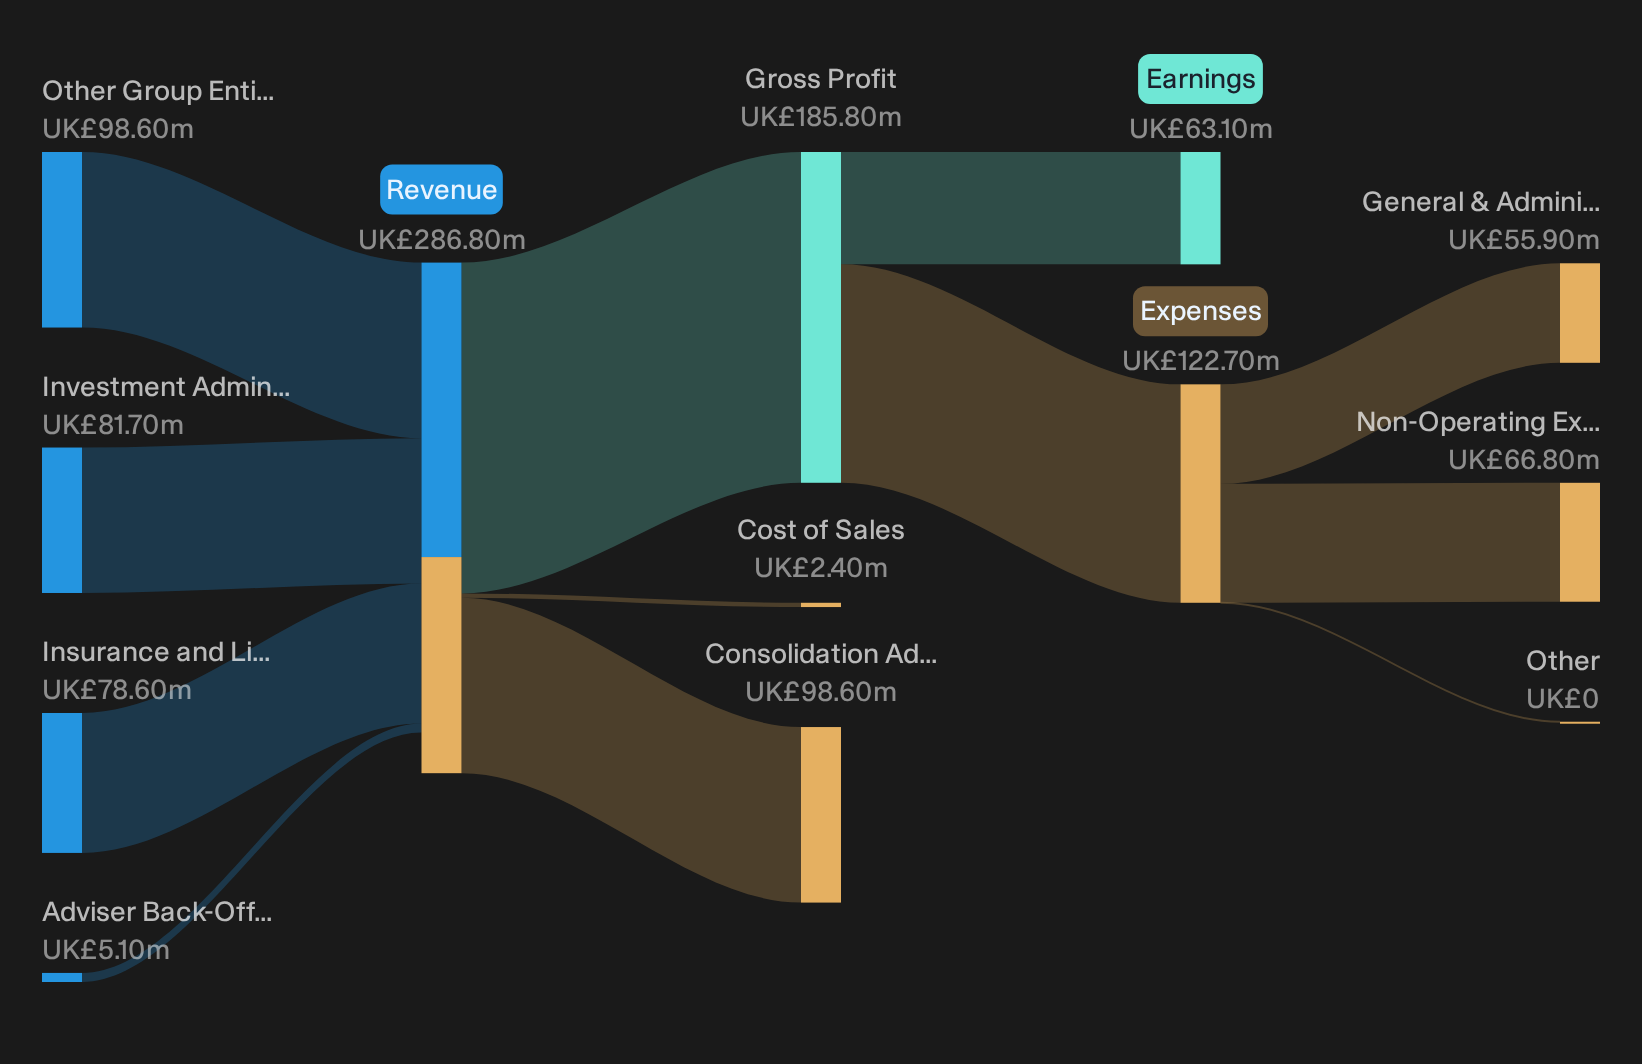
IntegraFin runs the Transact platform and adviser software business that underpins many UK wealth managers, generating about £81.7 million from Investment Administration Services, £78.6 million from Insurance and Life Assurance, and £5.1 million from Adviser Back-Office Technology, with a market value of roughly £1.26 billion.
"Transact net inflows and client growth remain a live driver, with recent periods showing record gross inflows and funds under direction above £80b, which expands IntegraFin Holdings’ recurring fee base and supports revenue."
For investors, an important consideration now is how a quiet shift in the cost base may shape future margins if that growth engine continues to operate at current levels.
If that cost base inflects, the full narrative for IntegraFin Holdings shows how IntegraFin Holdings’ margins, cash generation and risk profile could be shifting in ways the headline inflow story does not fully reveal.
Currys (LSE:CURY)
Currys plugs the Financially Fit Penny Stocks theme into everyday life, with budget tech sales and repair services giving you small-ticket exposure across its Currys and Elkjøp stores, supported by £5.5b from UK & Ireland operations, £3.8b from the Nordics and a market value near £1.45b.
Currys links penny-stock-style budget gadgets and accessories with an omnichannel model, then layers on services and protection that can reshape how cash flows through the business.
"Expansion of higher margin recurring services such as credit, installations, connectivity and repair, which now account for over 30% of UK revenue and have been growing faster than product sales, can affect Currys group revenue quality and EBIT margins as more customers shift into these offers."
What happens to that picture if one quiet cost pressure starts to bite into the room Currys has created on margins?
If that squeeze is already starting, read the full narrative for Currys to see whether Currys’ recurring services are masking risk or quietly accelerating a higher quality earnings mix.

Seeking Alternatives Before The Crowd Moves
Market momentum shifts fast and fresh opportunities do not stay under the radar for long. To spot potential breakouts and avoid getting caught chasing stocks already flying higher, it can help to act early.
- Look for resilient cash generators before momentum screens pick them up by scanning the 15 high quality undervalued stocks while it still highlights ideas most investors have not crowded into yet.
- Participate in the backbone of the AI build out by using the 53 AI infrastructure stocks to filter for businesses involved with the chips, data pipes and energy behind the headlines.
- Prepare for a potential power upgrade cycle by screening the 40 power grid technology and infrastructure stocks and focusing on companies tied to grid technology that others may notice only after prices have already moved.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com