


DraftKings (DKNG) stock tumbled on Nov. 6 after investors reacted negatively to the sports betting giant’s first formal outlook for 2027, which came in below Wall Street expectations. Investors bailed on DKNG as management lowered its current-year guidance as well, citing substantially higher investment in DraftKings Predictions — the firm’s recently launched event-contracts platform.
Following today’s decline, DraftKings shares are trading at about half their price at the start of this year.
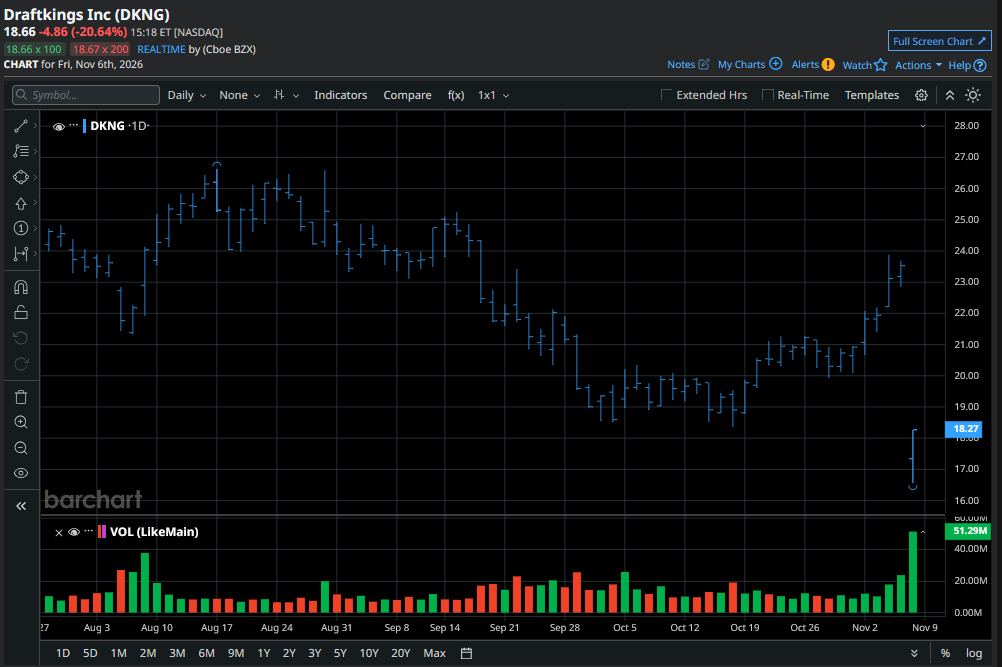
What Triggered the Selloff in DKNG Stock Today
While DraftKings recorded solid user growth (monthly unique payers up 13%) for Q3, investors were unsettled by the cost of the company’s aggressive push into prediction markets. Management now expects to invest up to $700 million in that business during 2026, more than double its initial spending plan.
That increased investment prompted DKNG to trim its 2026 adjusted EBITDA guidance to a range of $175 million to $275 million, well below its previous forecast of at least $700 million.
The bigger concern for investors, however, was the 2027 profitability outlook. DraftKings said adjusted EBITDA could reach $900 million next year, but that also fell shy of the consensus estimate set at $1.12 billion. These numbers suggest competition in prediction markets and customer acquisition costs may remain elevated longer than investors had anticipated, raising questions about the pace of future margin expansion.
Truist Remains Bullish on DraftKings Shares
Despite today’s selloff, some Wall Street firms remain constructive on DKNG shares’ longer-term prospects. Truist reiterated its “Buy” rating on the company this morning, arguing it’s making a deliberate decision to prioritize growth opportunities in prediction markets over near-term profitability.
Management expects the segment to generate between $650 million and $750 million in revenue during 2027 and has highlighted strong customer engagement metrics, including 1.6 million users having interacted with the product year-to-date.
DraftKings has a history of gaining nearly 9.5% on average in November, a seasonal pattern that makes it even more attractive in the near term.
How Wall Street Recommends Playing DraftKings
Other Wall Street analysts haven’t thrown in the towel on DraftKings stock, either.
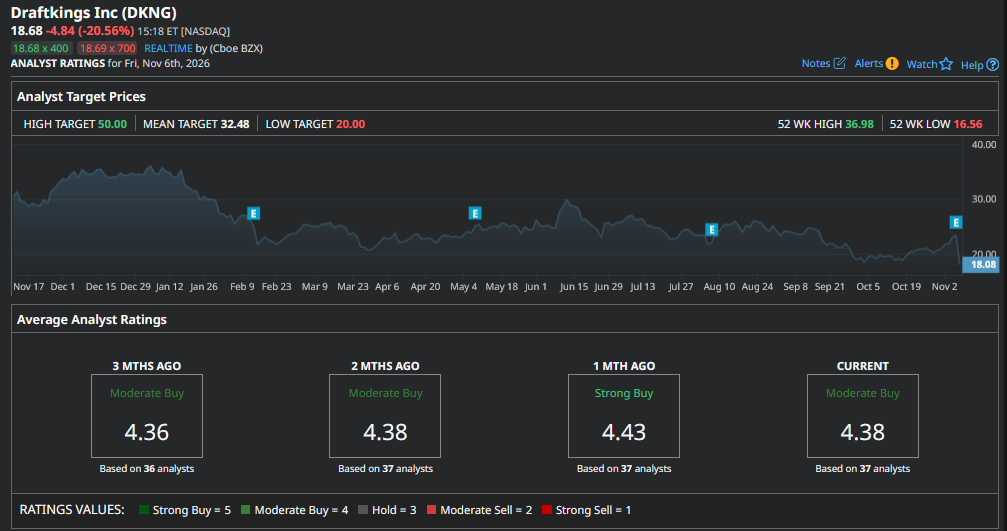
The consensus rating on DKNG remains at “Moderate Buy,” with the mean price target of about $32 indicating massive upside potential from here.
On the date of publication, Wajeeh Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.