


Premium Brands Holdings: Why Q3 2026 Caught Investors’ Attention
Premium Brands Holdings (TSX:PBH) has drawn fresh attention after reporting record third quarter sales, a swing back to positive net income, and launching a new share buyback alongside its latest dividend declaration.
Recent trading shows that investors are reacting to these updates in real time, with a 1-day share price return of 2.90% and a 7-day gain of 5.55%. However, the year-to-date share price is still down 24.87% and the 5-year total shareholder return has declined 31.29%. This suggests that interest in Premium Brands Holdings has increased in the short term while its longer-term record remains weak.
Scan for other Premium Brands Holdings style recoveries by checking companies on our 6 high quality undervalued stocks that pair recent earnings momentum with longer term share price weakness.
Premium Brands Holdings just posted a sharp earnings rebound and the share price has started to move, yet the long term chart still shows heavy damage. Is this an early entry point, or a rally that rewards patience?
Most Popular Narrative: 31% Undervalued
Premium Brands Holdings last closed at CA$76.97, while the most followed narrative pegs fair value at CA$112.25 using a 6.57% discount rate. That gap puts the focus squarely on whether the new capacity and cash generation story can support a higher valuation over time.
The completion of Premium Brands Holdings' roughly $1.1b capital investment program, with only about $41.6m left to spend and over $2b of new sales capacity available, provides room for additional volume from existing and new programs, which can support revenue and EBITDA as utilization improves.
See why 17 investors see Premium Brands Holdings as 31% undervalued.
Result: Fair Value of CA$112.25 (UNDERVALUED)
However, the Premium Brands Holdings story still hinges on two pressure points: large new U.S. launches could keep ramping unevenly, and asset sales might slip or underdeliver, which would strain the deleveraging script.
Find out about the key risks to this Premium Brands Holdings narrative.
Another View: Premium Brands Holdings Through The P/E Lens
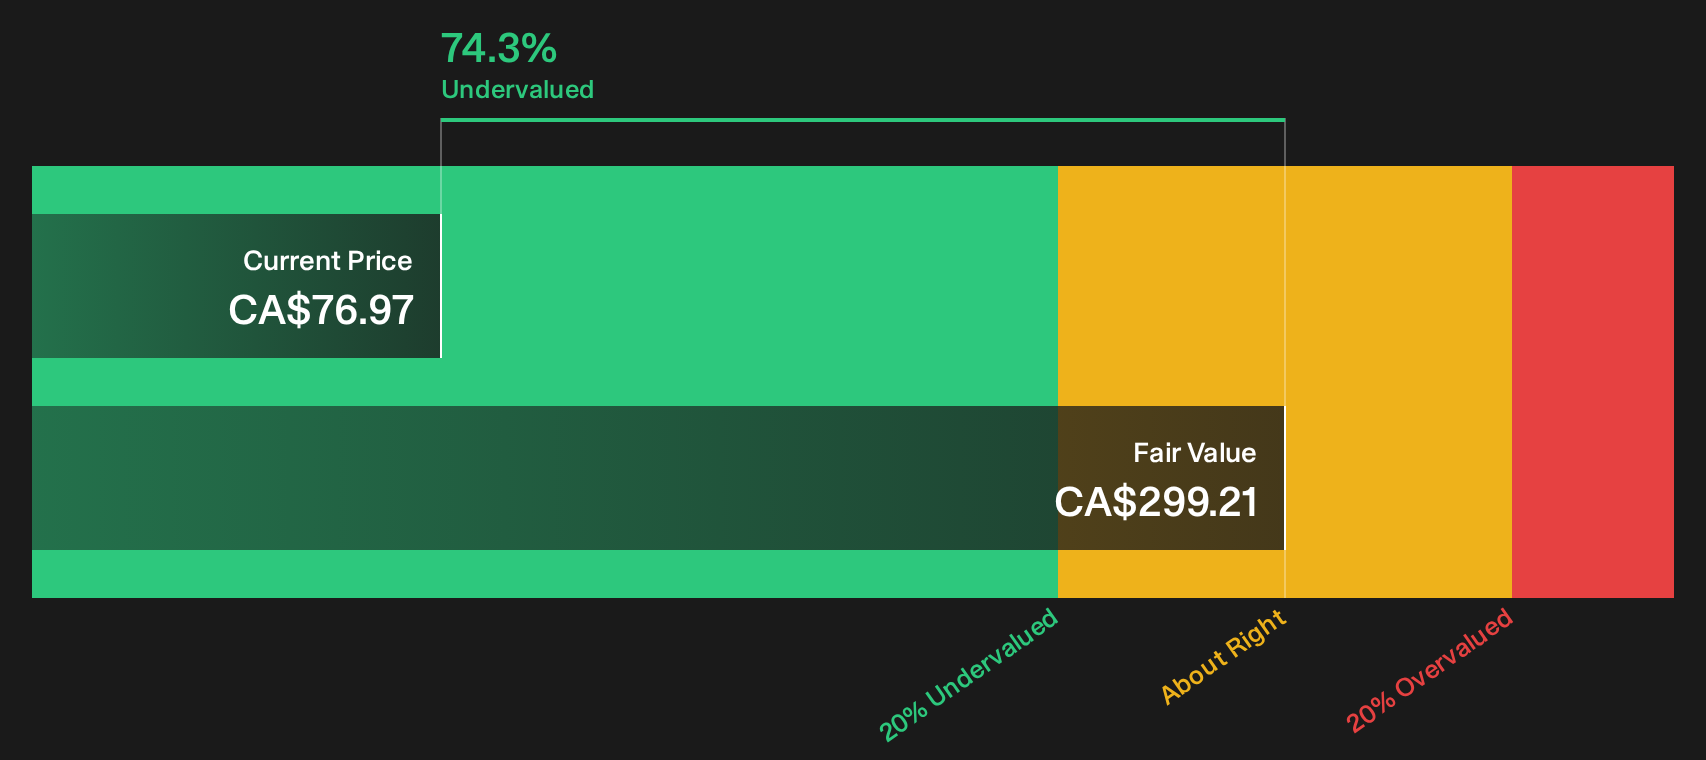
The SWS DCF workup suggests Premium Brands Holdings is trading at a steep discount to an estimated future cash flow value of CA$299.21 per share, which flags upside in that model. Yet on a plain P/E basis, PBH trades at 56.9x, far above both North American food peers at 18.7x and its own fair ratio of 67.5x. Is the market already paying up for the story, or is the DCF capturing something the multiples are missing?
Look into how the SWS DCF model arrives at its fair value: Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals surround this Premium Brands Holdings story, so move fast, pull up the full breakdown, and weigh the 4 key rewards and 4 important warning signs for yourself.
Looking For More Investment Ideas Beyond Premium Brands Holdings?
If Premium Brands Holdings has your attention, do not stop here. Fresh ideas and different risk profiles could help round out your watchlist intelligently.
- Target higher potential upside with carefully selected smaller companies by scanning the 18 elite penny stocks with strong financials. These securities clear strict financial quality hurdles.
- Strengthen your offense with candidates priced below their estimated worth by reviewing the 6 high quality undervalued stocks. These opportunities pair quality fundamentals with discounted valuations.
- Reinforce your defensive side by focusing on balance sheets that look built to endure using the list of solid balance sheet and fundamentals (5 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com