


Sacyr (BME:SCYR) has drawn fresh attention after reporting nine month 2026 sales of €3,776.92 million and net income of €116.34 million, alongside newly awarded investment grade credit ratings and additional infrastructure concessions.
Despite the stronger nine month figures and new concessions, Sacyr’s share price at €4.046 has moved unevenly. The 30 day share price return of 2.53% contrasts with a 90 day decline of 11.58%, while a 1 year total shareholder return of 12.98% and a 5 year total shareholder return of 115.45% indicate momentum that has built over a longer horizon.
Scan for opportunities similar to Sacyr's concession driven story and credit rating upgrade by checking our curated list of list of solid balance sheet and fundamentals (192 results).
Sacyr now combines a concession-heavy business and fresh investment grade status with a share price that has slipped over the past 90 days. Does that combination still leave the stock attractively valued today?
Most Popular Narrative: 19% Undervalued
Sacyr's most followed valuation narrative pegs fair value at €4.98 per share, above the recent close at €4.05. This frames the current pullback against a still supportive long term story built on concessions and recurring cash flow.
The significant growth and robust pipeline in recurring, long-duration concession assets, highlighted by contract wins in high-growth regions (e.g., U.S., Chile, Italy) and a record €10.8bn backlog, position Sacyr to benefit from a global surge in infrastructure investment and urbanization. This supports higher future revenue and more predictable, resilient cash flows.
See why 6 investors see Sacyr as 19% undervalued.
Result: Fair Value of €4.98 (UNDERVALUED)
Still, Sacyr’s heavy project finance debt of €6.891b and sensitivity to currency swings, including a €213m FX hit, could quickly weaken that upbeat narrative.
Find out about the key risks to this Sacyr narrative.
Another View: Sacyr On Richer Earnings Multiples
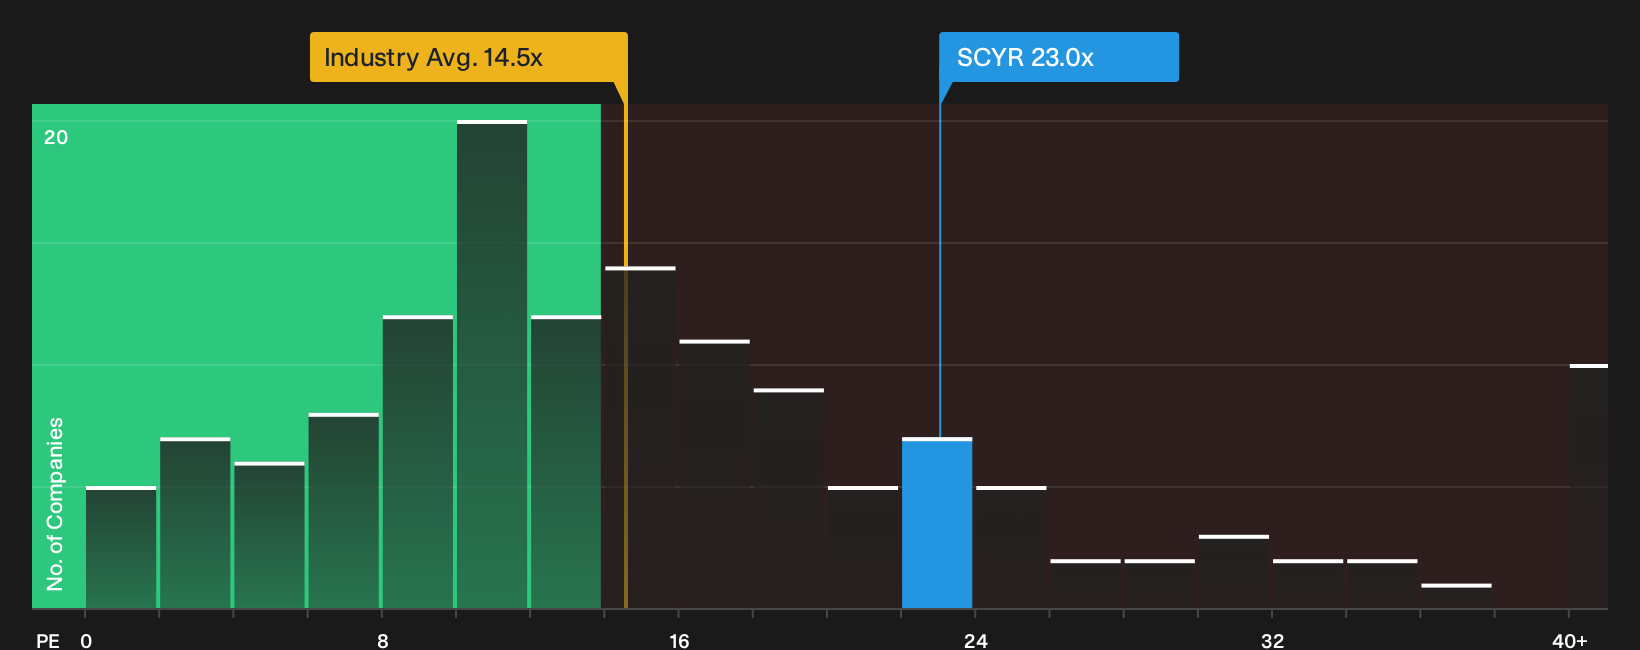
The first narrative paints Sacyr as about 19% undervalued, yet the earnings multiple tells a tighter story. The stock trades on a P/E of 23x, compared with 14.5x for the wider European construction group and a fair ratio of 18.3x that the market could move toward over time.
That gap suggests investors are already paying a premium for Sacyr's concession model, which could limit upside if sentiment cools or earnings fall short. It raises a practical question for you: is this a margin of safety, or a valuation that leaves less room for error?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Sacyr's valuation and risk profile can feel confusing. Move quickly, pull up the underlying metrics, and weigh both the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Sacyr?
You do not need to stop at Sacyr. Use the Simply Wall Street Screener to line up fresh ideas before the next opportunity slips past.
- Target potential mispricings by scanning a 227 high quality undervalued stocks that pairs strong fundamentals with prices that may not fully reflect underlying business quality.
- Strengthen your portfolio’s resilience by focusing on a 213 resilient stocks with low risk scores highlighted for steadier balance sheets and lower overall risk scores.
- Get ahead of the crowd by tracking a 589 high quality undiscovered gems that combines solid metrics with relatively limited market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com