


North West (TSX:NWC) is back in focus after recent updates showed the retailer tackling higher freight and wage costs through its Next 100 productivity programme, while reporting higher sales, same-store sales, and a September 2026 dividend increase.
Recent trading reflects that story. North West’s share price has climbed to CA$59.46, with a 30 day share price return of 9.32%. This builds on a 21.20% year to date share price gain and a 5 year total shareholder return of 102.92%.
Scan other retailers showing similar operational resilience to North West by reviewing our curated list of 6 high quality undervalued stocks.
After that kind of run, the question is simple: Does North West at about CA$59 still offer an appealing balance of risk and potential reward, or has the easy part of the rerating already played out?
Preferred P/E of 19.9x: Is it justified?
For a stock that has already moved, valuation is where opinions usually split. North West now trades on a P/E of 19.9x, which puts a clear price tag on every dollar of earnings the retailer currently produces.
The P/E multiple simply compares the share price to earnings per share. For a retailer like North West, it is a quick way to see how much investors are paying for the company’s profit engine relative to both its own history and other consumer chains.
At 19.9x earnings, the business is described as slightly expensive against the wider North American consumer retail group on 19.8x, but as good value against a closer peer set that sits around 34.4x. That combination suggests the market is not paying a bargain price for the ticker, yet the stock is also not priced like the higher multiple retailers that carry richer expectations baked into every share.
Against the industry reference point, the message is blunt. North West trades almost in line with the broader consumer retail cohort, yet at a sizeable discount to its more direct peers where valuations stretch to roughly one third higher P/E levels.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 19.9x (ABOUT RIGHT)
Still, the story can break if freight and wage pressures flare up again, or if consumer demand in North West’s remote markets turns more cautious.
Find out about the key risks to this North West narrative.
Another view on North West’s value
The P/E of 19.9x paints North West as roughly in line with the wider consumer retail group, but our DCF model points in a very different direction. On that measure, the stock at CA$59.46 is described as trading about 71.5% below an estimated future cash flow value of CA$208.82.
That is a wide gap. For you as an investor, the key question is whether the cash flow assumptions behind that SWS DCF model are realistic enough to matter, or simply too generous to rely on.
Look into how the SWS DCF model arrives at its fair value.
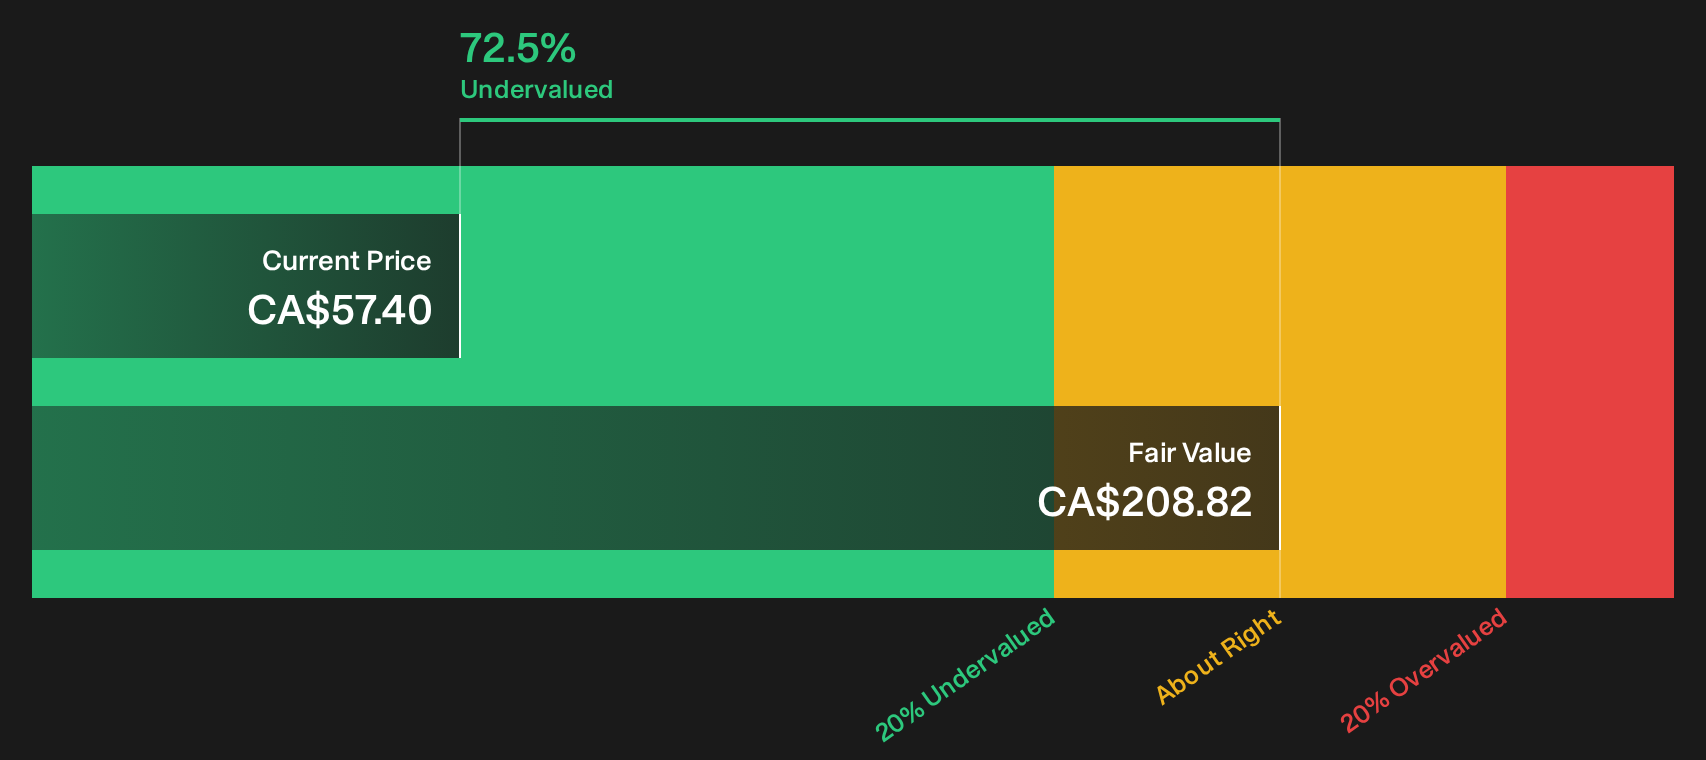
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out North West for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the North West story so far appears finely balanced between promise and pressure, consider acting promptly and evaluating both aspects for yourself by reviewing the full breakdown of 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond North West?
If North West has sharpened your focus, keep that momentum going by lining up a few more high conviction candidates using structured filters instead of guesswork.
- Target resilient compounders by reviewing a 9 resilient stocks with low risk scores that can help you spot businesses with more stable profiles when markets turn choppy.
- Hunt for quality at a discount by scanning a 7 high quality undiscovered gems that highlights companies with strong fundamentals that many investors may still overlook.
- Strengthen the defensive side of your portfolio by working through a list of solid balance sheet and fundamentals (5 results) that focuses on firms with sturdier financial foundations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com