


Event overview and why VTAMA matters for Organon
Organon (OGN) has put VTAMA cream back in focus after flagging a fresh Phase 3 data analysis in moderate to severe atopic dermatitis for presentation at a major allergy and immunology meeting.
The new readout looks at how VTAMA performed across different patient subgroups, including those with varying levels of body surface area affected and other baseline characteristics. That kind of slice of the dataset can help you judge how broad or narrow the clinical effect might be across real world patients.
VTAMA already carries indications in plaque psoriasis in adults and atopic dermatitis in adults and children from 2 years of age, which makes this closer look at outcomes in atopic disease especially relevant. For anyone tracking Organon shares, it connects directly to how durable and versatile the dermatology portfolio could be within the wider mix of women’s health, biosimilars, respiratory treatments and other established therapies.
- The cream is described as the only aryl hydrocarbon receptor agonist with approvals in both plaque psoriasis and atopic dermatitis in these populations.
- The atopic dermatitis development program, branded ADORING, included two 8 week pivotal trials and a 48 week open label extension that together form the backbone of the current evidence base.
- Safety data across plaque psoriasis and atopic dermatitis highlight a range of observed adverse reactions, from folliculitis and nasopharyngitis to upper and lower respiratory tract infections, which help frame benefit risk discussions for prescribers.
For investors, this sort of scientific update often sits a step removed from near term revenue or earnings, yet it can still inform views on how differentiated a product really is within a crowded topical dermatology market. As that information filters through clinicians, payers and regulators, it can feed into expectations about prescribing patterns over time.
Organon’s VTAMA update lands after a steep re rating, with the share price at US$13.87 and a year to date share price return of 91.57%, while the 1 year total shareholder return of 106.24% and 3 year total shareholder return of 36.65% suggest strong momentum despite a 5 year total shareholder return that declined 49.84%.
Recent headlines have mixed this dermatology data with an October quarterly report that showed US$1,574 million of third quarter sales and a small uplift in net income, along with a US$0.02 quarterly dividend affirmation. Together, these events can influence perceptions of both Organon’s growth options and its income profile, which helps explain why sentiment around the stock has been firming rather than fading.
Spot similar healthcare stories in motion by scanning our hand picked 35 healthcare AI stocks that are riding fresh data readouts and pipeline catalysts of their own.Organon now has fresh VTAMA data and a sharp share price recovery on the table. The business looks stronger. The question is whether the current valuation already reflects that shift.
Most Popular Narrative: 34% Overvalued
Organon’s most followed valuation narrative pegs fair value at $10.33, well below the last close at $13.87. This suggests the recent rebound may be running ahead of those underlying assumptions.
“The current valuation implies the share price already credits Organon with durable free cash flow around recent levels and a successful pivot toward biosimilars and late-stage business development despite policy headwinds, higher interest costs and a reduced dividend, which leaves limited room for disappointment.”
See why 35 investors see Organon as 34% overvalued.
Result: Fair Value of $10.33 (OVERVALUED)
Still, if Organon’s off patent brands prove more resilient, or if Nexplanon and MIUDELLA gain traction faster than analysts model, that bearish valuation narrative could be tested.
Find out about the key risks to this Organon narrative.
Another View: Organon Through A Cash Flow Lens
Analysts leaning on price targets see Organon as about 34% overvalued at $13.87 versus a fair value of $10.33. Our DCF model points in the opposite direction, with a future cash flow value of $93.92 per share. That gap is very large. Which signal do you put more weight on?
Look into how the SWS DCF model arrives at its fair value.
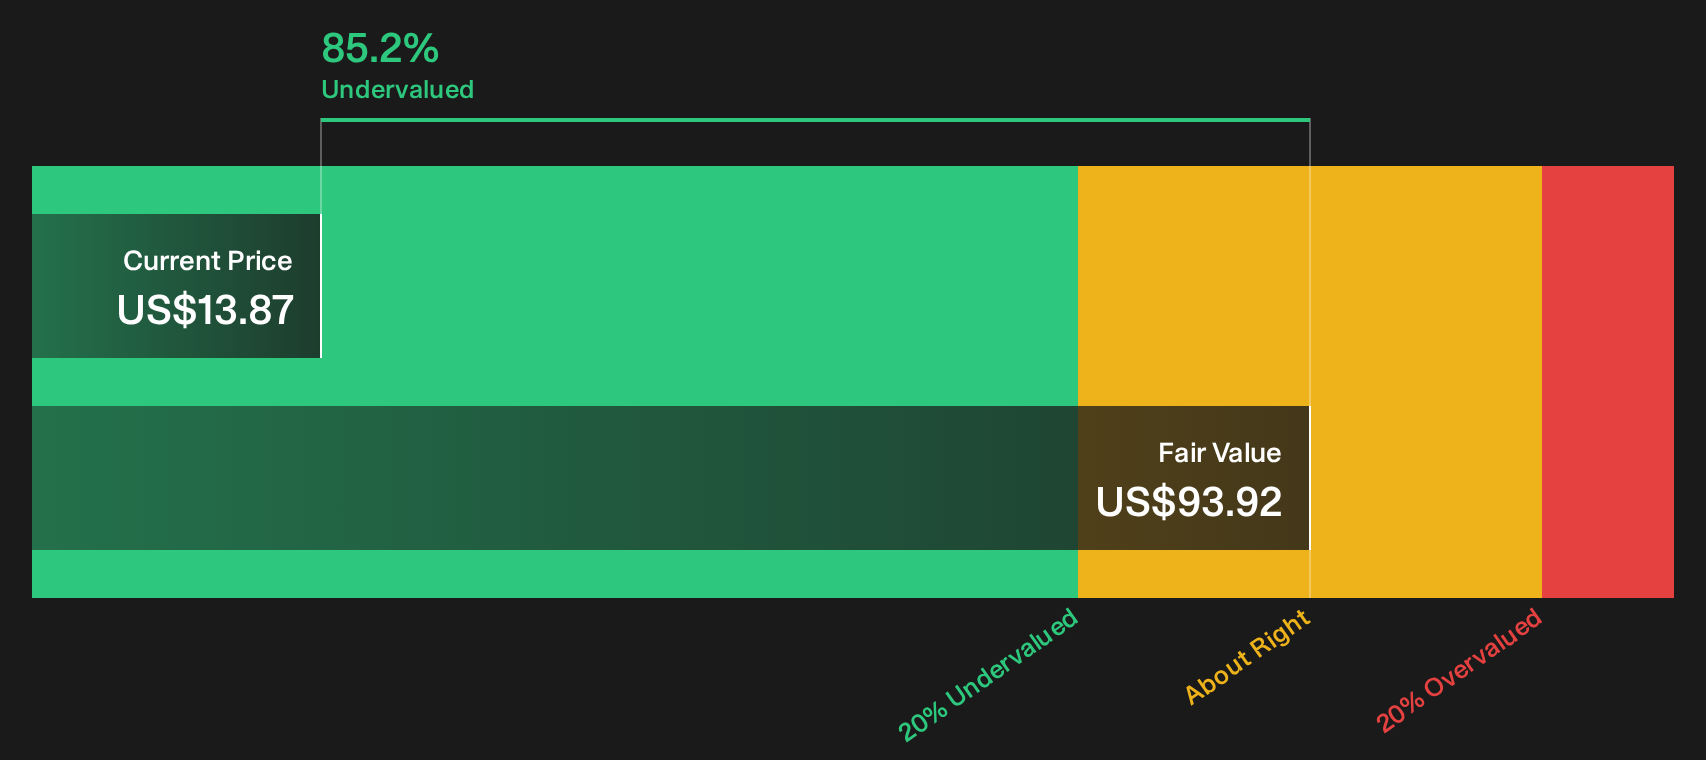
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Organon for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and caution around Organon feels familiar, use it as a prompt to move fast and pressure test the numbers yourself with 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Organon?
You have already done the hard work by digging into Organon. Do not stop there when a wider opportunity set is only a few clicks away.
- Target steadier opportunities by scanning a 29 resilient stocks with low risk scores that groups companies with more resilient profiles and lower overall risk scores.
- Hunt for value by reviewing a 39 high quality undervalued stocks that highlights quality businesses trading below their assessed worth with solid fundamentals backing them.
- Spot rising potential by checking a 19 high quality undiscovered gems that surfaces lesser known companies with strong financial underpinnings before wider attention arrives.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com