


- BioMarin Pharmaceutical reported third quarter 2026 revenue of US$1,024.65m and a net loss of US$122.83m, and also updated full year 2026 revenue guidance to a slightly lower range of US$3.8b to US$3.9b.
- The combination of higher revenue and a wider quarterly loss suggests BioMarin Pharmaceutical is carrying heavier costs or investments that are weighing on profitability even as sales rise.
- Now the focus turns to how BioMarin Pharmaceutical's investment narrative absorbs a wider Q3 loss and a trimmed 2026 revenue guidance range.
See how BioMarin Pharmaceutical fits into the wider biotech opportunity set by comparing it with a hand-picked 35 healthcare AI stocks that may be shaping the next wave of healthcare breakthroughs.
BioMarin Pharmaceutical Investment Narrative Recap
To own BioMarin Pharmaceutical, investors need to believe that a broad rare disease portfolio can eventually translate into cleaner profitability and better use of capital. The latest quarter points in the opposite direction. Revenue for the three months to September 30, 2026 reached US$1,024.65m, yet the firm reported a net loss of US$122.83m and a wider loss per share.
The near term debate centers on whether management can tighten costs while still funding pipeline programs and integration work. Full year 2026 revenue guidance was nudged down to a range of US$3.8b to US$3.9b, which slightly dents the growth narrative. The biggest current risk is that margins remain under pressure while product and deal spending stays elevated.
The most relevant recent development for this earnings release is the exclusive worldwide license agreement for HM15421/GC1134A, a long-acting enzyme replacement therapy for Fabry disease. BioMarin Pharmaceutical is paying US$70m upfront, with up to US$405m in potential milestones plus tiered royalties, and will take on development, manufacturing and commercialization outside Korea.
This deal fits directly into the rare disease portfolio catalyst that many shareholders focus on, but it also reinforces the core risk. Execution on later stage trials and eventual commercialization will matter for returns on this added capital. Until the therapy progresses, that upfront outlay and future commitments sit against a backdrop of current losses and already scrutinized margins.
What The Analyst Framework Implies For BioMarin Pharmaceutical
Analysts framing BioMarin Pharmaceutical's outlook are effectively tying today’s rare disease spending to a much larger profit pool several years out. Their core model uses forecast revenue growth of 14.0% a year and assumes that profit margins move from 2.1% today to 24.6% in three years. On that basis, consensus points to earnings of US$1.2b by about 2029, compared with US$73.0m of earnings today, which is an increase of roughly 16x. The same framework anchors on 2029 revenue of US$5.1b and treats 2029 as the key estimate year for both income and earnings forecasts.
BioMarin Pharmaceutical's narrative projects US$5.1b revenue and US$1.2b earnings by 2029. This requires 14.0% yearly revenue growth and an earnings increase of roughly 16x from US$73.0m of earnings today.
Uncover why BioMarin Pharmaceutical's fair value indicates a 64% potential upside to its current price, which could narrow quickly.
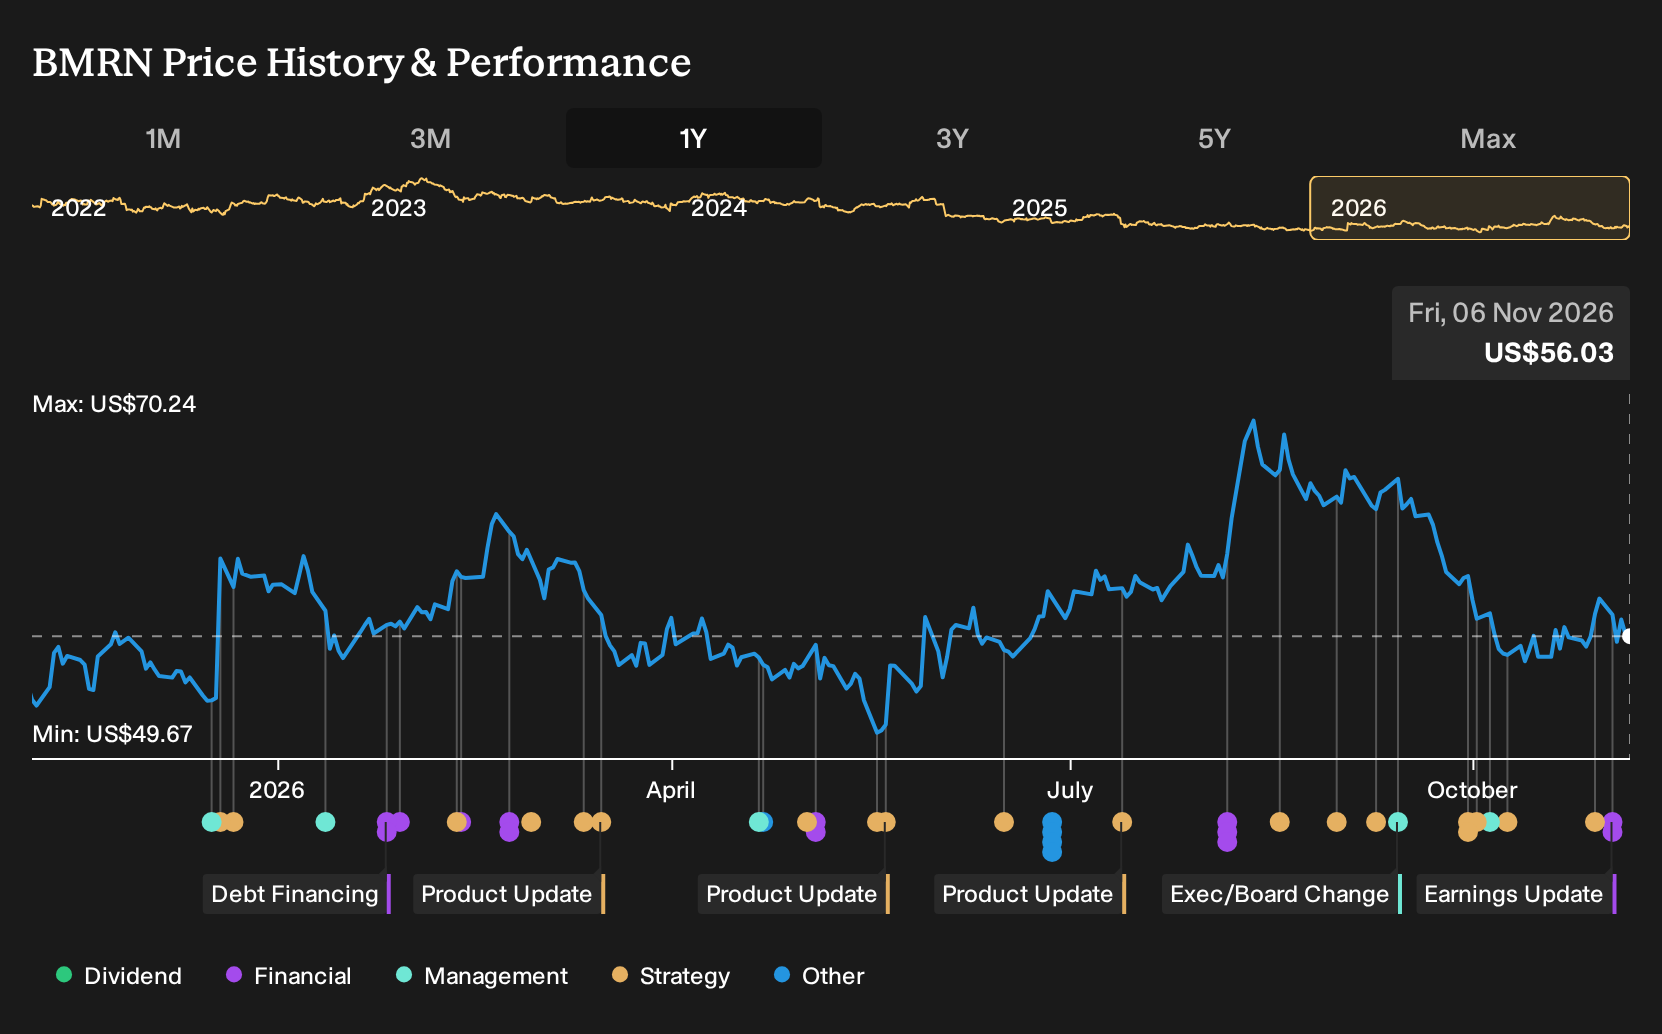
Exploring Other Perspectives
Some of the most optimistic analysts focus on a different catalyst for BioMarin Pharmaceutical. They highlight potential expense savings from the Amicus deal and were modeling about US$5.6b in revenue and US$2.4b in earnings by 2029, before this Q3 loss and guidance cut. You can compare those upbeat projections with your own read of today’s results and decide how much the story might now shift.
Explore 5 other BioMarin Pharmaceutical fair value estimates, including one that suggests as much as 295% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your independent analysis.
- A great starting point for your BioMarin Pharmaceutical research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for BioMarin Pharmaceutical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BioMarin Pharmaceutical's overall financial health at a glance.
Looking For More Investment Ideas Beyond BioMarin Pharmaceutical?
Once you have formed a view on BioMarin Pharmaceutical, it can help to place that opinion in a wider watchlist of potential opportunities. The Simply Wall St Screener lets you quickly filter for different types of stocks that might suit your return goals and risk comfort.
- If capital preservation and steadier price moves matter to you, consider focusing on companies that show resilient fundamentals through a 29 resilient stocks with low risk scores.
- If reliable income is a priority, you can zero in on higher yielding businesses by scanning a curated 8 dividend fortresses that may offer more predictable cash returns.
- If you are hunting for future leaders before they are widely followed, broaden your research with a 19 high quality undiscovered gems that filters for under-the-radar stocks with solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com