


Exelon has delivered a 39.5% share price gain over the past five years, and fresh headlines around big grid and storage plans are keeping the story in focus. The key issue for anyone looking at the stock today is whether that track record and new investment push are matched by its earnings profile.
- Over a 5 year window, Exelon stock has returned 39.5%, which puts real weight on the question of whether current earnings can carry that performance further.
- Planned spending of up to about US$8b on energy storage and related projects can influence future earnings power, but it also affects how quickly those profits may emerge relative to the cash going out today.
- Your read on Exelon is one view; the desks covering it have another. See what analysts think Exelon's shares could be worth.
The issue now is whether Exelon’s current share price around US$45.62 is appropriately aligned with what its earnings suggest it should be worth.
If you are weighing Exelon against other grid and storage plays, it can help to compare this earnings question across a wider set of 42 power grid technology and infrastructure stocks
Is Exelon a Bargain on Earnings?
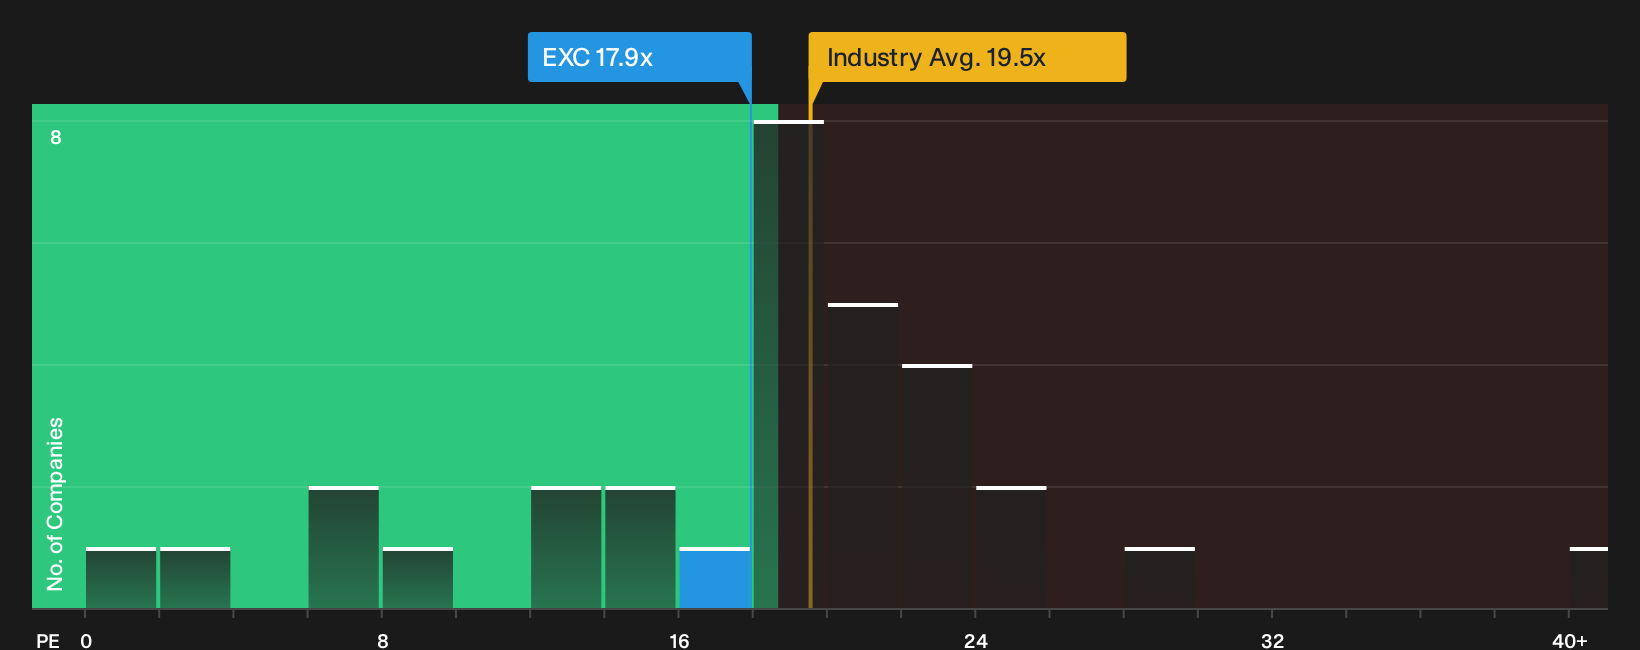
The P/E ratio suits Exelon because earnings remain a key anchor for a regulated utility where cash flows are closely tied to approved rates and capital plans. On this measure, Exelon trades on about 17.9x earnings, which is a little lower than the Electric Utilities industry average of roughly 19.5x and slightly below the peer group at about 18.8x.
Because of that planned US$8b grid and storage build out, investors are clearly weighing near term spending against the earnings base that supports today’s price. On a tailored fair value framework that factors in Exelon’s growth profile, profitability and risk, the current P/E appears below the level suggested by those fundamentals. This points to the shares looking undervalued on this metric. Despite the recent Q3 2026 earnings beat and reaffirmed capital plan keeping interest high, the P/E still prices Exelon at a discount to what this model implies. Explore the numbers behind Exelon's P/E valuation.
The Exelon Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E discussion leaves off by spelling out which expectations about Exelon’s future growth, profitability and earnings path would need to hold for the current valuation to look either stretched or conservative, and they sit on the stock’s Community page. Rather than relying on a single ratio or model result, each one sets out the key inputs behind its fair value view so you can compare those assumptions with actual quarterly outcomes as they are reported.
One of the top community narratives on Exelon: roughly fairly valued
"The key execution priority is the rebalanced capital plan, including limiting adjusted O&M growth to no more than 2% and delivering the planned capex…"
Discover why this Narrative puts Exelon at roughly fairly valued.
One More Angle On Exelon That Could Change How You See It
Before you get comfortable with where Exelon sits on earnings and capital plans, it is worth checking the specific risk checks our research has flagged and deciding how much weight they carry for you. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com