


BXP (BXP) stock is in focus after the real estate investment trust reported third quarter 2026 earnings that moved from a net loss to a profit and lifted its full year earnings outlook.
At a share price of US$65.01, BXP has seen a 1 month share price return of 9.41%, even though the 90 day share price return is down 6.74% and the year to date share price return is down 4.14%. That near term rebound contrasts with a 1 year total shareholder return that is down 5.96%, a 3 year total shareholder return of 44.83% and a 5 year total shareholder return that is down 28.34%. Taken together, these figures point to momentum rebuilding recently after a mixed longer term experience for investors.
Scan for other REITs showing fresh earnings momentum and recently upgraded guidance by reviewing the hand picked 39 high quality undervalued stocks that may be offering similar setups to BXP.
BXP has already logged a sharp short term bounce on stronger earnings and higher guidance, yet much of the longer term return record is still in the red. How much of any valuation reset is actually priced in?
Most Popular Narrative: 12.5% Undervalued
BXP closed at $65.01, while the most followed narrative pegs fair value at $74.30 using a 9.0% discount rate. This frames the recent bounce as only a partial rerating in the eyes of those followers.
Premier workplaces in BXP's core CBD markets, which have lower vacancy and more than 60% rent premiums relative to broader office stock, leave room for the company to capture higher future pricing and occupancy as tenants cluster in top tier buildings, supporting revenue per square foot and cash flow.
See why 13 investors see BXP as 13% undervalued.
Result: Fair Value of $74.30 (UNDERVALUED)
Still, the bullish BXP narrative depends on refinancing risk remaining contained and on asset sales not dragging funds from operations more than guidance already suggests.
Find out about the key risks to this BXP narrative.
Another View: What BXP’s P/E Is Telling Investors
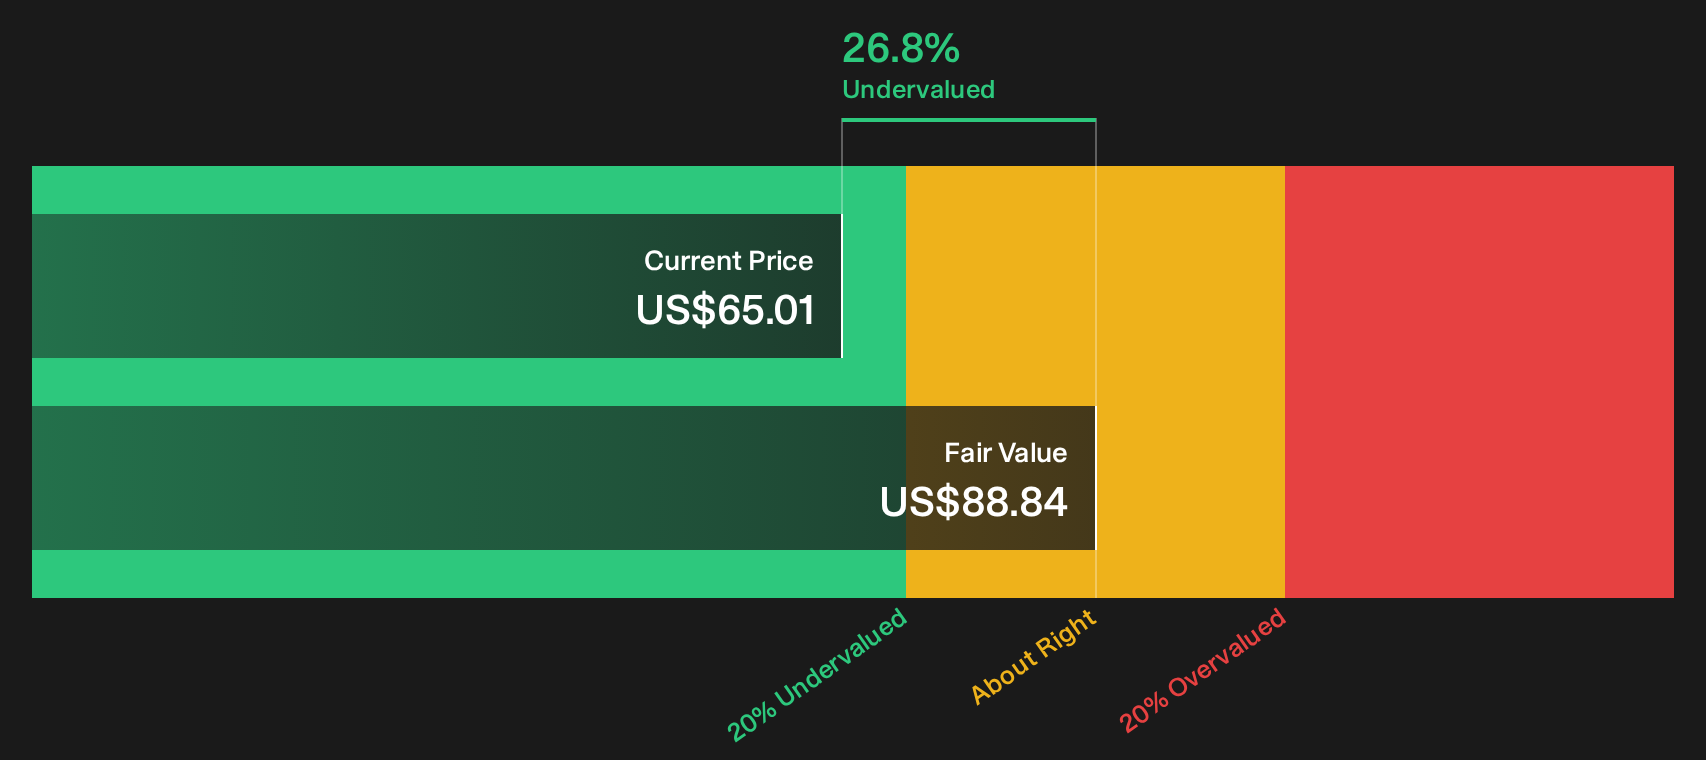
The DCF lens paints BXP as attractive, with the stock trading about 26.8% below an estimated future cash flow value of $88.84. The simple earnings multiple sends a cooler message. At 19.5x P/E, BXP trades richer than the Global Office REITs average of 16.8x, even though the fair ratio points to 27.5x as a level the market could move toward. That gap hints at upside if sentiment improves, but it also means anyone buying today is already paying more than the broader sector. Which signal carries more weight for you?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If the mixed tone on BXP leaves you torn, pull up the numbers while sentiment is still shifting and weigh the 2 key rewards and 4 important warning signs.
Ready For More Ideas Beyond BXP?
Do not stop with one REIT when the wider market is full of other setups that could fit your goals just as well or even better.
- Target potential mispricing by checking a hand picked 39 high quality undervalued stocks that blend solid fundamentals with prices that sit below many investors' radar.
- Strengthen your income stream by reviewing a curated group of 8 dividend fortresses that focus on higher yields backed by underlying cash flows.
- Dial down portfolio stress by scanning a focused 29 resilient stocks with low risk scores built around resilient balance sheets and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com