


SI-BONE has delivered a strong multi year share price run, and with the stock last closing at US$24.23 the live question is whether that price still lines up with the revenue the business is generating. For anyone watching SI-BONE today, the key issue is how much sales power the market is effectively paying for at this level.
- Over the past 3 years the stock has returned 53.8%, which puts real weight on the question of how its current valuation stacks up against the underlying sales base.
- Recent updates show double digit revenue growth alongside a smaller loss and improved adjusted EBITDA, which can influence how investors think about the scale and timing of future sales and cash generation that might be implied in the share price.
- There is a second opinion on SI-BONE worth weighing. See what analysts think SI-BONE's shares could be worth.
The issue now is whether the current US$24.23 price tag for SI-BONE is justified by the level and trajectory of its sales.
If you are weighing SI-BONE against other opportunities that put sales and balance sheets under the microscope, a focused stock screen can be a useful second starting point, such as solid balance sheet and fundamentals stocks screener (24 results).
Is SI-BONE Getting Expensive on Sales?
P/S fits SI-BONE because revenue is the cleanest reference point for a business that is still reporting a loss and is being judged heavily on sales momentum rather than current earnings.
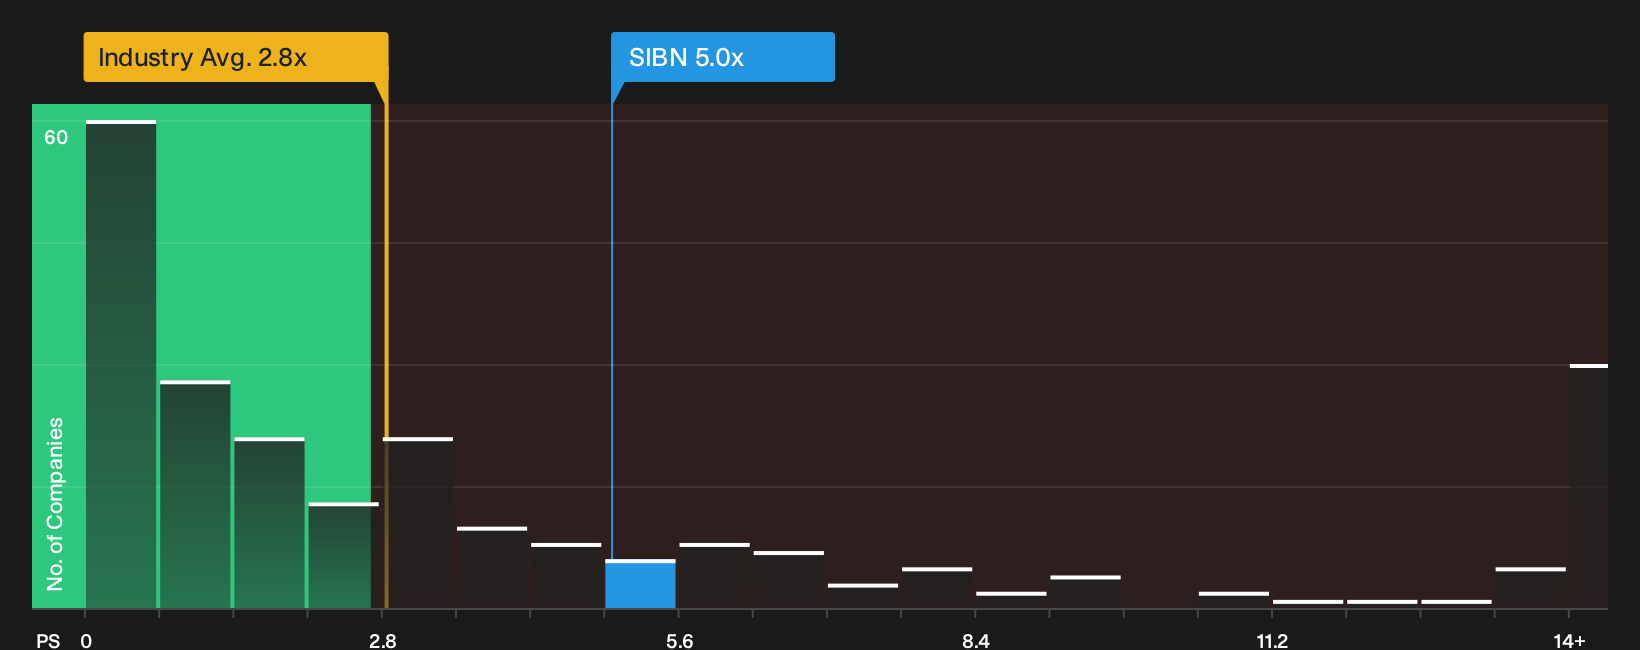
From this perspective, the stock trades on a P/S ratio of 5.0x, compared with a Medical Equipment industry average of 2.8x and a peer group average of 4.1x. Based on the tailored fair multiple for SI-BONE, which blends its growth profile, margins, size and risk, the current P/S appears to be on the expensive side. Recent Q3 2026 news around 15% revenue growth and improved adjusted EBITDA helps explain some of the enthusiasm reflected in that richer sales tag, although it also raises the bar for what the market expects from future execution. Explore the numbers behind SI-BONE's P/S valuation.
The SI-BONE Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for SI-BONE sit on the Community page and pick up where the valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to be worth materially more or materially less than it is today. Rather than a single multiple or model output, each scenario sets out the assumptions behind its view of fair value so you can compare those against SI-BONE's reported results over time.
Community views on SI-BONE are split between those who see more left in the story and those who think expectations already do much of the work.
Bull case: roughly fairly valued
"Continued expansion of SI-BONE’s physician base, with 1,715 unique physicians performing procedures in Q2 2026 and higher case volumes among repeat users, points to further utilization gains…"
Discover why this Narrative puts SI-BONE at roughly fairly valued.
Bear case: 5% overvalued
"The numbers imply the share price already reflects a fairly valued, optimistic case in which SI-BONE maintains high gross margins, continues to grow revenue in the mid-teens, and steadily improves adjusted EBITDA…"
Explore why this Narrative puts SI-BONE at 5% overvalued.
Before acting on SI-BONE's valuation, there is one more angle to check
Numbers tell part of the SI-BONE story, yet the people choosing where to invest cash, how fast to grow and how they are rewarded can tilt outcomes in subtle ways. See who runs SI-BONE and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com