


- Vallourec recently signed a new €750 million multicurrency revolving credit facility with a five year term and two optional one year extensions. This facility replaces previous credit lines and supports general corporate purposes on improved terms and with lower financing costs.
- The fresh revolving facility reflects lender confidence in Vallourec’s balance sheet and liquidity position. This is relevant for funding offshore, geothermal and other capital intensive projects while maintaining flexibility around working capital and shareholder returns.
- The next area of attention is how Vallourec’s improved €750 million credit facility might influence the broader investment narrative that investors are monitoring.
Compare Vallourec’s refinancing story with peers by reviewing hand picked companies on our screener of list of solid balance sheet and fundamentals (193 results).
Vallourec Investment Narrative Recap
To own Vallourec, you need to be comfortable with a business that is still heavily tied to oil and gas activity while working to ramp offshore and new energy contracts. The big near term swing factor is how well pricing and volumes in U.S. OCTG and offshore projects can offset logistics pressures and softer Mine & Forest demand.
The fresh €750 million revolving credit facility mainly tweaks the plumbing rather than the core thesis. It strengthens liquidity and flexibility, which may help Vallourec ride through freight, energy and insurance cost pressure. The largest current risk remains a sustained drop in drilling activity or prolonged logistics disruption.
The most relevant prior focus point for this new facility is Vallourec’s balance sheet and liquidity story. Analysts highlighted more than €2b in liquidity and a net cash position of US$183 million, alongside plans for sizeable shareholder returns and disciplined capex.
The new revolving line sits beside that context and shows how funding is being kept diverse and relatively flexible while the group targets higher margin offshore line pipe and new energy contracts. For you as a shareholder, the key question is whether execution on those contracts and cost programs turns this balance sheet flexibility into durable earnings and cash flow, while dividend coverage risks are managed carefully.
What Vallourec’s Analyst Assumptions Really Add Up To
Analysts are effectively asking you to underwrite a Vallourec story built on steady top line expansion, thicker margins and a leaner share count. The forecast now on the table assumes revenue grows at 9.9% a year for the next three years, while profit margins move from 9.6% today to 12.6% in that same window. Alongside that, the analyst base case points to outstanding shares declining by about 7% per year, which would amplify any earnings progress on a per share basis.
On the earnings line, the consensus view circles around profit of US$699.0 million by around 2029, compared with US$403.5 million today. That is a sizeable step up in absolute dollars, although the range of estimates is wide, from US$614.3 million at the cautious end to US$850.5 million at the optimistic end. The disagreement matters because it shows how differently forecasters are treating key swing factors such as U.S. OCTG pricing, offshore line pipe execution and the ramp in New Energies contracts.
Valuation assumptions are just as important as the operating inputs. For the current analyst price targets on Vallourec to line up with those earnings projections, the shares would need to trade on a P/E of 9.5x 2029 earnings. That compares with a multiple of 11.8x today, and with the GB Energy Services industry quoted at roughly 12.5x on current earnings. The framework in the Simply Wall St report applies a discount rate of about 7.3% to 7.35% when translating those future cash flows and earnings into a present value anchor.
On top of that, the valuation section assumes 2029 revenues of US$5.6b paired with the US$699.0 million earnings outcome. That pairing implicitly bakes in both the margin gains and the revenue growth path already discussed. If you are stress testing Vallourec’s story, the key judgment call is whether those mid teens profit margins and nearly US$700 million of earnings feel realistic given your own view on the drilling cycle, offshore project execution, logistics costs and New Energies progress.
Vallourec's narrative projects US$5.6b revenue and US$699.0 million earnings by 2029. This framework uses 9.9% yearly revenue growth and an earnings increase of about US$295.5 million from current earnings of US$403.5 million.
Uncover why Vallourec's fair value indicates a 38% potential upside to its current price that could narrow quickly.
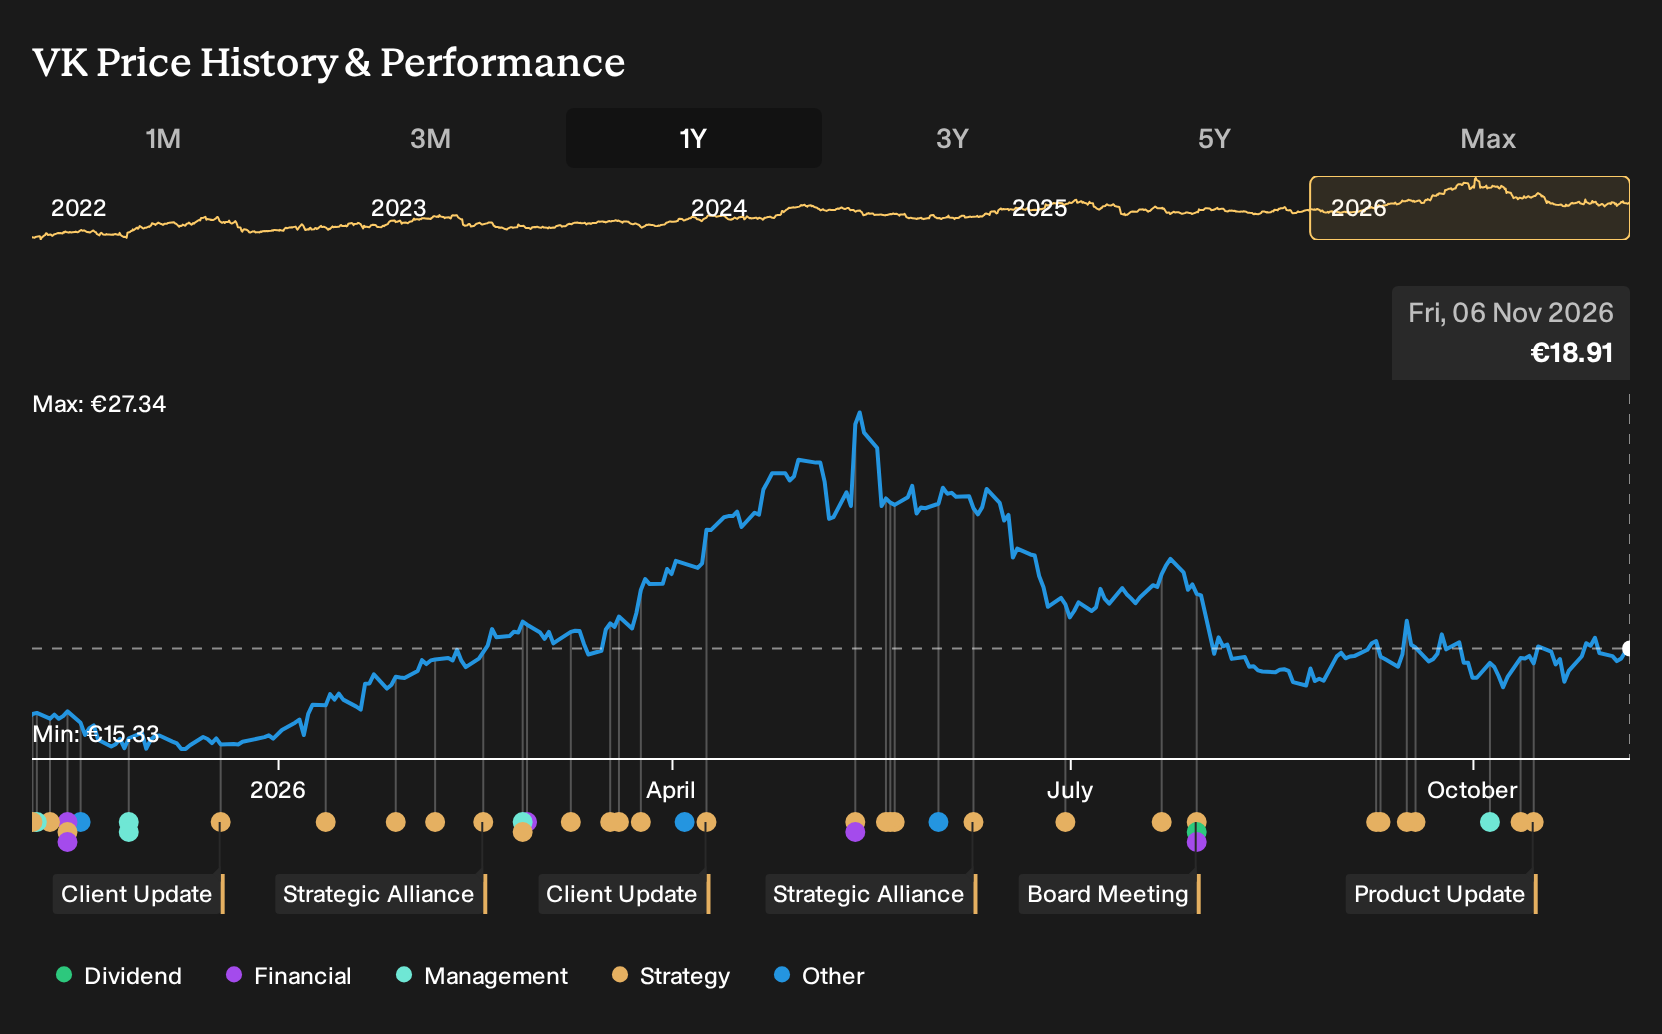
Exploring Other Perspectives
One alternative view on Vallourec leans hard on reinvestment risk. You are asked to worry that returning about €650 million to shareholders in 2026 and targeting roughly US$5.1b revenue and US$638.9 million earnings by 2029 already looked ambitious before this new credit facility. The most pessimistic analysts are clearly more cautious, so this refinancing could eventually push their narrative closer to or further from consensus.
Explore 4 other Vallourec fair value estimates, including one that suggests it could be worth just €21.77.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Vallourec research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Vallourec. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vallourec's overall financial health at a glance.
Looking For More Investment Ideas Beyond Vallourec?
If the Vallourec story has sharpened your thinking, use that same lens across a wider watchlist by casting the net over other businesses with clear balance sheets, resilient cash flows and different risk profiles on the Simply Wall St Screener.
- For investors who want financial strength to be front and center, start with a list of solid balance sheet and fundamentals (193 results) that pairs robust balance sheets with solid fundamentals.
- If value is the priority, scan a 225 high quality undervalued stocks that filters for quality businesses trading below what their fundamentals might justify.
- For those drawn to income resilience, review a 232 dividend fortresses that focuses on higher yielding companies where durability of payouts is a key feature.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com