


- Kalmar Oyj reported third quarter 2026 sales of €432.8 million and net income of €38.6 million. The company also booked new equipment orders including 10 electric straddle carriers for The Port of Virginia and a hybrid straddle carrier plus a reachstacker for Tropical Shipping.
- The Tropical Shipping deal introduces that customer’s first hybrid straddle carrier, highlighting practical demand for Kalmar Oyj’s lower fuel use equipment and the digital MyKalmar INSIGHT platform in real terminal operations.
- This article will examine how Kalmar Oyj’s investment narrative is shaped by these new electric and hybrid port equipment orders.
Scan beyond Kalmar Oyj and the latest port equipment contracts by reviewing hand-picked peers focused on resilient infrastructure and automation through the 89 robotics and automation stocks.
Kalmar Oyj Investment Narrative Recap
To own Kalmar Oyj, you need to believe that ports and logistics operators will keep prioritising automation, fuel efficiency and lower emissions, and that Kalmar can win a healthy share of that spend with its equipment and services. The recent Virginia and Tropical Shipping contracts fit this story but are small next to total €1,332 million nine month sales.
The more immediate swing factor is how order intake and margins hold up while U.S. demand has pockets of softness and price pressure remains in AMEA. The mixed quarter, with sales roughly flat year on year and quarterly earnings down, keeps execution risk on larger operational changes and electrification uptake firmly in focus.
The Port of Virginia order for 10 electric straddle carriers looks most relevant for the Kalmar Oyj catalyst debate. It directly addresses one key risk, the slow development in fully electric machine sales, by adding a concrete reference for zero emission equipment in a semi automated, high throughput terminal targeting net zero Scope 1 and 2 emissions by 2040.
For investors, this contract links decarbonisation demand to Kalmar’s eco portfolio and digital offerings, since Virginia already uses a large fleet of hybrid units and automation. The order is scheduled for delivery in the third quarter of 2027, so the near term focus stays on building backlog while managing tariff uncertainty, competitive pricing and operational changes without eroding profitability.
Kalmar Oyj's narrative projects €2.1b revenue and €225.3 million earnings by 2029. This assumes 4.5% yearly revenue growth and an earnings increase of about €51.9 million from €173.4 million today.
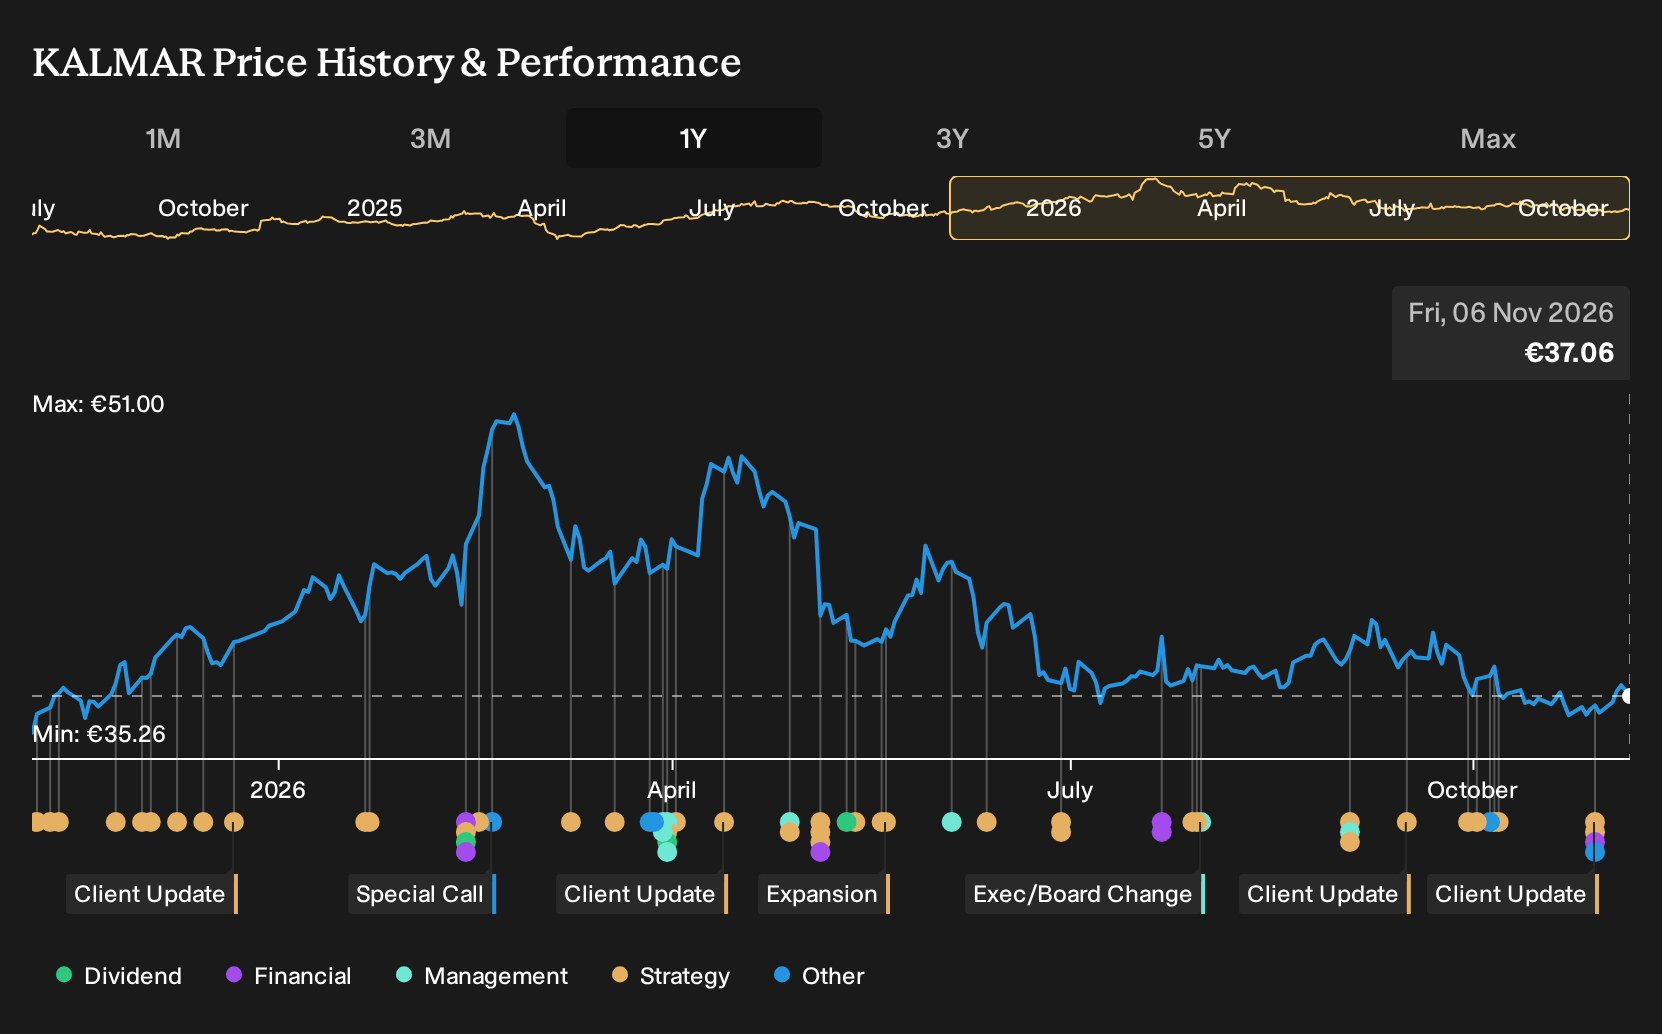
Uncover why Kalmar Oyj's fair value indicates an 18% potential upside to its current price before that discount to Kalmar Oyj closes.
Exploring Other Perspectives
Some of the lowest analysts focus on supply chain risk rather than new orders. They were modelling only 2.8% annual revenue growth to about €2.0b and earnings of €210.1 million by 2029. You can use those more cautious views as a reference point and decide whether the recent Kalmar Oyj contracts and China expo appearance might change that view.
Explore 2 other Kalmar Oyj fair value estimates, including one that suggests it could be worth just €42.20.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Kalmar Oyj research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Kalmar Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kalmar Oyj's overall financial health at a glance.
Looking For More Investment Ideas Beyond Kalmar Oyj?
Once you have a view on Kalmar Oyj, it can help to cross check that thesis against other opportunities that share similar qualities, whether you care most about value, balance sheet strength or keeping risk in check.
- If you want a starting point for value focused research, scan a curated set of companies that screen as attractively priced using our 225 high quality undervalued stocks
- For investors who put financial resilience first, compare Kalmar Oyj with businesses that carry robust balance sheets through the list of solid balance sheet and fundamentals (193 results)
- If your priority is limiting downside, narrow your watchlist to companies with relatively low risk profiles via the 212 resilient stocks with low risk scores
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com