


Glanbia (ISE:GL9) is back under pressure after Morgan Stanley cut its rating to Underweight. The bank argued that rising contracted whey costs and tougher competition could squeeze future margins and earnings relative to peers.
The downgrade has hit sentiment hard in the short term, with the share price falling 8.48% over the past day and 18.74% over 90 days, even though Glanbia still shows a 34.12% year to date share price return and a 62.47% total shareholder return over five years.
Scan beyond Glanbia and assess other potential rebound candidates using our curated list of 224 high quality undervalued stocks that already pair solid balance sheets with meaningful cash generation.
After a sharp reset in Glanbia’s share price, the question now is simple. Do current levels still offer an attractive trade off between whey cost risk and what you are paying for the underlying earnings power?
Most Popular Narrative: 19% Undervalued
Against Glanbia’s last close at €19.42, the most followed valuation storyline anchors fair value at €24.02 using a 6.39% discount rate. This frames the recent pullback as a move away from that narrative fair value rather than toward it.
Execution of a group wide transformation program, including a new global supply chain structure, IT operating model, automation and AI based tools, now targeted to deliver about $70m of annual savings by 2027 with around 40% expected by the end of 2026, gives Glanbia more room to improve EBITDA margin and earnings.
See why 16 investors see Glanbia as 19% undervalued.
Result: Fair Value of €24.02 (UNDERVALUED)
Still, the bullish story around Glanbia only holds if elevated whey costs do not erode Performance Nutrition margins and if the larger transformation program avoids execution missteps.
Find out about the key risks to this Glanbia narrative.
Another View On Glanbia’s Valuation
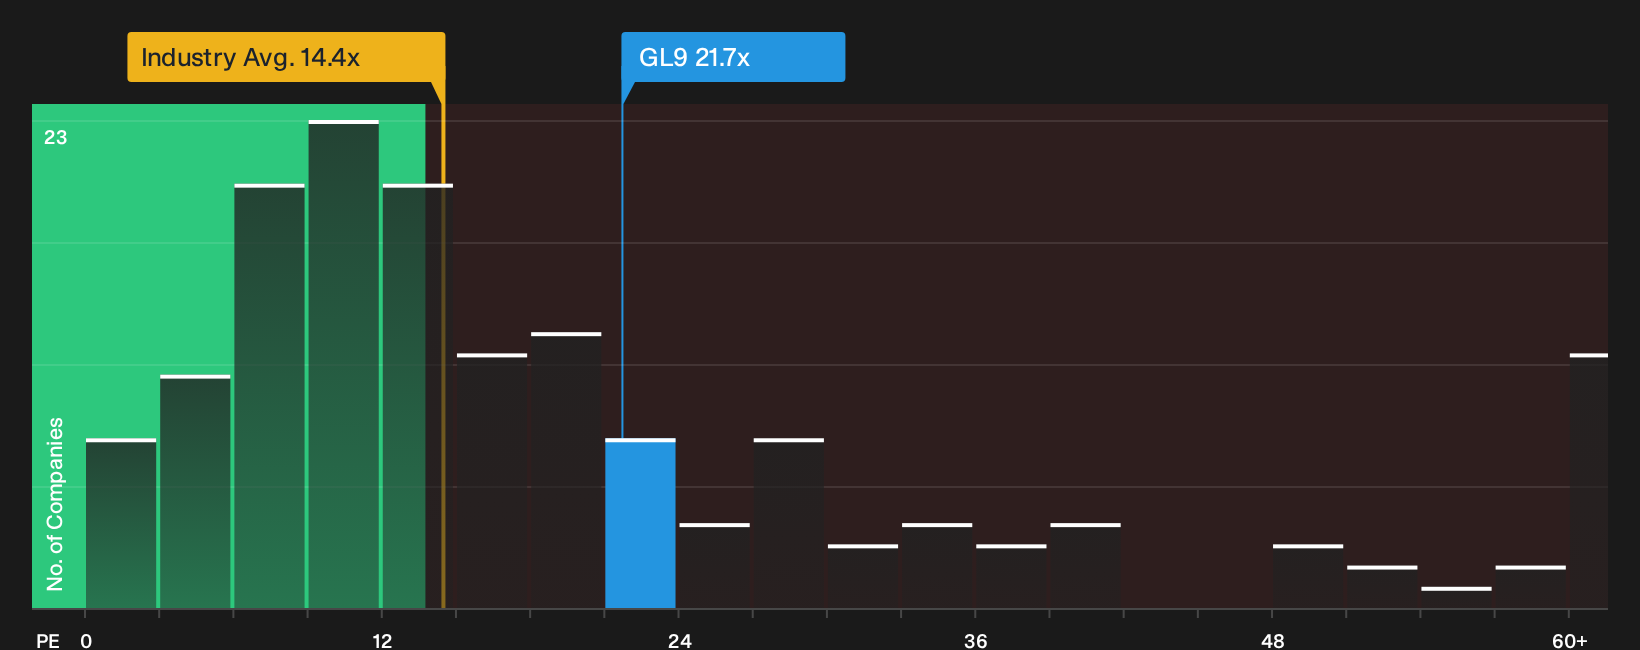
The fair value narrative puts Glanbia at €24.02, yet the market is currently asking investors to pay a P/E of 21.7x. That is above both peers at 20.8x and a fair ratio of 18.1x, which points to less safety margin if whey or execution risks bite.
Seen through this lens, the share price looks richer than the story. The key question is whether the earnings path can close that gap before the multiple moves closer to the fair ratio, or whether re rating risk does the work instead.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on Glanbia after this reset, or already leaning one way? Act while sentiment is still unsettled by weighing both sides of the story through 4 key rewards and 4 important warning signs
Hunting Beyond Glanbia: More Ideas To Act On Now
If Glanbia has you rethinking risk and reward, do not stop here. Put that same discipline to work by scanning wider opportunities before others move first.
- Target reliable income in a yield hungry market by reviewing 232 dividend fortresses that focus on robust payouts backed by underlying fundamentals.
- Identify potential value gaps early by running through the 588 high quality undiscovered gems that pair quality metrics with lower market attention.
- Dial up resilience when conditions turn choppy by filtering for 212 resilient stocks with low risk scores that score well on both financial strength and risk controls.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com