


Perrigo has returned 20.1% over the past year, yet the longer record is much tougher, and that mix of gains and past declines raises a clear question about whether the current share price makes sense relative to its sales. With the business reshaping its portfolio and refocusing on consumer self care, the key issue for you is how much sales power the market is now assuming this company has.
- Perrigo shares are down 53.9% over 5 years, which puts a lot of weight on whether the present valuation can now be supported by the revenue base that remains.
- The planned sale of the Infant Formula division and review of Oral Care may shift the mix toward higher margin consumer self care products, which can change how investors think about what each dollar of Perrigo’s sales is worth.
- Your read on Perrigo is one view; the desks covering it have another. See what analysts think Perrigo's shares could be worth.
The issue now is whether the price investors pay today for Perrigo is adequately backed by the sales the streamlined business is expected to generate.
To pressure test whether Perrigo's 20.1% one year rebound and portfolio reshaping fit your playbook, it helps to line it up against 39 high quality undervalued stocks.
Does Perrigo Look Undervalued on Sales?
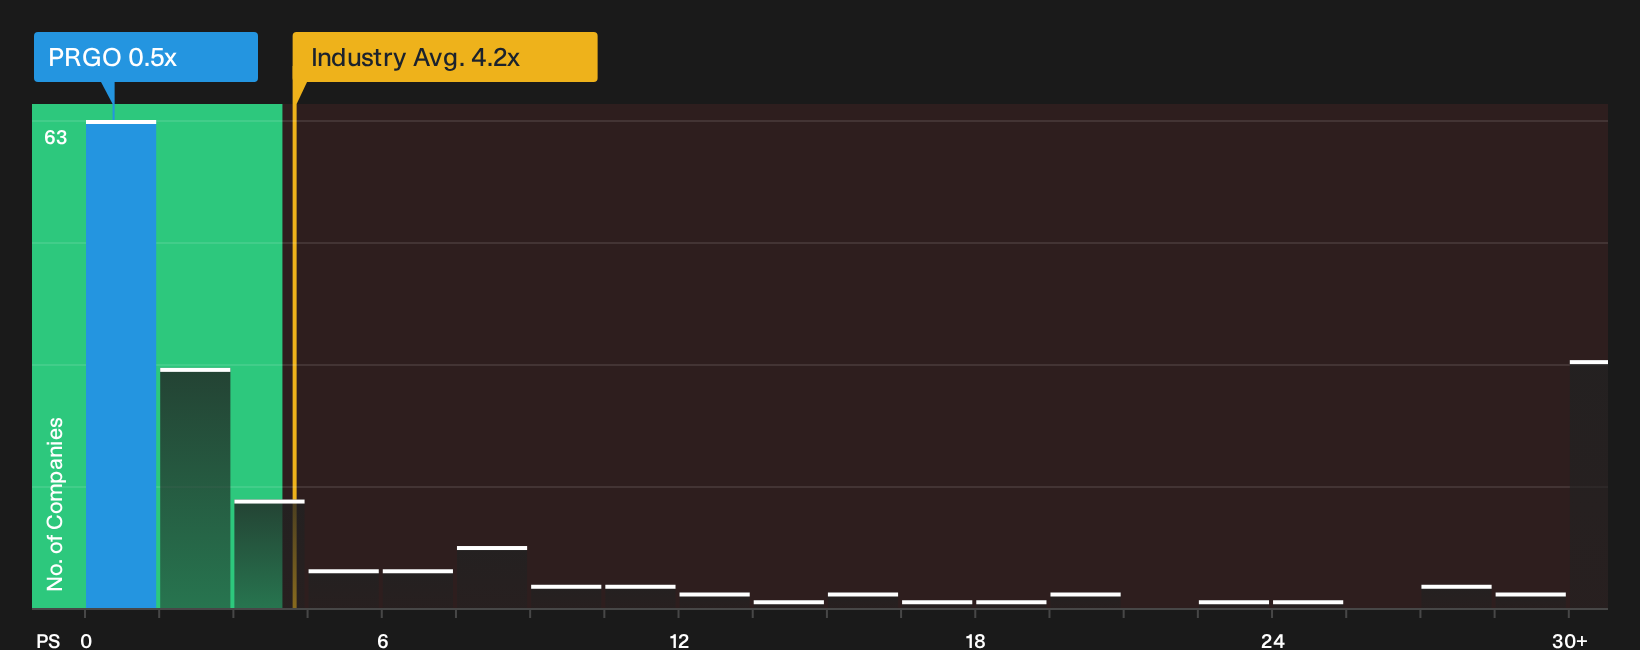
Perrigo lends itself to a P/S check because management is reshaping the business around consumer self care, where investors often anchor on how much they pay for each dollar of revenue. On this metric, the stock trades on a P/S of 0.5x, far below the Pharmaceuticals industry average of 4.2x and well under a peer group closer to 13.7x. That gap indicates the market currently prices Perrigo’s sales base at a steep discount to many other drug makers.
The fair multiple from the model, which blends factors like margins, growth profile, size and risk, sits above where Perrigo trades today. As a result, the shares screen as undervalued on this framework. Because the agreed sale of the Infant Formula arm simplifies the portfolio and shifts focus toward higher margin consumer products, the current low P/S suggests investors are not yet paying for that mix change. For anyone weighing whether the recent rebound has already used up the easy money, this compression in the sales multiple is the key figure to probe further. Explore the numbers behind Perrigo's P/S valuation.
The Perrigo Narrative: What Would Justify Today's Price?
Narratives on Perrigo act as the bridge between that compressed P/S multiple and what would need to happen on growth, profitability and earnings for the stock to be worth meaningfully more or less than today. Each scenario anchors a fair value to a particular mix of potential catalysts and risks, which helps you track over time which interpretation of Perrigo's future is actually playing out.
One of the top community narratives on Perrigo: 12% undervalued
"Portfolio simplification and operational efficiency initiatives are enhancing profitability, supporting innovation investment, and accelerating the company's financial deleveraging."
Discover why this Narrative puts Perrigo at 12% undervalued.
One more part of Perrigo that could change how you see the whole story
Valuation only tells part of the Perrigo puzzle, because the research also highlights specific risk checks that could tilt how you weigh everything you have just read. Take a closer look at 1 major warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com