


Applied Digital has swung from a very large three year gain to a sharply weaker recent share price. That puts fresh focus on whether the current US$15.55 level matches what its sales can reasonably support. With investors digesting heavy financing needs and shifting sentiment around data center operators, the key issue is how much revenue power the business is really being priced for.
- Over the past three years the stock has returned about 231.6%, so a lot of value on the table now hinges on how much sales growth the market expects from Applied Digital.
- Recent reports that quarterly interest expense has moved above base rent revenue and that a large portion of planned capacity still lacks committed funding can influence how investors think about future sales scale, timing and the capital required to reach it.
- Your read on Applied Digital is one view; the desks covering it have another. See what analysts think Applied Digital's shares could be worth.
The stock's next move may depend on whether that recent share price still lines up with the sales Applied Digital is generating and realistically aiming for.
If you want to stress test this same sales question across a broader slice of AI data center and infrastructure plays, scan through 52 AI infrastructure stocks.
Does Applied Digital Look Pricey on Sales?
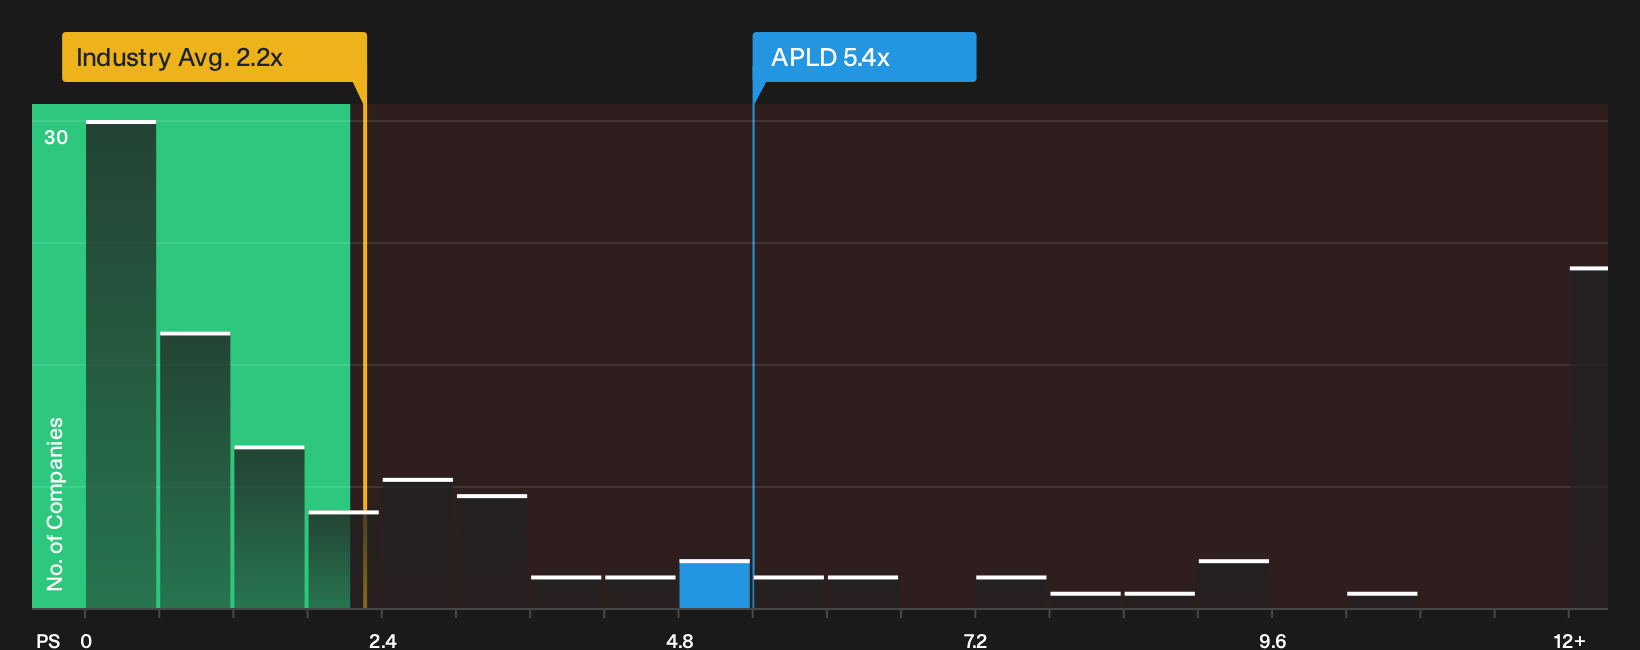
P/S fits Applied Digital because investors are currently focusing more on revenue capacity than on near term profits. On this metric, the stock trades on a P/S of about 5.4x, which is well above the broader IT industry average of roughly 2.2x and also above similar peers near 3.8x. That indicates the market is assigning a premium to each dollar of sales compared with many other tech infrastructure companies.
The fair value framework, which aligns the multiple with Applied Digital's own growth profile, margins, scale and risk, points to a lower P/S than the market is paying today, so the shares screen as overvalued on this measure. Because recent news highlighted that quarterly interest expense now tops base rent revenue and that a large chunk of planned capacity currently lacks funding, this richer P/S suggests investors are still paying up for revenue expectations even while financing questions remain front of mind. Explore the numbers behind Applied Digital's P/S valuation.
The Applied Digital Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Applied Digital's valuation puzzle leaves off. They spell out which growth, margin and earnings paths would need to hold for the stock to be worth materially more or less than today's price on the Community page.
Each Narrative ties a specific set of catalysts and risks to its own fair value estimate, so you can track over time which version of Applied Digital's story appears to be taking shape in the real world.
One of the top community narratives on Applied Digital: 74% undervalued
"The long term leasing agreements that Applied Digital has signed with Tier 1, investment grade hyperscalers now total about US$36b of contracted lease value across 1.41 GW of IT load…"
Discover why this Narrative puts Applied Digital at 74% undervalued.
One more Applied Digital check that belongs beside the sales multiples
Price tags tell only part of the story for Applied Digital, because the people directing capital allocation and the way their pay packages are structured can heavily influence where this business goes next. See who runs Applied Digital and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com