


Univest Financial (UVSP) just released a busy third quarter update, reporting a sharp rise in net loan and lease charge-offs, higher net interest income, softer quarterly earnings and a reaffirmed cash dividend.
At a share price of US$40.47, Univest Financial has achieved a 25.37% year-to-date share price return and a 39.36% total shareholder return over the past year. This comes even though the 90-day share price return has declined 5.53% as investors reassess risk after the charge-offs and weigh the longer-term 3-year total shareholder return of 149.72% against more recent volatility.
Capitalize on the renewed focus on bank risk management after Univest Financial's charge-offs by scanning our hand picked 29 resilient stocks with low risk scores that prioritize resilience when conditions change.So is Univest Financial’s pullback after those charge-offs telling you something new about the business, or just marking a shift in mood around the stock relative to where the numbers stand?
Most Popular Narrative: 11% Undervalued
On the most followed view of Univest Financial, the share price of $40.47 sits below an assessed fair value of $45.50. This puts the recent pullback against a backdrop of still constructive long term expectations and disciplined balance sheet management.
The main thing that has to go right is that Univest Financial continues to execute on higher margin commercial and construction lending, noninterest income growth, and expense discipline while managing event driven credit issues within guided provision levels.
The numbers and current narrative view that Univest Financial is fairly valued and bullish imply that the share price already reflects continued balance sheet discipline, mid single digit expense growth, guided 2026 net interest income growth of 8 to 10%, and ongoing capital returns through buybacks and dividends.
See why 0 investors see Univest Financial as 11% undervalued.
Result: Fair Value of $45.50 (UNDERVALUED)
Still, the story for Univest Financial can change quickly if event driven credit issues require heavier provisions or if intense deposit competition keeps funding costs remaining stubbornly high.
Find out about the key risks to this Univest Financial narrative.
Another Angle On Univest Financial’s Valuation
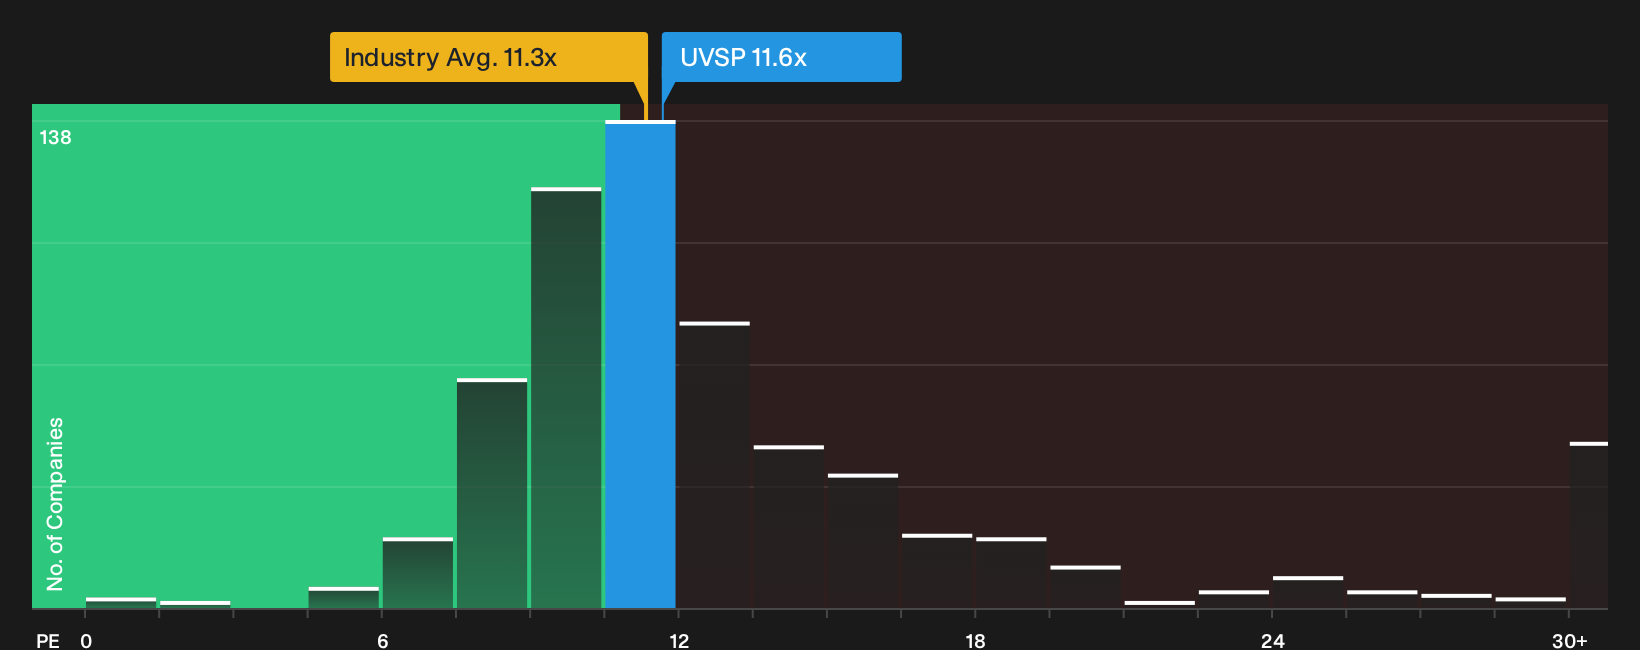
That 11% gap to the US$45.50 fair value uses a forward looking narrative built around earnings and cash flows. A simpler lens looks at Univest Financial’s 11.6x P/E, which is slightly above its 11x fair ratio and the 11.3x US banks average, so the market is already paying up a bit for the story here.
That premium is not huge, but it does narrow the margin for error if earnings or credit costs surprise you. It is worth asking which side of that valuation trade off you are more comfortable with: the modestly higher multiple, or the implied upside in the narrative model.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the mix of optimism and concern around Univest Financial matches your own read of the numbers? Move fast and stress test the thesis against both the upside and the caution flags by reviewing the 4 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Univest Financial?
If Univest Financial has sharpened your focus, do not stop here. Broaden your watchlist and pressure test your approach against other opportunities before the market moves on.
- Target potential mispricing by scanning a curated set of quality companies through the 39 high quality undervalued stocks.
- Strengthen your downside protection by zeroing in on financially robust businesses in the list of solid balance sheet and fundamentals (24 results).
- Hunt for under-the-radar opportunities by reviewing the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com