


GigaCloud Technology has seen its share price move sharply over recent years, which naturally raises a straightforward question for you as an investor: Is the current US$58.37 price broadly aligned with the cash flows the business can generate over time, or has the story moved ahead of the underlying money coming in the door?
- Over the past 3 years, GigaCloud Technology has delivered a very large share price gain, which puts a lot of weight on whether its future cash generation can live up to expectations embedded in that move.
- The company’s asset light marketplace model can support strong cash conversion and relatively low capital needs, which matters because it shapes how much free cash flow might ultimately be available to justify today’s valuation.
- Prefer to judge GigaCloud Technology on earnings? See what GigaCloud Technology's 12.3x P/E says about the price.
The stock's next move may depend on whether those projected cash flows, when discounted back using a Discounted Cash Flow (DCF) approach, stack up against the current market price.
If you want to test the same cash flow question you are asking of GigaCloud Technology across a wider field, compare it with 39 high quality undervalued stocks.
Is GigaCloud Technology a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) model here focuses on the cash GigaCloud Technology can return to shareholders over time. Latest twelve month free cash flow sits at about $133.3 million, and the projection for 2027 points to $129.9 million. That keeps the story anchored in solid, mid nine figure cash generation rather than speculative hopes.
The forecast path in this 2 Stage Free Cash Flow to Equity framework assumes free cash flow that broadly grows at low single digit rates over the coming decade, and then tapers into a more mature phase. On those inputs, the DCF projections put GigaCloud Technology's estimated intrinsic value substantially above the current share price of $58.37. For investors, the key question is whether the marketplace model can sustain those cash flows long enough for the gap between cash flow value and market price to close. Find out what GigaCloud Technology could be worth using our Discounted Cash Flow (DCF) estimate.
The GigaCloud Technology Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the GigaCloud Technology valuation puzzle leaves off by spelling out which combinations of future growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s price on the Community page. Each narrative ties a fair value estimate to a specific set of potential catalysts and risks for GigaCloud Technology, so you can track over time which version of the story is gaining traction.
GigaCloud Technology draws a split crowd, with one side leaning toward upside in the marketplace model and the other stressing governance and execution risk.
Bull case: roughly fairly valued
"Strengthening marketplace network effects, reflected in trailing 12 month GMV of US$1.7b, 26% growth in active 3P sellers and 17% growth in active buyers in Q2 2026…"
Discover why this Narrative puts GigaCloud Technology at roughly fairly valued.
Bear case: 10% overvalued
"Although GigaCloud Technology reports record revenue of US$412 million and net income of US$42 million in Q2 2026, the newly announced investigation into possible fiduciary breaches by its officers and directors introduces a governance and litigation overhang…"
Explore why this Narrative puts GigaCloud Technology at 10% overvalued.
One more angle on GigaCloud Technology that could change your view
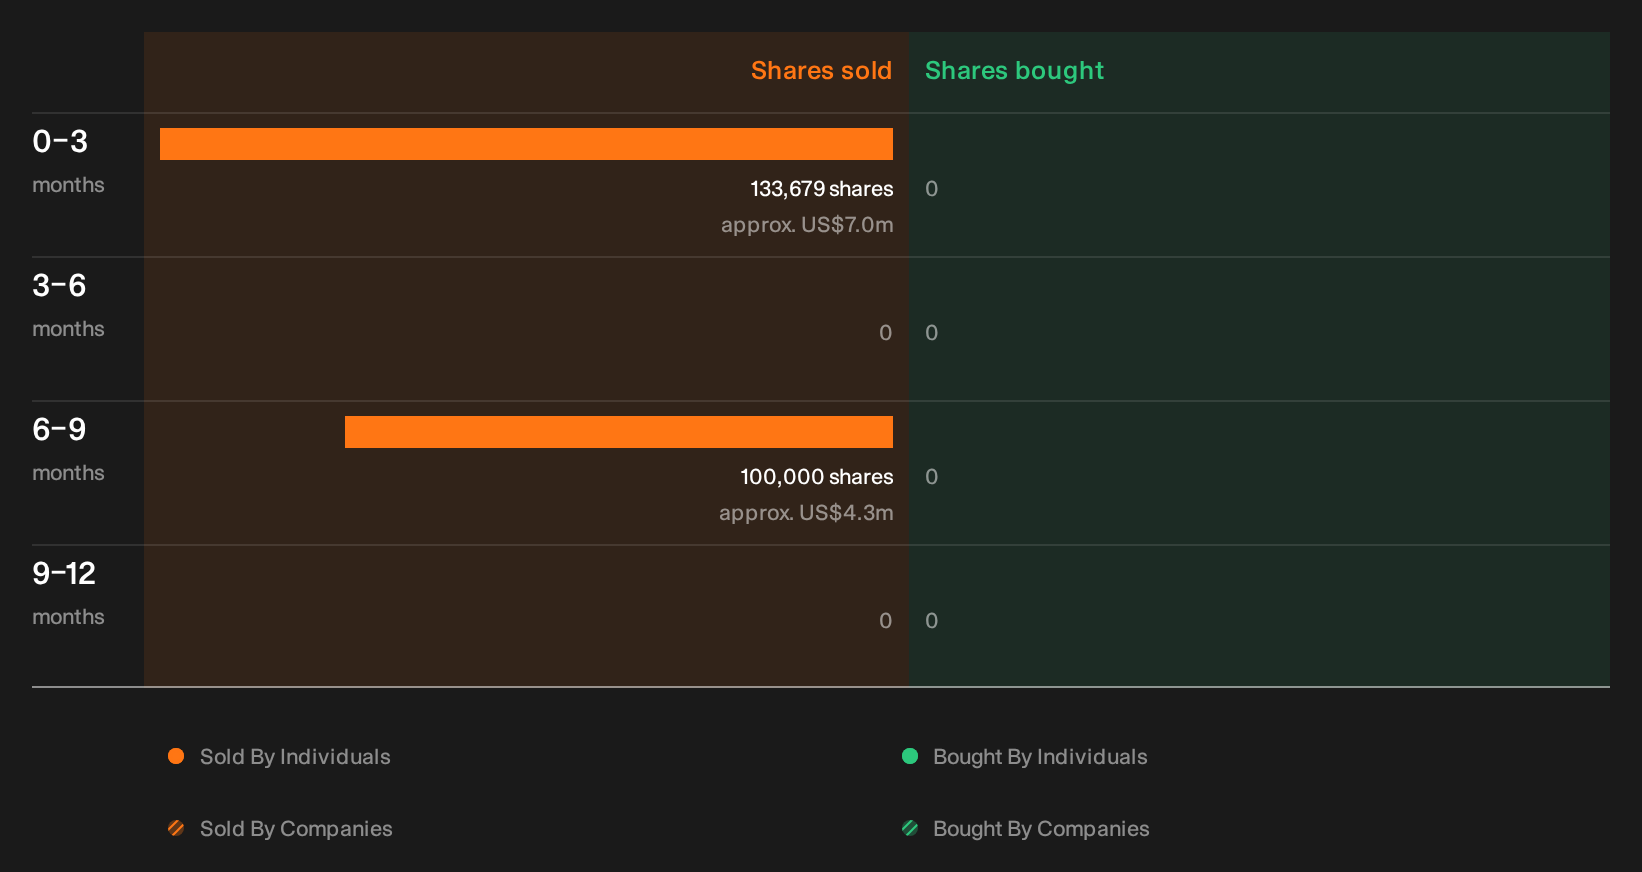
Beyond the cash flow story and competing narratives around GigaCloud Technology, recent activity by company insiders has raised a fresh question about who is selling, how much, and what that might signal for you as a shareholder. See the recent insider selling flagged for GigaCloud Technology.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com